Option Theta: Time Decay Explained
Table of Contents
Option theta is one of the most practical Options Greeks to understand — it tells you how much an option’s value erodes each day simply from the passage of time. For option buyers, theta represents the daily cost of holding a position. For option sellers, it represents a source of daily income. Whether you’re evaluating a directional trade, selling premium, or building a multi-leg strategy, theta is central to the risk/reward equation. For a complete walkthrough of all five Greeks, explore our Options Greeks course.
What is Option Theta?
Option theta (Θ) measures the rate of change of an option’s price with respect to the passage of time, expressed per day. It answers a simple question: how much value does this option lose overnight if nothing else changes?
A theta of −0.05 means the option loses approximately $0.05 per share ($5 per contract) each day due to time decay alone, all else equal. Long option positions typically have negative theta (time works against you), while short option positions have positive theta exposure (time works in your favor).
Theta is a first-order Greek — it is the partial derivative of the option’s value with respect to time (∂V/∂t). Unlike gamma, which is a second-order Greek measuring the curvature of the price curve, theta directly measures the daily erosion of the option’s extrinsic (time) value. Theta is typically negative for long calls and long puts in nearly all practical scenarios, with a rare theoretical exception for deep in-the-money European puts discussed in the Limitations section below.
The Theta Formula
Under the standard Black-Scholes model (European options, non-dividend-paying stock), theta is expressed as an annualized rate. The formulas below produce annualized theta; brokers typically display the per-day figure by dividing by 365 (calendar days) or 252 (trading days).
Where:
- N'(d1) — standard normal probability density function (PDF) evaluated at d1: N'(d1) = (1 / √(2π)) × e−d1²/2
- N(d2), N(−d2) — cumulative standard normal distribution evaluated at d2 and −d2
- S — current stock price
- K — option strike price
- σ — annualized implied volatility (as a decimal, e.g., 0.30 for 30%)
- T — time to expiration in years (e.g., 30 days = 30/365)
- r — risk-free interest rate (annualized)
- d1 and d2 — as defined in the delta formula: d1 = [ln(S/K) + (r + σ2/2) × T] / (σ × √T) and d2 = d1 − σ × √T
In practice, most traders read theta directly from their broker’s options chain rather than computing it by hand. Understanding the formula helps you see why ATM theta can accelerate near expiration (the √T in the denominator shrinks) and why near-ATM options typically have the largest theta magnitude (N'(d1) is maximized when d1 is near zero). For dividend-paying stocks like AAPL, the formula adjusts in two ways: the stock price term gains an e−qT discount factor, and additional carry terms involving q appear (e.g., ± q × S × e−qT × N(±d1)), where q is the continuous dividend yield. Always check whether your broker quotes theta per calendar day (÷365) or per trading day (÷252).
Interpreting Theta Values
Theta values vary widely depending on an option’s time to expiration, moneyness, and implied volatility. The ranges below are illustrative — actual values depend on the underlying’s price level, IV environment, and interest rates:
| Theta Range (per day) | Typical Scenario | Interpretation | Example |
|---|---|---|---|
| −0.01 to −0.03 | Long option, far from expiry | Slow, steady decay — time is eroding value gradually | 60-day OTM call on AAPL |
| −0.03 to −0.08 | Long option, moderate time | Noticeable daily erosion; decay is accelerating | 30-day ATM call on AAPL |
| −0.08 to −0.20+ | Long option, near expiry | Rapid decay — time value is disappearing fast | 7-day ATM call on AAPL |
| Positive exposure | Short option position | Time decay works in your favor — you collect theta daily | Short 30-day ATM put |
Theta is typically negative for long calls and long puts — time erosion works against the option buyer. Short option positions flip the sign: when you sell an option, you benefit from the same decay that works against the buyer. The theta value is quoted per share; multiply by 100 to get the per-contract daily impact (e.g., theta of −0.05 = −$5 per contract per day).
The Theta Decay Curve
One of the most important properties of theta is that time decay is not linear. For an option that remains near the money with other inputs fixed, the decay rate increases in magnitude as expiration approaches.
For an ATM option held at a fixed stock price and volatility, the time-value curve steepens near expiration. The share lost in the final 30 days depends on the starting horizon; it is not a universal two-thirds rule. In the hypothetical 60-day example below, 70.7% of the initial time value remains at 30 DTE and then decays to zero. This ATM acceleration reflects the √T term in the denominator of the Black-Scholes theta formula; away from the strike, the N'(d1) term can offset it.
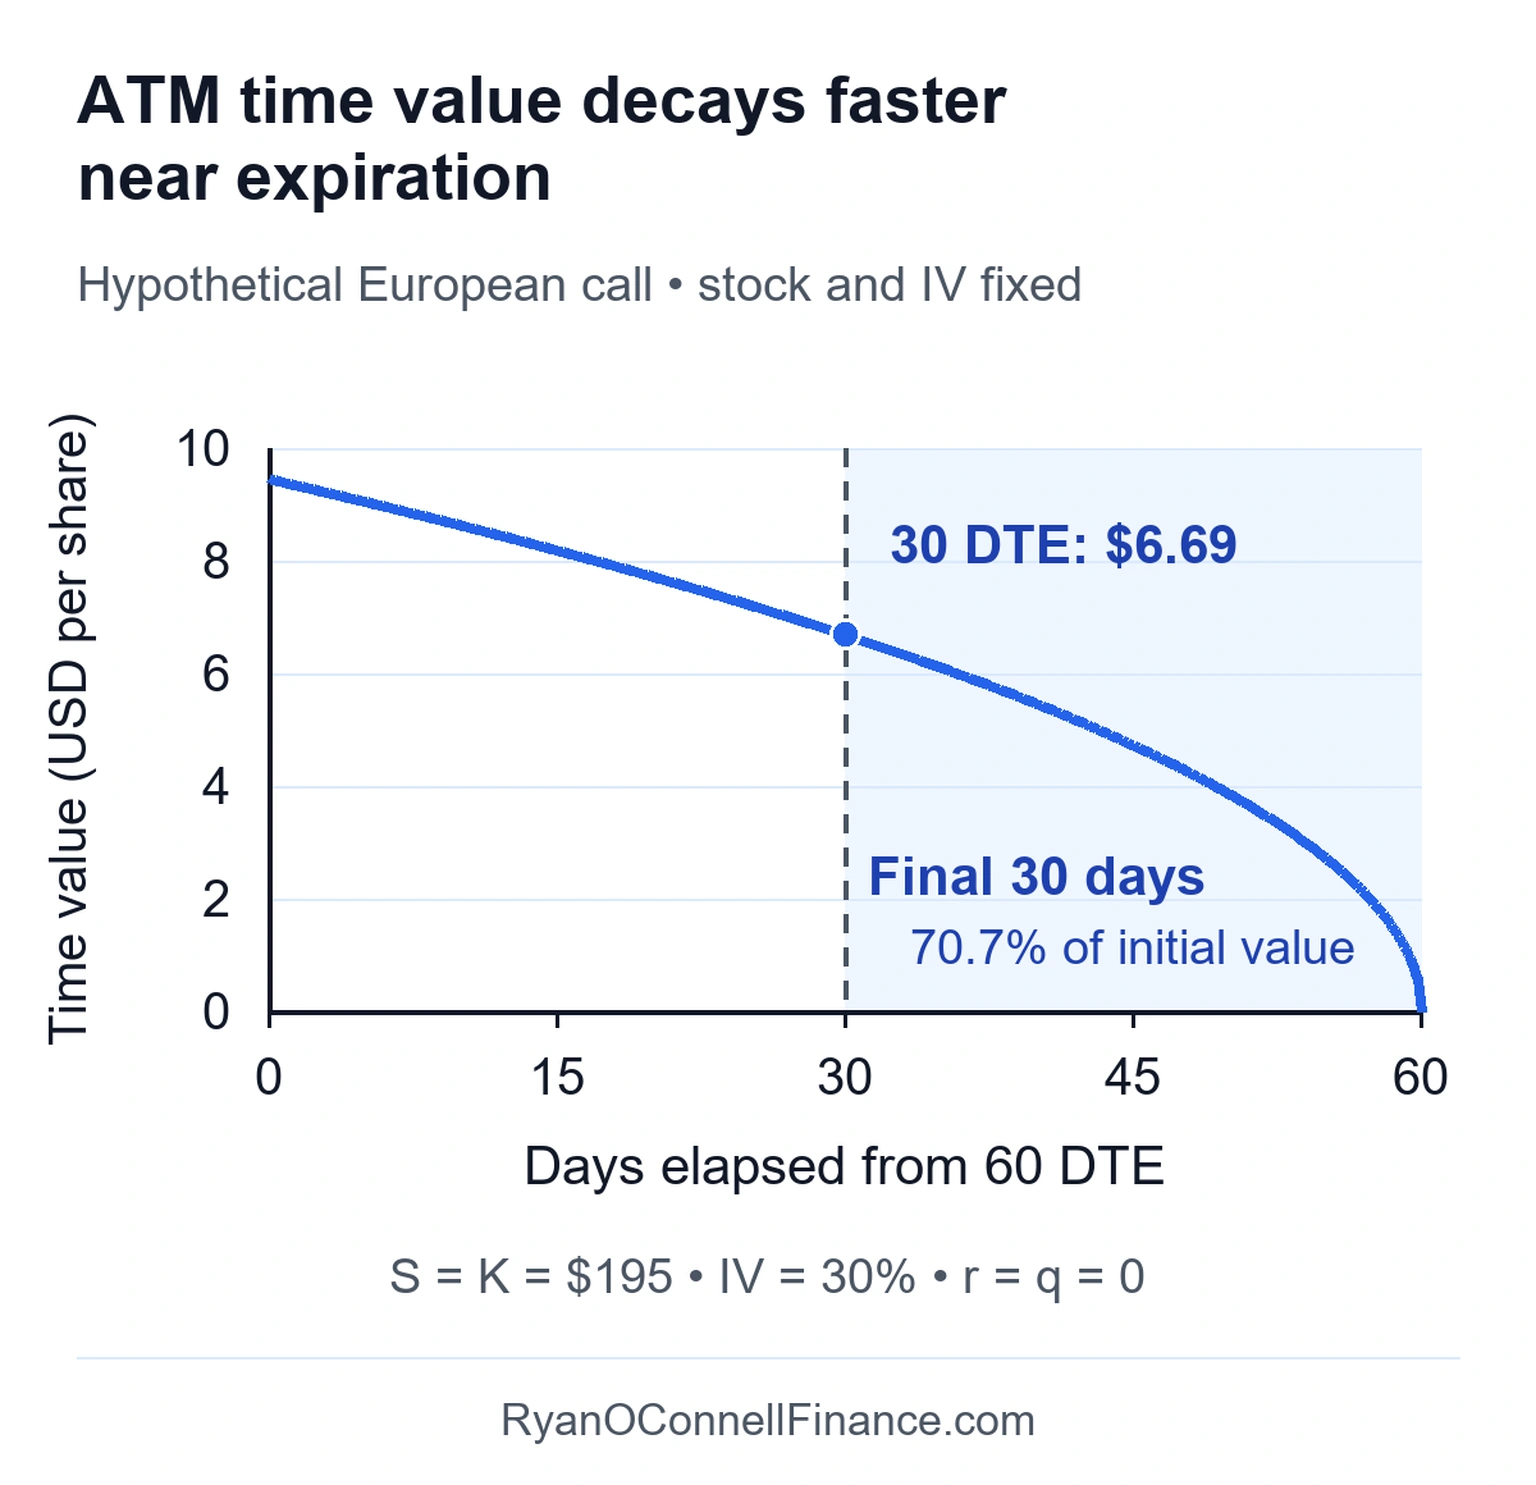
The curve is relatively gradual early on and steepest near expiration while the option stays ATM. This has direct implications for both sides of the trade:
- Option buyers with options that remain near the money face an accelerating headwind as expiration nears — each passing day takes a larger bite out of the remaining premium
- Option sellers benefit from this acceleration, which is why many premium-selling strategies target 30–45 DTE entry points — this range offers a favorable theta-to-gamma risk balance before the most extreme final-week decay
This non-linear behavior is closely related to the gamma-theta tradeoff: the same ATM options with the steepest theta also have the highest gamma. For option sellers, the richest theta income comes bundled with the highest gamma risk.
Theta Example
Let’s compare how theta affects two options with different expirations to see the decay curve in action.
Hypothetical setup: AAPL is trading at $195. Compare these illustrative quotes for two ATM call options at the $195 strike; they are a separate example from the model curves:
| Monthly (30 DTE) | Weekly (7 DTE) | |
|---|---|---|
| Price | $6.50/share | $3.10/share |
| Delta | 0.52 | 0.51 |
| Theta | −0.08/day | −0.18/day |
| Theta as % of premium | 1.2%/day | 5.8%/day |
5-day projection: Holding each quoted theta constant gives the following linear illustration, with each option starting at 100% of its own premium.
| Days elapsed | Weekly | Monthly |
|---|---|---|
| 0 | 100.0 | 100.0 |
| 1 | 94.2 | 98.8 |
| 2 | 88.4 | 97.5 |
| 3 | 82.6 | 96.3 |
| 4 | 76.8 | 95.1 |
| 5 | 71.0 | 93.8 |
Hypothetical constant-theta projection, normalized to each option’s starting premium. Other inputs held fixed.
The monthly loses $0.40 per share (6.2%), while the weekly loses $0.90 (29.0%) over five days. The weekly’s quoted daily theta is 2.25 times the monthly’s. Its buyer would need about a $1.76 favorable stock move ($0.90 ÷ 0.51 delta) to offset that projected theta drag under a constant-delta approximation.
The 5-day projection above holds theta constant. Theta itself changes as time passes and as stock price and IV move. If an option stays near the strike with other inputs fixed, its theta magnitude generally rises near expiration, so a fixed-theta projection can understate decay. Away from the strike, the pattern can differ. Treat multi-day theta projections as rough estimates, not precise forecasts.
Theta and Moneyness
Theta varies significantly based on how far the stock price is from the strike price. This is because theta erodes extrinsic (time) value, and the amount of extrinsic value differs by moneyness. For a full explanation of the intrinsic vs extrinsic value decomposition, see our Intrinsic vs Extrinsic Value guide.
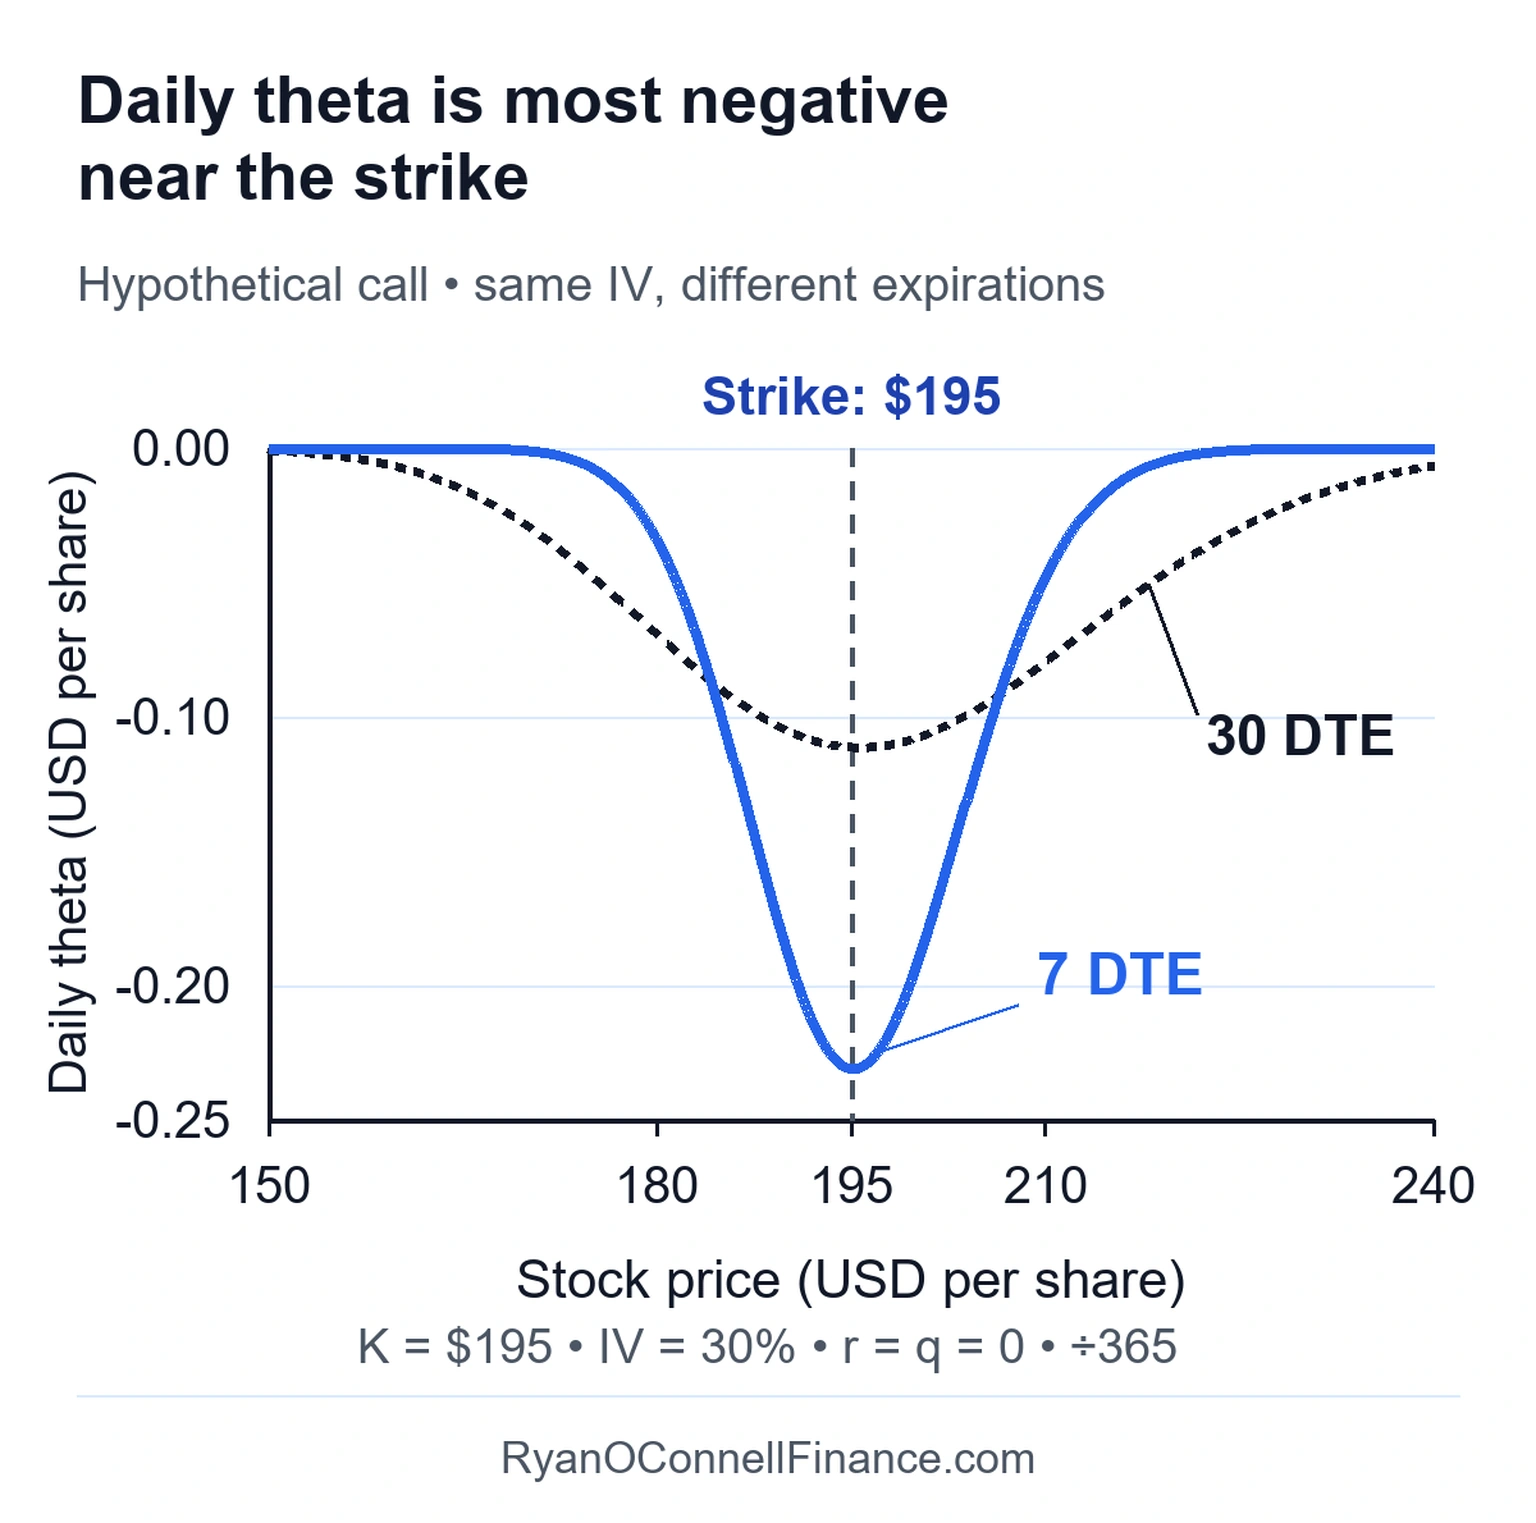
In this model example, daily theta near the $195 strike is about −$0.23 per share at 7 DTE versus −$0.11 at 30 DTE. The short-dated curve is also narrower: far from the strike, little time value remains to decay. The near-expiration acceleration is therefore an ATM pattern, not a rule for every strike.
| Moneyness | Theta Magnitude | Why | Practical Implication |
|---|---|---|---|
| ATM (at-the-money) | Highest | Maximum extrinsic value — the most time premium available to decay | Greatest daily erosion in dollar terms |
| ITM (in-the-money) | Moderate | Some extrinsic value remains, but intrinsic value is protected from decay | Less theta than ATM; option costs more overall |
| Deep ITM | Low | Mostly intrinsic value with little time premium left to erode | Minimal theta; option behaves more like the underlying stock |
| OTM (out-of-the-money) | Moderate | Entirely extrinsic value, but total premium is smaller than ATM | Lower dollar theta, but can be high as a percentage of the option’s price |
| Deep OTM | Low | Very little premium remaining | Low absolute theta, but the option is cheap — percentage decay can still be significant |
The key insight is that ATM options have the most extrinsic value, so they have the most to lose per day. OTM options have lower dollar theta, but because their entire premium is extrinsic, theta as a percentage of the option’s price can be deceptively high — making cheap OTM options particularly vulnerable to time decay.
Long Options vs Short Options Theta
The way theta affects your position depends entirely on whether you are buying or selling options. This distinction drives most options strategy decisions.
Long Options (Negative Theta)
- Theta works against you — your position loses value each day
- Near-the-money time decay can accelerate as expiration approaches
- Must overcome theta drag through stock movement or IV expansion to profit
- ATM options near expiry face the steepest daily erosion
- Theta is the cost of owning optionality and gamma exposure
- Near the money, longer-dated options typically have lower daily theta magnitude
Short Options (Positive Theta)
- Theta works in your favor — you collect time decay daily
- Premium-selling strategies (covered calls, credit spreads) rely on theta income
- Risk: losses from stock moves or IV expansion can exceed theta gains
- ATM options near expiry provide the highest daily theta collection
- Theta income is compensation for bearing gamma risk
- Highest theta collection comes with highest gamma and tail risk
This dynamic is the gamma-theta tradeoff at work. Long gamma positions benefit from large price moves (convexity) but pay daily theta. Short gamma positions collect theta income but face accelerating losses during large moves. Understanding which side of this tradeoff you’re on is fundamental to options strategy selection. For a practical application of managing this balance, see our delta hedging guide.
How to Calculate Theta Decay
You don’t need to compute the Black-Scholes formula by hand. Here’s a practical approach to tracking theta in your portfolio:
- Find theta on your broker’s options chain: Theta is displayed alongside delta, gamma, and vega for each strike and expiration.
- Convert to per-contract cost: Multiply theta by 100 (e.g., theta of −0.05 = −$5.00 per contract per day).
- Scale for your position: Multiply by the number of contracts and the position sign (+1 for long, −1 for short), then sum the signed daily exposures.
- Track theta over time: Theta changes with time and moneyness — re-check regularly, especially in the final 2–3 weeks.
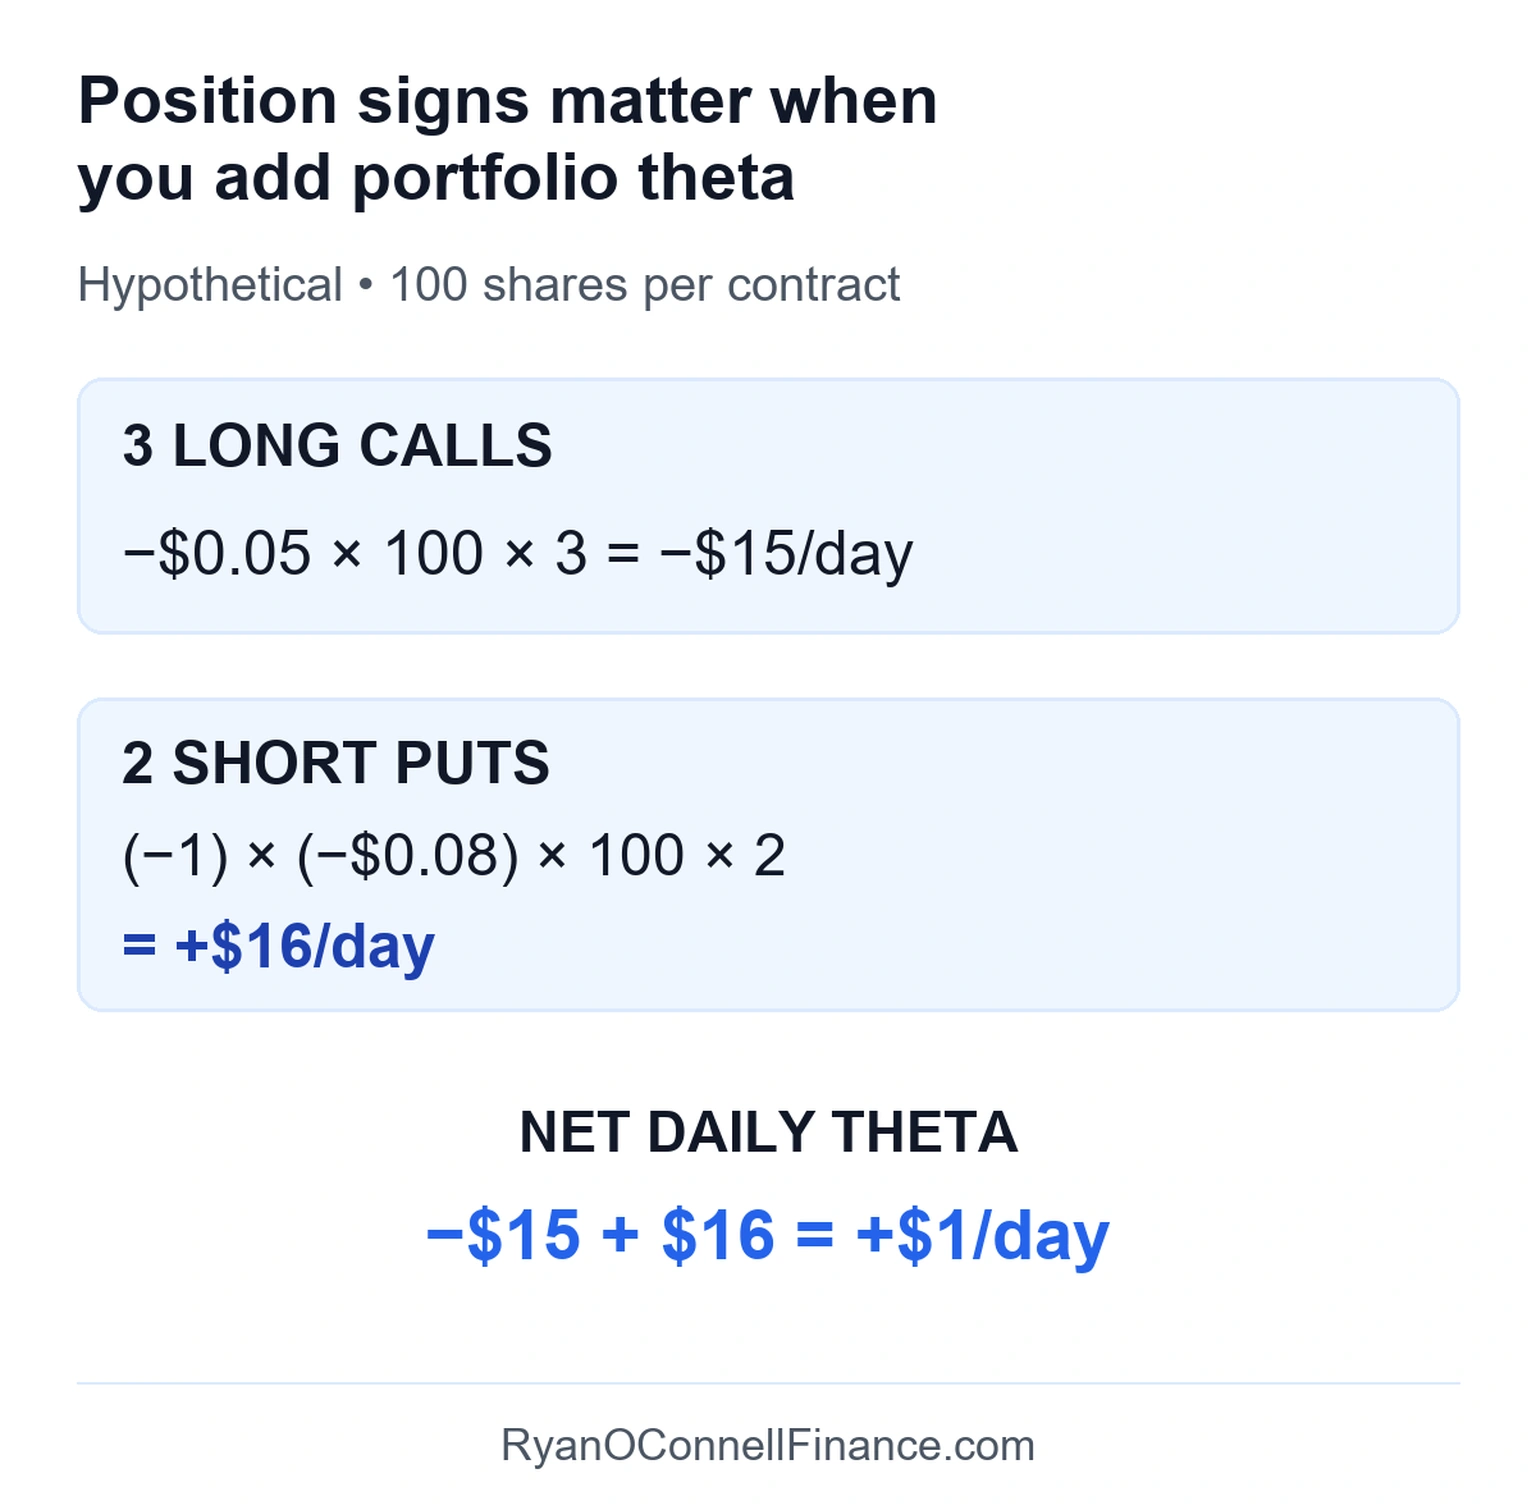
The short puts reverse the option’s quoted negative theta, so their +$16 daily exposure offsets the long calls’ −$15. The net +$1 per day isolates time decay; it is not a guaranteed daily profit.
Whether you’re running covered calls, debit spreads, or credit spreads, monitoring net theta tells you how much time is costing — or earning — each day across your entire portfolio.
Net portfolio theta is the sum of theta across all positions, accounting for long vs short direction. A portfolio with +$50 net daily theta is collecting $50/day from time decay; a portfolio with −$50 net daily theta is paying $50/day. Monitoring portfolio-level theta helps you understand whether time is working for or against your overall book. For a complete picture of how theta interacts with the other Greeks, explore our Options Greeks course.
Common Mistakes
These are the most frequent errors traders make when working with option theta:
1. Assuming theta decay is linear. Many traders multiply today’s theta by 30 to estimate a month of decay. This produces misleading results because theta changes with time and moneyness. An option with theta of −$0.05 today might have theta of −$0.12 a week later. For options that remain near the money with fixed inputs, decay is generally more back-loaded than a fixed-theta projection implies; away from the strike, theta can taper instead.
2. Buying cheap OTM options without accounting for theta drag. Low-premium out-of-the-money options look appealing because they are inexpensive, but theta as a percentage of the option’s value is often among the highest. A $0.50 OTM call with theta of −$0.04 loses 8% of its value every day. The stock needs to make a substantial move — and quickly — just to offset the time decay.
3. Ignoring the gamma-theta tradeoff when selling options. Option sellers focus on collecting theta income but underestimate the gamma risk that accompanies high-theta positions. The same ATM options near expiration that generate the richest daily theta also carry the highest gamma, meaning a sudden stock move can produce losses that far exceed weeks of accumulated theta gains.
4. Conflating theta with total expected loss. Theta measures only the time-decay component of daily P&L, holding stock price and IV constant. In practice, delta/gamma effects from stock movement and vega effects from IV changes often dominate any single day’s P&L. An option with −$0.05 theta can still gain $1.00 in a day if the stock moves favorably.
5. Overlooking weekend and holiday theta conventions. Whether options decay over weekends depends on the model convention and market repricing behavior. Some models spread theta evenly across all calendar days (including weekends), while others concentrate decay on trading days only. The convention your broker or model uses affects the daily theta figure. Be aware that Friday-to-Monday theta may behave differently than Tuesday-to-Wednesday theta depending on the pricing model and how the market reprices options at the open.
Limitations of Theta
Theta is a model-derived estimate that assumes all other factors remain constant. In real markets, stock prices, implied volatility, and interest rates change simultaneously, making theta just one piece of the daily P&L puzzle.
1. Ceteris paribus assumption. Theta isolates the effect of time passing while holding stock price and IV constant. On any given day, delta/gamma and vega effects usually generate larger P&L swings than theta alone. Theta is a persistent headwind or tailwind, but it is rarely the dominant factor on a single-day basis.
2. Calendar day vs trading day conventions. Some platforms quote theta per calendar day (dividing annualized theta by 365) while others use trading days (dividing by 252). This difference produces noticeably different daily theta values — the trading-day convention yields a figure roughly 45% higher. Always check which convention your broker uses to avoid misinterpreting your daily decay exposure.
3. Deep ITM European put exception. Under Black-Scholes, deep in-the-money European puts can theoretically have positive theta — they can gain time value as they approach expiration under certain conditions (high interest rates and extreme moneyness). Early exercise on American-style options usually reduces or eliminates this effect. For standard equity options trading, the exception is rare, but it is worth noting for completeness.
Theta is essential for understanding the cost of holding option positions over time, but it should always be analyzed alongside delta, gamma, and vega for a complete risk picture. No single Greek tells the whole story. For a comprehensive view of how all five Greeks interact, see our Options Greeks overview.
Frequently Asked Questions
Disclaimer
This article is for educational and informational purposes only and does not constitute investment advice. Options trading involves significant risk and is not suitable for all investors. Theta values cited are approximate and may differ based on the pricing model, inputs, and market conditions. Always conduct your own research and consult a qualified financial advisor before making trading decisions.
Keep reading
Next in this series
Part 5 of 11 in The Options Greeks
Option Vega: Volatility Sensitivity ExplainedMore in Options & Derivatives
-
Call Options: Buying and Selling Calls Explained
Complete guide to call options — how they work, buying vs selling calls, payoff diagrams, and when to use call options in your trading strategy.
-
Put Options: Buying and Selling Puts Explained
Complete guide to put options — how they work, buying vs selling puts, payoff diagrams, hedging applications, and when to use put options.
-
Option Greeks: The Complete Beginner’s Guide
Complete guide to the five option Greeks — delta, gamma, theta, vega, and rho — what they measure, how they interact, and how to use them for options analysis.