Option Rho: The Interest Rate Greek
Table of Contents
Option rho is the fifth and often overlooked member of the option Greeks family. While delta, gamma, theta, and vega capture the effects of price movement, curvature, time decay, and volatility, rho answers a different question: how does an option’s price respond when interest rates change? For most short-dated options, rho is the smallest Greek in practical impact — but for LEAPS and large portfolios, ignoring it can be costly. Rho is one of the five core Greeks covered in our Options Greeks course.
What is Option Rho?
Option rho (ρ) measures the change in an option’s price for a 1-percentage-point change in the risk-free interest rate, holding all other factors constant. It is a first-order Greek — the partial derivative of the option’s value with respect to the interest rate (∂V/∂r).
Rho tells you how much an option’s price will change when the risk-free interest rate moves by 1 percentage point (e.g., from 4.5% to 5.5%). Long calls have positive rho — they gain value when rates rise. Long puts have negative rho — they lose value when rates rise. Selling reverses the sign: short calls carry negative rho, and short puts carry positive rho.
Why does this happen? Higher interest rates increase the forward price of the underlying stock (the cost of carrying a stock position rises). This benefits call holders (the right to buy at a fixed strike becomes more valuable) and hurts put holders (the right to sell at a fixed strike becomes less valuable, because the present value of the strike they receive decreases).
Unit convention: Rho is quoted per share. A rho of 0.95 means the option price changes by approximately $0.95 per share for a 1pp rate move. Since each standard contract covers 100 shares, the per-contract impact is 0.95 × 100 = $95.
Option Rho Formula
Under the Black-Scholes model for European-style options (ceteris paribus — holding stock price, volatility, and time constant), rho is calculated as:
Where:
- K — option strike price
- T — time to expiration in years (e.g., 365 days = 1.0, 30 days = 30/365)
- r — risk-free interest rate, typically a maturity-matched Treasury or OIS yield (not the fed funds headline rate)
- e−rT — continuous-time discount factor
- N(d2) — cumulative standard normal distribution evaluated at d2
- d2 = d1 − σ × √T, where d1 = [ln(S/K) + (r + σ²/2) × T] / (σ × √T). For dividend-paying stocks, replace r with r − q in d1, where q is the continuous dividend yield.
Scaling convention: The formulas above produce rho per a full 1.0 (100 percentage point) rate change. To express rho per 1 percentage point (the standard broker convention), divide by 100. Most broker platforms already display rho in the per-1pp format, so a displayed rho of 0.95 means $0.95 per share per 1pp rate move.
Interpreting Rho Values
Rho varies significantly based on an option’s time to expiration and moneyness. The table below gives illustrative per-1pp rho values for options on a $195 stock; these are not a current options-chain snapshot:
| Scenario | Illustrative Rho ($/share per 1pp) | Why |
|---|---|---|
| ATM call, 30 DTE | +0.08 | Short time horizon limits interest rate sensitivity |
| ATM call, 1-year LEAPS | +0.90 to +1.10 | Long duration amplifies the rate effect via the T factor |
| ATM put, 1-year | −0.90 to −1.10 | Typically similar magnitude as call rho, but opposite sign |
| Deep ITM call, 1-year | Highest positive | Acts like a leveraged stock position; discounted strike amplifies rate sensitivity |
| Deep OTM call | Very small | Low probability of finishing ITM means little sensitivity to rate changes |
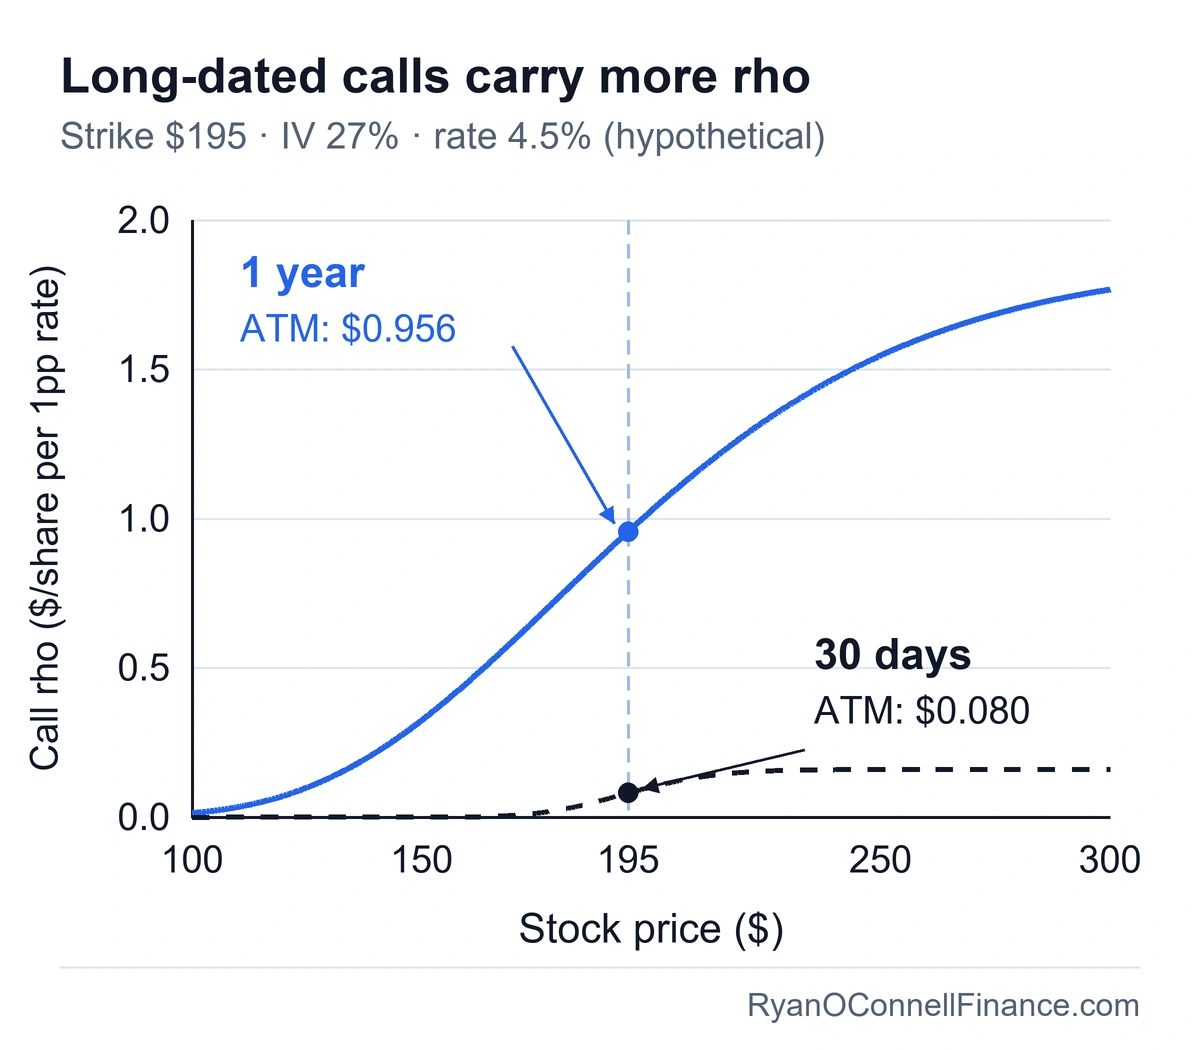
At the $195 stock price, the modeled 1-year call has about 12 times the rho of the 30-day call. Holding the strike fixed, moving deeper into the money increases call rho because N(d2) rises.
For the illustrative ATM 30-day call above, a 1pp rate move changes the option price by roughly $0.08 per share — far less than the typical daily effects of delta, theta, or vega in dollar terms. This is why most traders focus on the other four Greeks first. Longer-dated options amplify the per-contract rate effect; short-dated rho can still matter when many contracts are held.
Rho Example
Let’s see how rho affects a LEAPS option compared to a short-dated option, using the same underlying stock.
Setup: AAPL is trading at $195. Compare two ATM call options at the $195 strike:
- 1-year LEAPS call: rho = 0.95
- 30-day call: rho = 0.08
Scenario: Risk-free rate rises from 4.5% to 5.5% (+1pp)
| Call expiry | Estimated gain ($/contract) |
|---|---|
| 1 year | 95 |
| 30 days | 8 |
Hypothetical AAPL example; +1pp in the maturity-matched rate, starting rhos fixed and other inputs unchanged.
The same 1pp rate rise produces an estimated gain of $95 per standard contract for the LEAPS call versus $8 for the 30-day call, using the displayed per-share rhos and the 100-share multiplier.
Key insight: The LEAPS option has roughly 12× the rho of the 30-day option, primarily because the T factor in the rho formula is about 12× larger (the discount factor and N(d2) also contribute to the difference). For a 10-contract LEAPS position, a 1pp rate increase adds approximately $950 to the position value.
Note: Rho is a first-order linear estimate. The actual price change may differ slightly because rho itself changes as rates move.
When Does Rho Matter?
For most standard monthly options, rho is the least significant Greek. However, there are three scenarios where rho becomes meaningful:
- LEAPS and long-dated options (6+ months): The T factor in the rho formula amplifies interest rate sensitivity. A 1-year ATM call can have rho above 0.90, making a 1pp rate change worth nearly $1 per share.
- Rapidly changing rate environments: During Fed tightening or easing cycles, multiple rate changes can occur over a LEAPS option’s life. Two or three 25bp moves in the option’s maturity-matched market rate can accumulate into a meaningful rho-driven P&L shift; Fed policy changes do not necessarily pass through one-for-one.
- Large institutional portfolios: A rho of 0.08 per share is trivial for 1 contract, but across 1,000 contracts the exposure becomes $8,000 per 1pp rate move — worth monitoring and potentially hedging.
For standard monthly options (30–45 DTE), rho is usually negligible compared to delta, theta, gamma, and vega. For ordinary small positions, the other four Greeks often deserve more attention. Monitor rho for longer expiries, large short-dated positions, rapid market-rate changes or exposure to unequal moves across maturities.
Rho vs Other Greeks
Rho’s relative importance depends on your option’s time horizon and the rate environment. Here’s when rho matters and when you can set it aside:
When Rho Matters Most
- LEAPS and options with 6+ months to expiration
- Active Fed tightening or easing cycles
- Large multi-contract portfolios
- Deep ITM calls with long duration
- Strategies sensitive to carry cost (e.g., synthetic long stock)
Among the five core Greeks, rho typically has the smallest practical P&L impact for standard retail option tenors. This doesn’t make it unimportant — it simply means its relevance is concentrated in specific situations.
How to Analyze Option Rho Exposure
When rho does matter for your portfolio, use this practical framework to assess and manage your exposure:
- Check rho on your broker’s options chain: Rho is displayed alongside delta, gamma, theta, and vega. Note the sign and magnitude for each position.
- Calculate position rho: Position Rho = option rho × contracts × 100 × position sign (+1 for long, −1 for short). Sum across all positions for net portfolio rho.
- Assess the rate environment: Check the Fed meeting schedule, Treasury yield trends, and your options’ time to expiration. If you hold LEAPS through a period of expected rate changes, your rho exposure may be significant.
If your portfolio includes significant LEAPS exposure, check your net portfolio rho before major Fed announcements. For a parallel increase in maturity-matched market rates, positive net rho estimates a gain and negative net rho estimates a loss, with other inputs fixed. A Fed hike alone does not establish that move; unequal changes across maturities can produce a different result. For a complete Greek-level risk assessment across all five sensitivities, see our Options Greeks course.
Common Mistakes
These are the most frequent errors traders make when working with option rho:
1. Ignoring rho entirely for LEAPS positions. A 1-year ATM call with rho of ~1.0 per share on a 10-contract position carries $1,000 of rho exposure per 1pp rate move. Over a year-long holding period, changes in the maturity-matched market rate can make this exposure consequential for P&L. Always check rho for options with 6+ months to expiration.
2. Confusing the risk-free rate with other interest rates. Rho uses the risk-free rate — typically a maturity-matched Treasury yield or OIS rate. It does not respond to changes in mortgage rates, corporate bond yields, or the fed funds headline rate directly. The relevant input is the market-implied yield for the option’s specific time horizon.
3. Overweighting rho for short-dated options. For ordinary small weekly or monthly positions, rho often contributes less than delta or theta. The illustrative 30-day ATM call above has rho of $0.08 per share per 1pp rate move; large contract counts or unequal maturity-rate moves can still make that exposure consequential. Compare position-level scenario impacts rather than dismissing short-dated rho.
4. Forgetting per-contract scaling. A displayed rho of 0.95 on 5 long contracts means your position rho is 0.95 × 5 × 100 = $475 per 1pp rate move, not $0.95. Always multiply by contract count and the 100-share multiplier to understand your true exposure.
Limitations of Rho
A single option’s rho refers to its own rate input; a summed portfolio rho commonly assumes a parallel shift across maturity-matched rates. In reality, yield curve changes are rarely uniform — short-term and long-term rates often move by different amounts or even in opposite directions.
1. Smallest practical P&L driver for standard tenors. For options under 90 DTE, rho is almost always overshadowed by delta, theta, gamma, and vega. It becomes a meaningful factor only for LEAPS, large portfolios, or rapid rate-change environments.
2. Parallel rate-shift assumption. Summed portfolio rho estimates the effect of a uniform change in the legs’ maturity-matched rates. Real yield curve movements are more complex — the front end might move 50bp while the long end moves only 10bp. Portfolio-level rho is a useful approximation but may not capture the full impact of non-parallel shifts.
Using the example rhos, consider one long 1-year call (+$95 per 1pp) and ten short 30-day calls (-$80 per 1pp in total). Net rho is +$15 per 1pp. Here 50 basis points means 0.50 percentage points, and 10bp means 0.10pp:
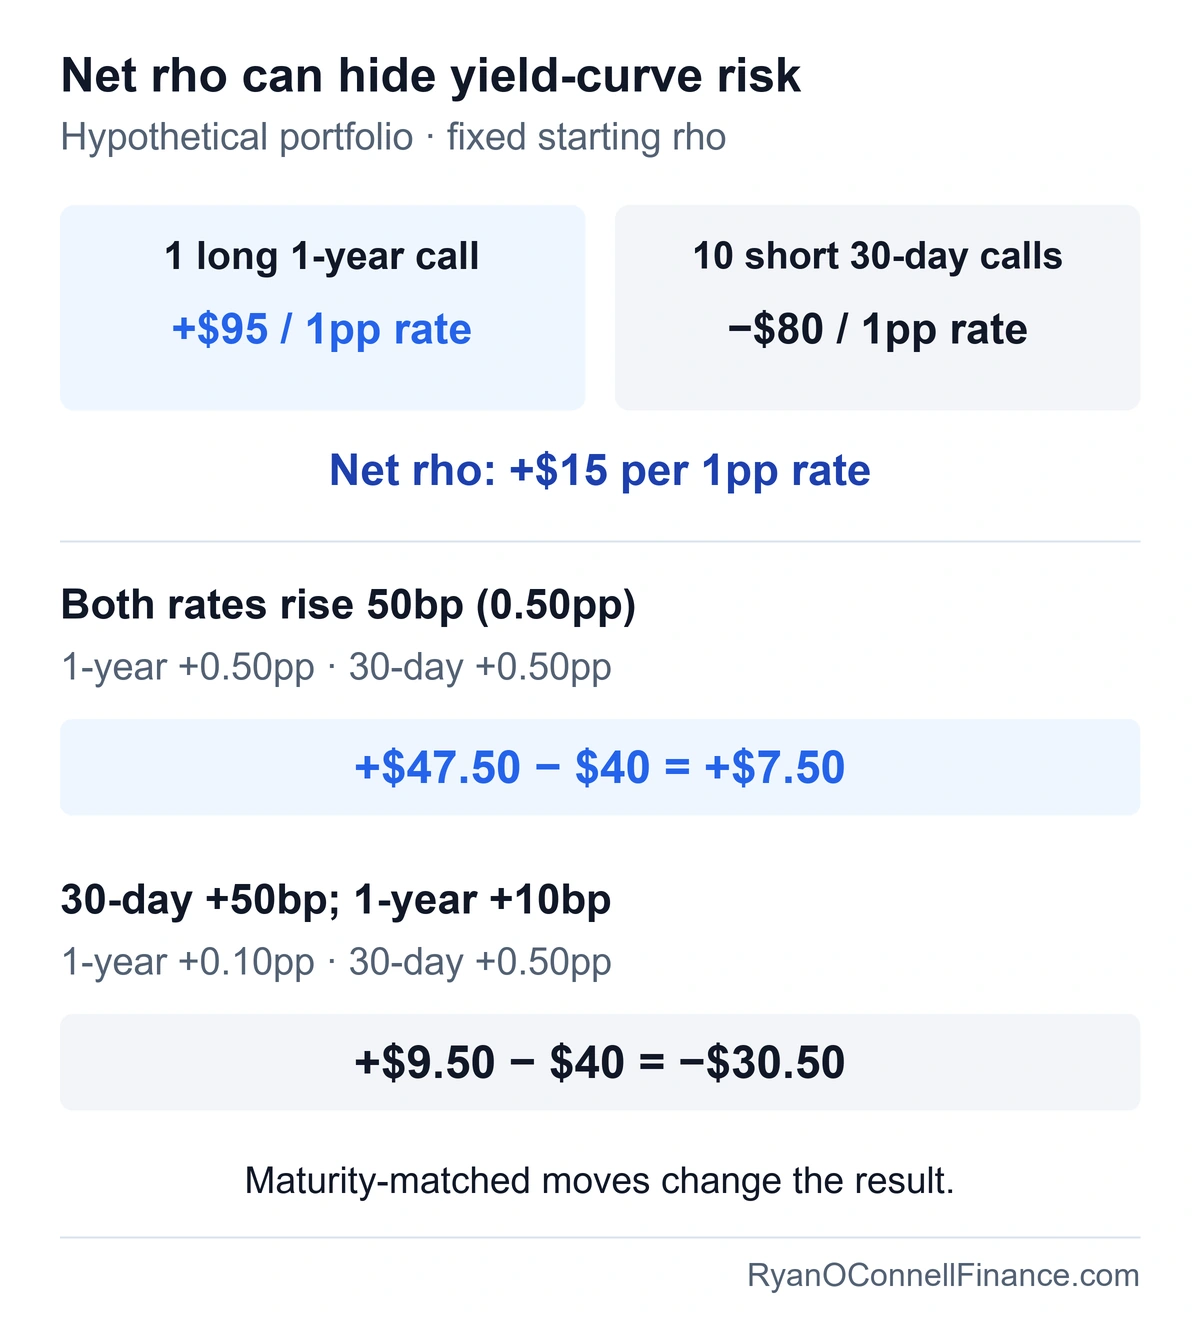
A parallel 50bp rise adds about $7.50. If the 30-day rate rises 50bp but the 1-year rate rises only 10bp, the estimated rate contribution becomes -$30.50. Apply each leg’s own maturity-matched rate move rather than multiplying net rho by a single Fed headline change.
3. Model-dependent. The Black-Scholes rho formula assumes a constant risk-free rate. More advanced models (such as stochastic interest rate models) treat rates as a random variable, which can produce different rho estimates. In practice, market-implied Treasury and OIS yields move continuously with economic data and expectations — not only at scheduled Fed meetings.
Rho completes the picture of option sensitivities but is the least actionable Greek for most traders. Prioritize delta, theta, gamma, and vega for daily risk management, and monitor rho when you hold LEAPS or trade through active rate-change cycles.
Frequently Asked Questions
Disclaimer
This article is for educational and informational purposes only and does not constitute investment advice. Options trading involves significant risk and is not suitable for all investors. Rho values cited are approximate and may differ based on the pricing model, inputs, and market conditions. Always conduct your own research and consult a qualified financial advisor before making trading decisions.
Keep reading
Next in this series
Part 7 of 11 in The Options Greeks
Delta Hedging: Strategy, Mechanics & ExamplesMore in Options & Derivatives
-
Call Options: Buying and Selling Calls Explained
Complete guide to call options — how they work, buying vs selling calls, payoff diagrams, and when to use call options in your trading strategy.
-
Put Options: Buying and Selling Puts Explained
Complete guide to put options — how they work, buying vs selling puts, payoff diagrams, hedging applications, and when to use put options.
-
Option Greeks: The Complete Beginner’s Guide
Complete guide to the five option Greeks — delta, gamma, theta, vega, and rho — what they measure, how they interact, and how to use them for options analysis.