Barrier Options: Types, Pricing, and In-Out Parity Explained
Table of Contents
Barrier options are among the most widely traded exotic options in institutional finance. Unlike standard calls and puts, barrier options activate or deactivate when the underlying asset reaches a specific price level — the barrier. This conditional feature makes them cheaper than equivalent vanilla options, which is why corporate treasurers and investment banks use them extensively to reduce hedging costs. Along with Asian options, barrier options represent one of the most practical and commonly encountered exotic option types.
What Are Barrier Options?
A barrier option is an option contract that includes a predetermined price level — the barrier — which determines whether the option becomes active or ceases to exist. The barrier creates a conditional element that does not exist in vanilla options.
Barrier options come in two fundamental categories: knock-in options that only become active when the underlying asset reaches the barrier, and knock-out options that terminate (become worthless) if the underlying reaches the barrier. Combined with the barrier direction (up or down), this creates four basic barrier types.
The four basic types arise from two choices:
- Barrier effect: Knock-in (activates at barrier) or knock-out (terminates at barrier)
- Barrier direction: Up (barrier is above current price) or down (barrier is below current price)
Barrier options are among the most commonly traded exotic options at major investment banks. They appear frequently in structured products, corporate hedging programs, and FX markets. Variations include double-barrier options (with both an upper and lower barrier) and one-touch/no-touch options (which pay a fixed amount if the barrier is or isn’t reached), though this article focuses on the standard single-barrier types.
Types of Barrier Options
Each of the four barrier types can be applied to either a call or a put, creating eight standard combinations:
| Type | Direction | Effect | Description |
|---|---|---|---|
| Up-and-In Call | Up | Knock-In | Call activates when price rises to barrier |
| Up-and-In Put | Up | Knock-In | Put activates when price rises to barrier |
| Up-and-Out Call | Up | Knock-Out | Call terminates when price rises to barrier |
| Up-and-Out Put | Up | Knock-Out | Put terminates when price rises to barrier |
| Down-and-In Call | Down | Knock-In | Call activates when price falls to barrier |
| Down-and-In Put | Down | Knock-In | Put activates when price falls to barrier |
| Down-and-Out Call | Down | Knock-Out | Call terminates when price falls to barrier |
| Down-and-Out Put | Down | Knock-Out | Put terminates when price falls to barrier |
Some barrier options include a rebate — a fixed cash payment made to the holder when a knock-out option is terminated (barrier is breached) or when a knock-in option’s barrier is never reached during the option’s life. The rebate provides partial compensation for losing or never gaining the option.
Continuous vs Discrete Monitoring
The monitoring convention determines when the barrier can be triggered:
- Continuous monitoring: Any price tick during the option’s life can trigger the barrier. Standard in FX markets where prices are observed continuously.
- Discrete monitoring: The barrier is checked only at specific times (e.g., daily closing prices, weekly fixings). Common in equity and commodity markets.
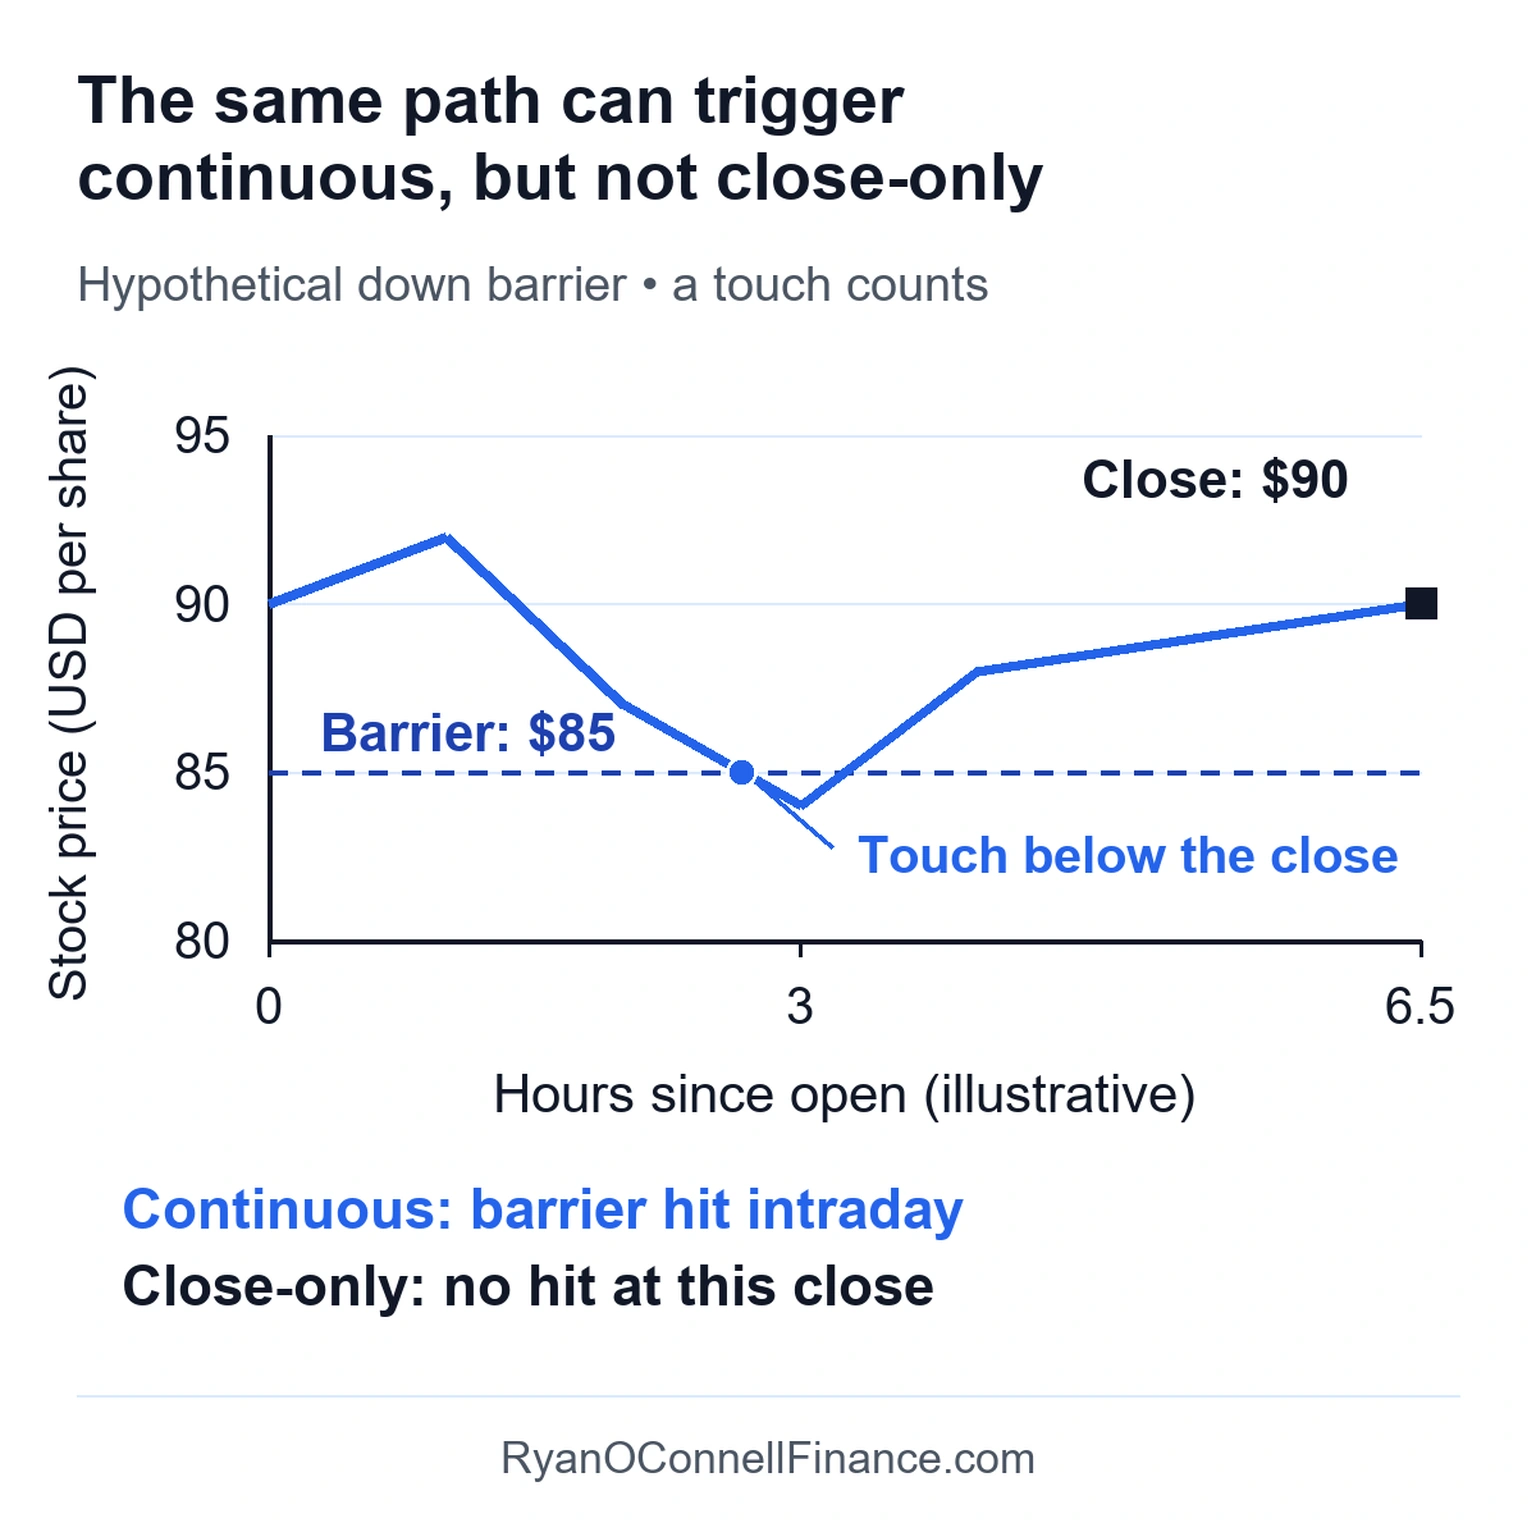
The price touches $85 during the day, so the continuously monitored knock-out triggers even though the stock closes at $90. The close-only contract has no trigger at that observation; it must still be monitored on later scheduled dates.
Discrete monitoring reduces the probability of barrier breach, but the effect on pricing depends on the option type. Discrete knock-out options are typically more expensive than their continuous counterparts — the holder is less likely to lose the option. Discrete knock-in options are typically cheaper — the holder is less likely to gain the option. Contract terms also specify whether the barrier is triggered on a “touch” (any trade at the barrier level) or only at the official close, and whether a price exactly equal to the barrier counts as a breach.
How Barrier Options Are Priced
Barrier options are generally cheaper than equivalent vanilla options for otherwise comparable contracts with no or limited rebate. The buyer accepts a conditional payoff — the option may be knocked out or may never knock in — and pays a lower premium in exchange for this risk.
The intuition behind in-out parity is straightforward: either the barrier is reached during the option’s life (the knock-in activates and the knock-out is terminated) or the barrier is never reached (the knock-out survives and the knock-in expires inactive). The active leg delivers the vanilla payoff, which can itself be zero. For the unadjusted equation above, use zero rebates and matched strike, barrier, maturity, monitoring convention and underlying dynamics, with no counterparty default. If rebates are present, their cash flows must be explicitly accounted for. The same zero-rebate parity applies to puts: Pknock-in + Pknock-out = Pvanilla.
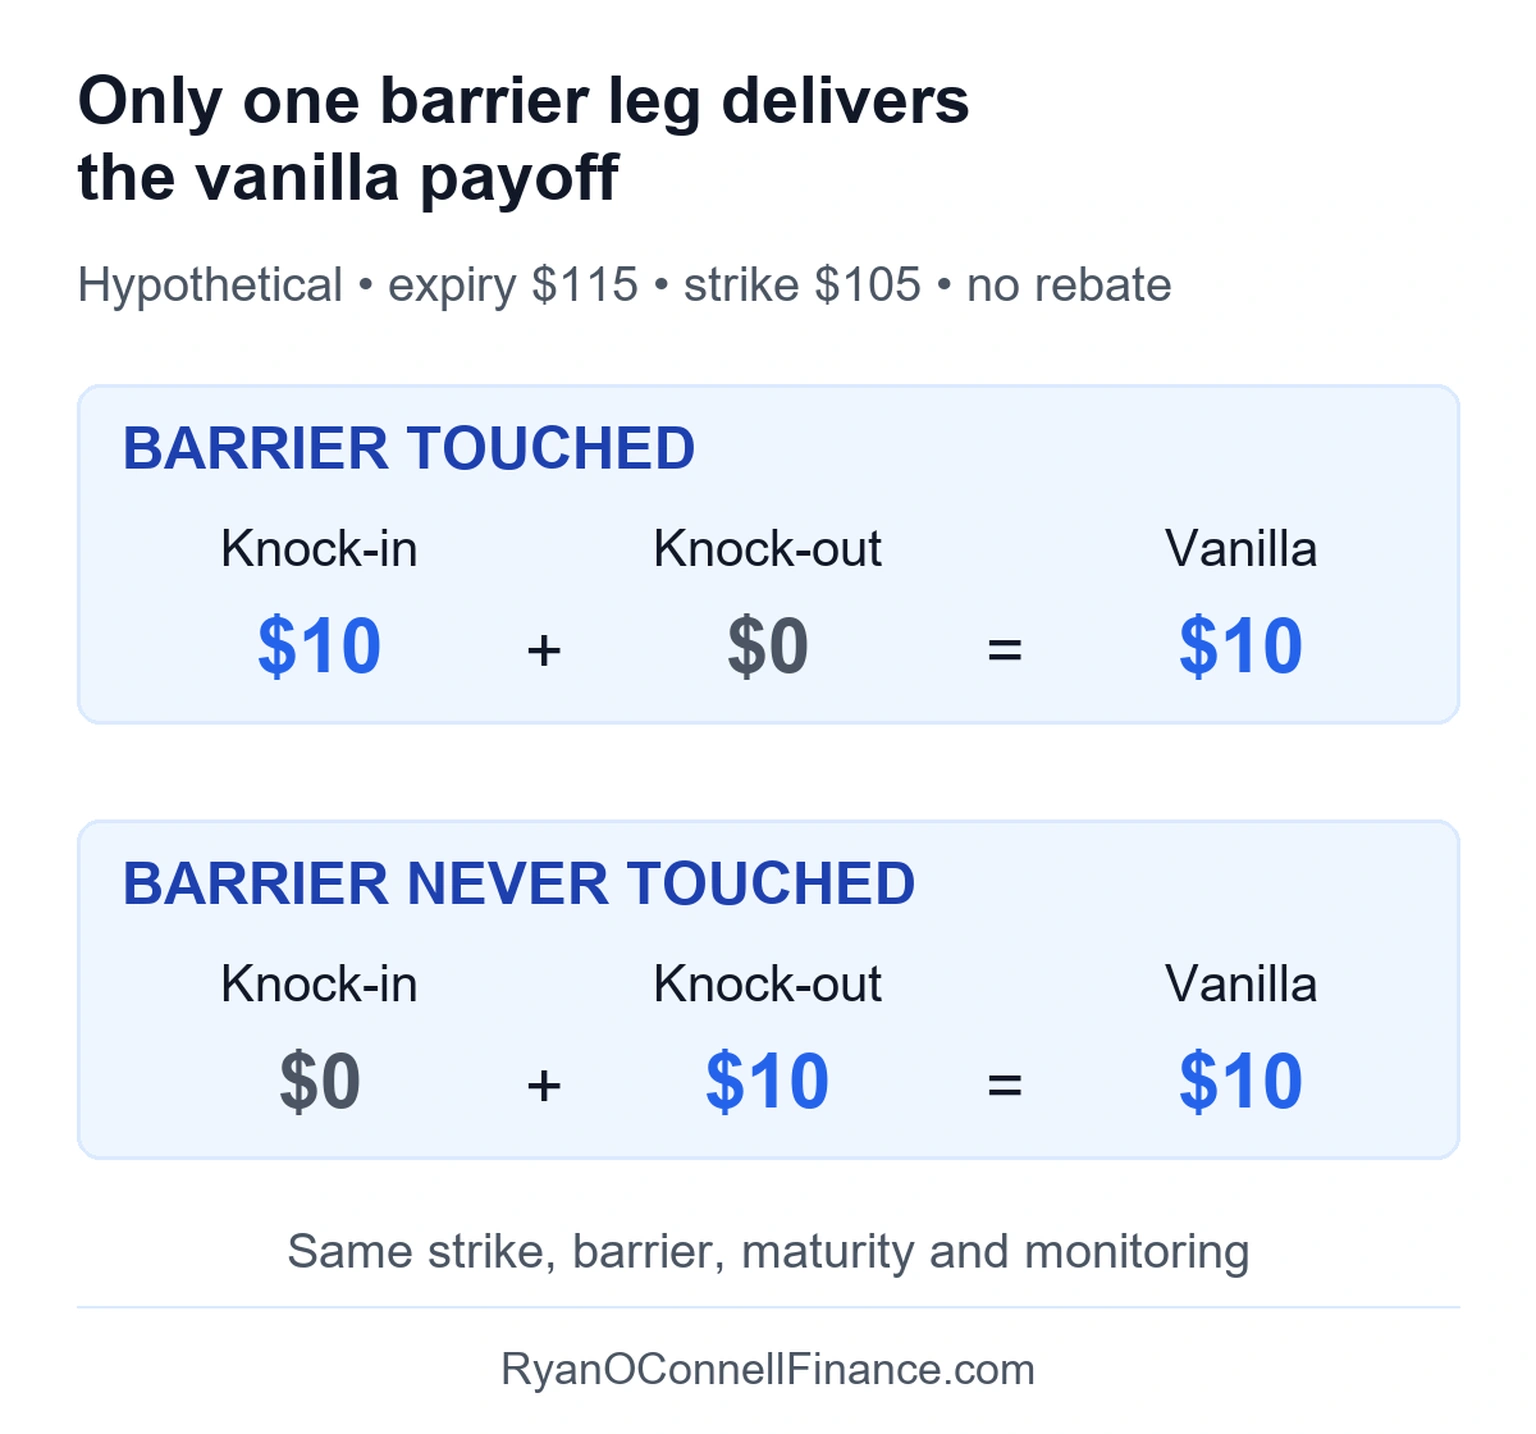
At a $115 expiry price and $105 strike, the vanilla call pays $10. The barrier history changes which leg delivers that $10, while their combined payoff stays the same.
The key drivers of barrier option pricing include:
- Distance to barrier — the closer the current price to the barrier, the higher the probability of breach
- Implied volatility and skew — higher volatility increases breach probability; the volatility smile has an outsized effect on barrier pricing compared to vanilla options
- Time to expiry — longer duration means more opportunities for the barrier to be hit
- Interest rates and dividends — affect the drift of the underlying price path
- Monitoring frequency — continuous vs discrete changes the effective barrier level
Analytical pricing formulas exist for continuously-monitored barrier options, derived as extensions of the Black-Scholes model. Discrete barrier options typically require numerical methods or approximation adjustments.
In-out parity provides a practical pricing shortcut. If you can price a knock-out option, you can derive the knock-in price as the difference between the vanilla price and the knock-out price — no separate knock-in model needed.
Barrier Option Example
In a hypothetical example, NVIDIA (NVDA) is trading at $100. An investor wants to buy a call option with a $105 strike expiring in 6 months. They can choose between a vanilla call and a down-and-out call with a barrier at $85.
Illustrative premiums assuming 32% implied volatility, 5% risk-free rate, continuous monitoring, no rebate:
| Option | Premium | Condition |
|---|---|---|
| Vanilla $105 Call | ~$8.00 | No conditions |
| Down-and-Out $105 Call (barrier $85) | ~$5.50 | Knocked out if stock hits $85 |
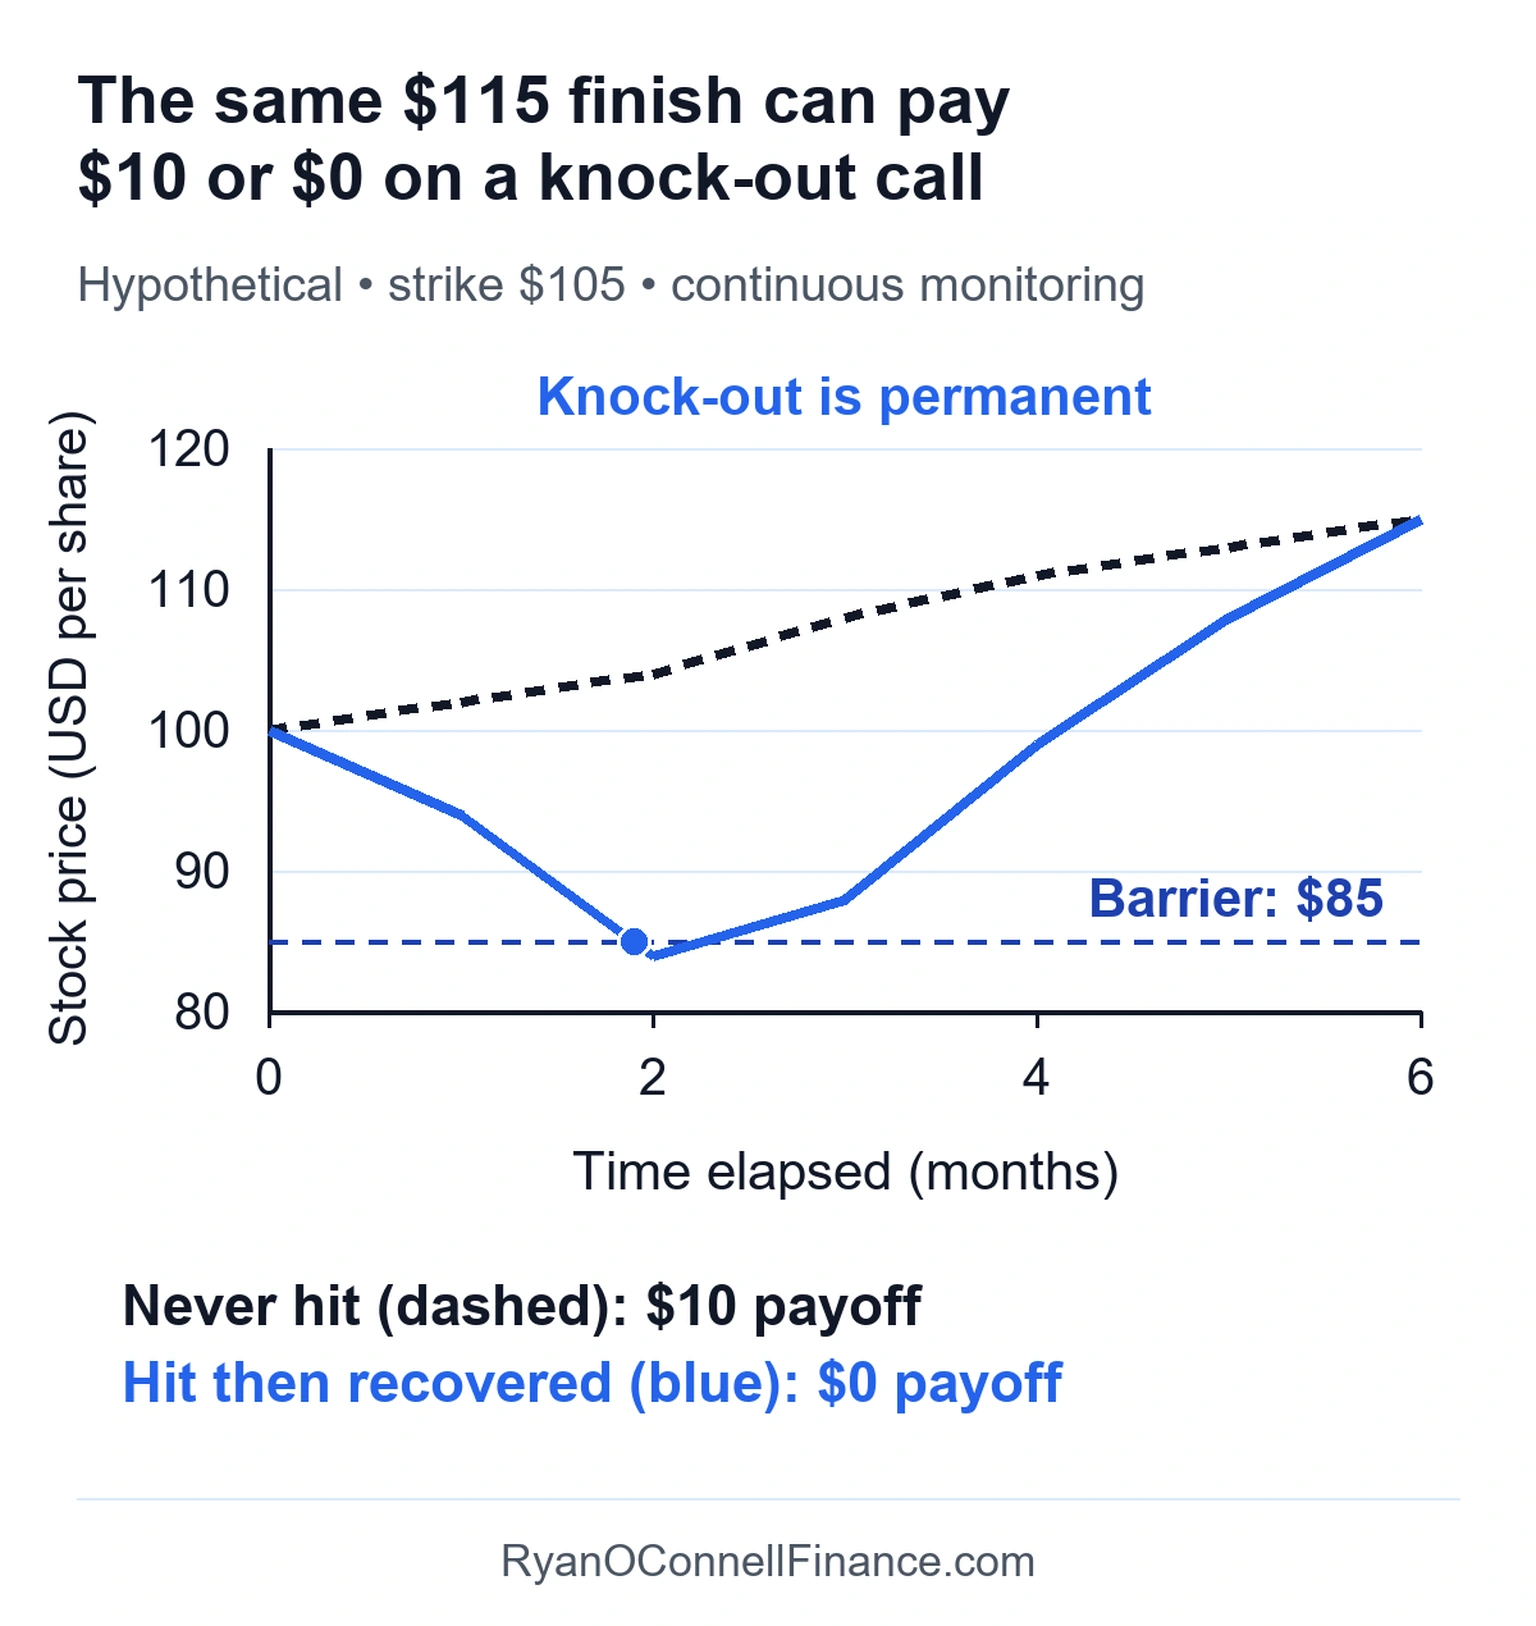
Scenario 1: If the stock never touches $85, both calls pay $10 at expiry ($115 − $105). The down-and-out buyer paid $2.50 less in illustrative premium.
Scenario 2: If the stock falls to $84 in month 2 and then recovers to the same $115 finish, the earlier $85 touch has permanently terminated the down-and-out call. It pays $0, while the vanilla call still pays $10. These are expiry payoffs, not profits after premiums.
In a second hypothetical example, a corporate treasurer at a mid-cap industrial firm holds Caterpillar (CAT) shares trading at $50 and wants downside protection. A vanilla put with a $48 strike costs $3.20. A down-and-in put with the same strike and a $40 barrier costs only $1.80.
The treasurer saves $1.40 per share (about 44%) in illustrative premium. The put activates only after a $40 touch; if that never occurs, a moderate decline below the $48 strike remains unprotected by this option.
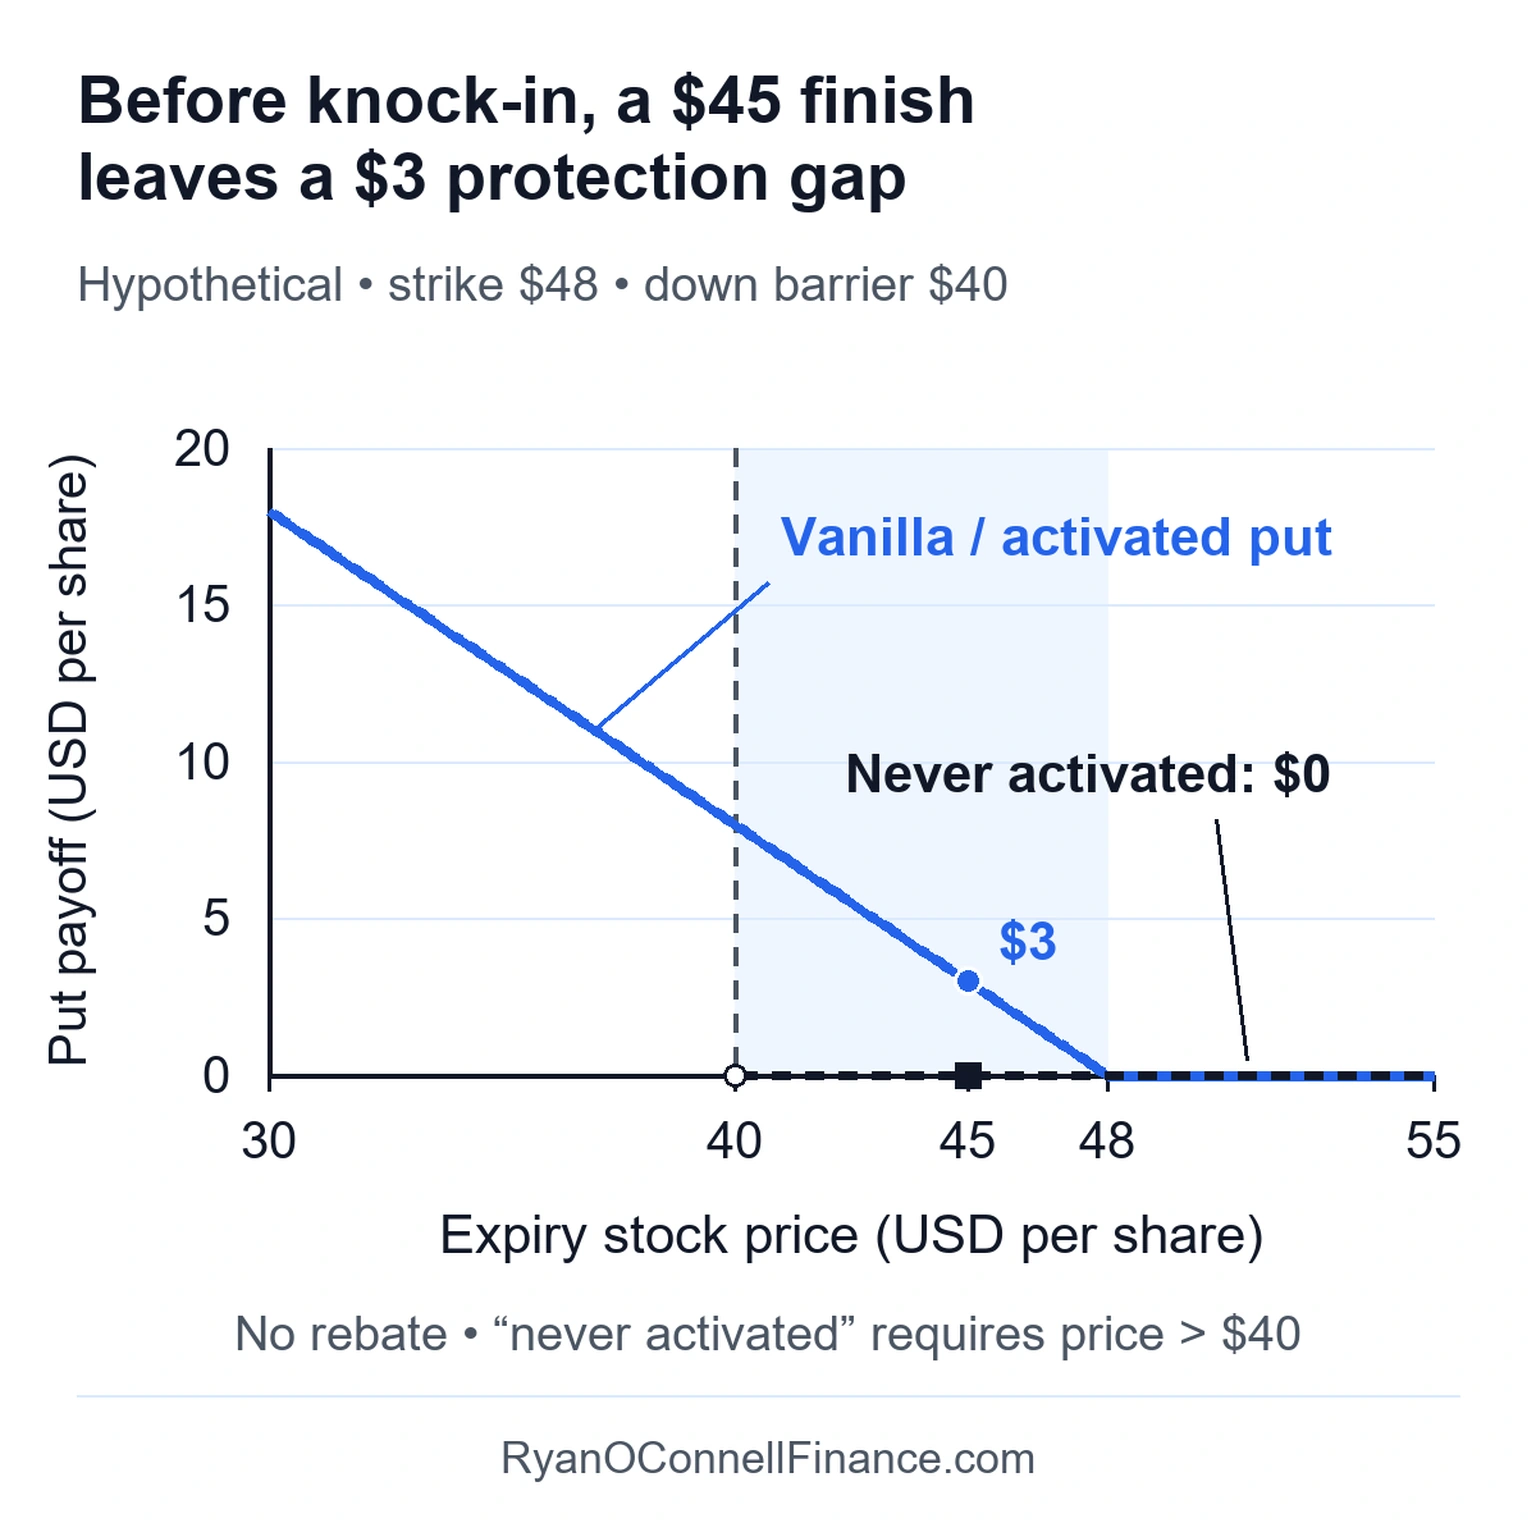
If the stock finishes at $45 without ever touching $40, the vanilla put pays $3 while the down-and-in put pays $0. If the stock touched $40 earlier and then recovered to $45, the knock-in stays activated and also pays $3. The protection gap depends on barrier history, not just the final price.
Barrier Options vs Vanilla Options
Barrier Options
- Lower premium for comparable contracts
- Payoff is conditional on barrier
- Complex Greeks with discontinuities near barrier
- Primarily OTC, some standardized forms exist
- Used as a hedging cost reduction tool
Vanilla Options
- Higher premium for full optionality
- Payoff is unconditional
- Smooth, well-behaved Greeks
- Exchange-traded and liquid
- Straightforward hedging and risk management
Barrier Option Greeks
The Greeks of barrier options behave very differently from vanilla options, especially as the underlying price approaches the barrier level.
Delta becomes discontinuous near the barrier. For a knock-out option, delta can swing dramatically — the option’s sensitivity to price changes jumps as the underlying approaches the barrier because a small price move can mean the difference between the option surviving and being terminated.
Gamma spikes near the barrier, reflecting the extreme sensitivity of delta in that region. For market makers hedging barrier option positions, this gamma spike creates significant and costly hedging adjustments.
Pin risk occurs when the underlying price hovers near the barrier level. Before a knock-out occurs, small price changes near the barrier can sharply change the risk of losing the option, making the position difficult to hedge. Once the contractual trigger occurs, the knock-out is permanent; a later recovery does not switch the option back on. This is far more pronounced for barrier options than the pin risk vanilla options experience near the strike price at expiration.
Vega (volatility sensitivity) is more complex for barrier options. Higher implied volatility simultaneously increases the probability of barrier breach and the value of the embedded option — these effects can partially offset each other, making vega less predictable than for vanilla options.
The Greek discontinuities near the barrier make dynamic delta-hedging extremely challenging and expensive. This is a key reason barrier options trade OTC with wider bid-ask spreads than vanilla options — dealers must charge for the hedging difficulty.
Common Mistakes
1. Ignoring continuous vs discrete monitoring. Assuming discrete monitoring when the contract specifies continuous (or vice versa) leads to materially wrong pricing and risk assessment. Continuous monitoring means any intraday tick can trigger the barrier; discrete monitoring only checks at specified times. The pricing and risk implications differ significantly.
2. Underestimating barrier breach probability. The probability of the underlying touching a barrier level at any point during the option’s life is much higher than the probability of being below that level at expiration. Many practitioners underestimate how often price paths hit a barrier, especially over longer time horizons with higher volatility.
3. Misapplying in-out parity. In-out parity requires identical strike, barrier, maturity, and monitoring convention between the knock-in and knock-out options. Practitioners sometimes treat knock-in and knock-out prices as independent, or forget that the unadjusted parity requires zero rebates and no counterparty default; any rebate cash flows must be explicitly accounted for.
4. Ignoring contract terms. Barrier option contracts contain critical details that affect pricing and risk: rebate rules, monitoring convention (continuous vs discrete), trigger definition (touch vs close-only), and whether a price exactly at the barrier level counts as a breach. Overlooking any of these terms can lead to unexpected outcomes.
Limitations
Barrier options carry risks beyond those of vanilla options. Understanding these limitations is essential before using barrier options for hedging or investment.
Gap risk. The underlying price can jump through the barrier level — especially overnight, over weekends, or around major economic announcements. A stock trading at $86 can open at $83, gapping through an $85 barrier without ever trading at $85. The monitoring and trigger terms determine the result. Under a continuously monitored at-or-below rule, the $83 observation triggers the barrier even without a trade at exactly $85; close-only or other contractual definitions can differ.
Model-dependent pricing. Barrier option prices are far more sensitive to model assumptions than vanilla options. The volatility smile and skew have an outsized effect on barrier pricing — two models that agree on vanilla option prices can produce meaningfully different barrier option prices.
Hedging difficulties near the barrier. The Greek discontinuities described above make dynamic hedging unreliable when the underlying is close to the barrier. Dealers must widen bid-ask spreads to compensate for this hedging cost.
Counterparty risk. Most barrier options trade OTC, so the credit quality of the counterparty matters. Unlike exchange-traded options backed by a clearinghouse, OTC barrier options expose both parties to default risk.
Frequently Asked Questions
Disclaimer
This article is for educational and informational purposes only and does not constitute investment advice. Option premiums cited are illustrative and based on simplified assumptions. Actual barrier option pricing depends on market conditions, model choice, and contract-specific terms. Always consult a qualified financial professional before trading exotic options.
Keep reading
Next in this series
Part 3 of 6 in Exotic Options
Asian Options: Average Price and Average Strike Options ExplainedMore in Options & Derivatives
-
Call Options: Buying and Selling Calls Explained
Complete guide to call options — how they work, buying vs selling calls, payoff diagrams, and when to use call options in your trading strategy.
-
Put Options: Buying and Selling Puts Explained
Complete guide to put options — how they work, buying vs selling puts, payoff diagrams, hedging applications, and when to use put options.
-
Option Greeks: The Complete Beginner’s Guide
Complete guide to the five option Greeks — delta, gamma, theta, vega, and rho — what they measure, how they interact, and how to use them for options analysis.