
Bear Call Spread: Strategy & Payoff Diagram

Table of Contents
The bear call spread — also called a call credit spread — is a vertical options strategy that profits when the underlying stock stays flat or declines. By selling a lower-strike call option and buying a higher-strike call with the same expiration, you collect a net credit upfront and define your maximum risk. This guide covers the strategy mechanics, payoff formulas, a worked example, and when to use a bear call spread in your trading.
What is a Bear Call Spread?
A bear call spread is a two-leg options strategy designed for a bearish or neutral market outlook. You simultaneously sell a call at a lower strike price and buy a call at a higher strike price, both on the same underlying and with the same expiration date. The premium received from the short call exceeds the premium paid for the long call, resulting in a net credit to your account.
The bear call spread is a defined-risk credit spread. The long call caps your maximum loss at the width of the spread minus the credit received — eliminating the unlimited risk of a naked short call. Your maximum profit is the net credit collected, earned when both calls expire worthless.
The spread has net negative delta, so a small stock-price decline generally helps with other inputs fixed. Net theta and vega are the differences between the two legs’ sensitivities. Theta is often positive and vega negative when both call strikes are above spot, but those signs can change as the stock moves through the strikes. Receiving a credit does not determine either sign.
How a Bear Call Spread Works
Setting up a bear call spread involves four steps:
- Sell one call at a lower strike price — this is the short leg that generates premium. Choose a strike above the current stock price (out-of-the-money) to increase the probability that it expires worthless.
- Buy one call at a higher strike price — this is the long leg that limits your maximum loss. Without it, you would have a naked short call with theoretically unlimited risk.
- Both options share the same expiration date — this creates a vertical spread. The spread width (difference between strikes) determines your maximum risk.
- Collect the net credit — the premium received from the short call minus the premium paid for the long call. This credit is your maximum profit.
Choosing Strikes and Expiration
Strike selection and expiration date are critical to a bear call spread’s success:
- Short call strike — many traders sell a call with a delta between 0.20 and 0.35 (a “20 to 35 delta call”). The resulting position delta is negative, reflecting the bearish bias. A lower delta means the strike is further out of the money, giving the trade a higher probability of profit but a smaller credit.
- Spread width — wider spreads collect more credit but increase maximum loss proportionally. Common widths range from $5 to $10 for most equity options. Ensure the credit received justifies the risk and covers transaction costs.
- Expiration (DTE) — 30 to 45 days to expiration captures accelerating theta decay while providing enough premium to make the trade worthwhile. Shorter expirations have faster decay but less premium; longer expirations carry more risk of adverse moves.
Bear Call Spread Payoff: Max Profit, Max Loss & Breakeven
The bear call spread has a well-defined payoff profile. All formulas below are expressed per share and represent outcomes at expiration, excluding commissions and taxes.
For a credit smaller than half the spread width, the maximum loss exceeds the maximum profit. Strikes above spot can offer a higher probability of expiring worthless, in exchange for a smaller credit. Net vega is often negative in that region, so falling IV can help, but it may turn positive in another price region; inspect the actual legs rather than infer vega from the credit.
Bear Call Spread Example
In this hypothetical example, AAPL is trading at $182. You are neutral to slightly bearish and want to collect premium with defined risk.
- Sell 1 AAPL $185 call at $4.00/share ($400 received)
- Buy 1 AAPL $195 call at $1.50/share ($150 paid)
- Net credit = $4.00 – $1.50 = $2.50/share ($250 total)
Both calls have the same expiration date and each contract covers 100 shares. Hold both legs through expiration and vary only AAPL’s price at that date; the following payoff includes the initial credit and excludes fees, taxes, and early-assignment effects.
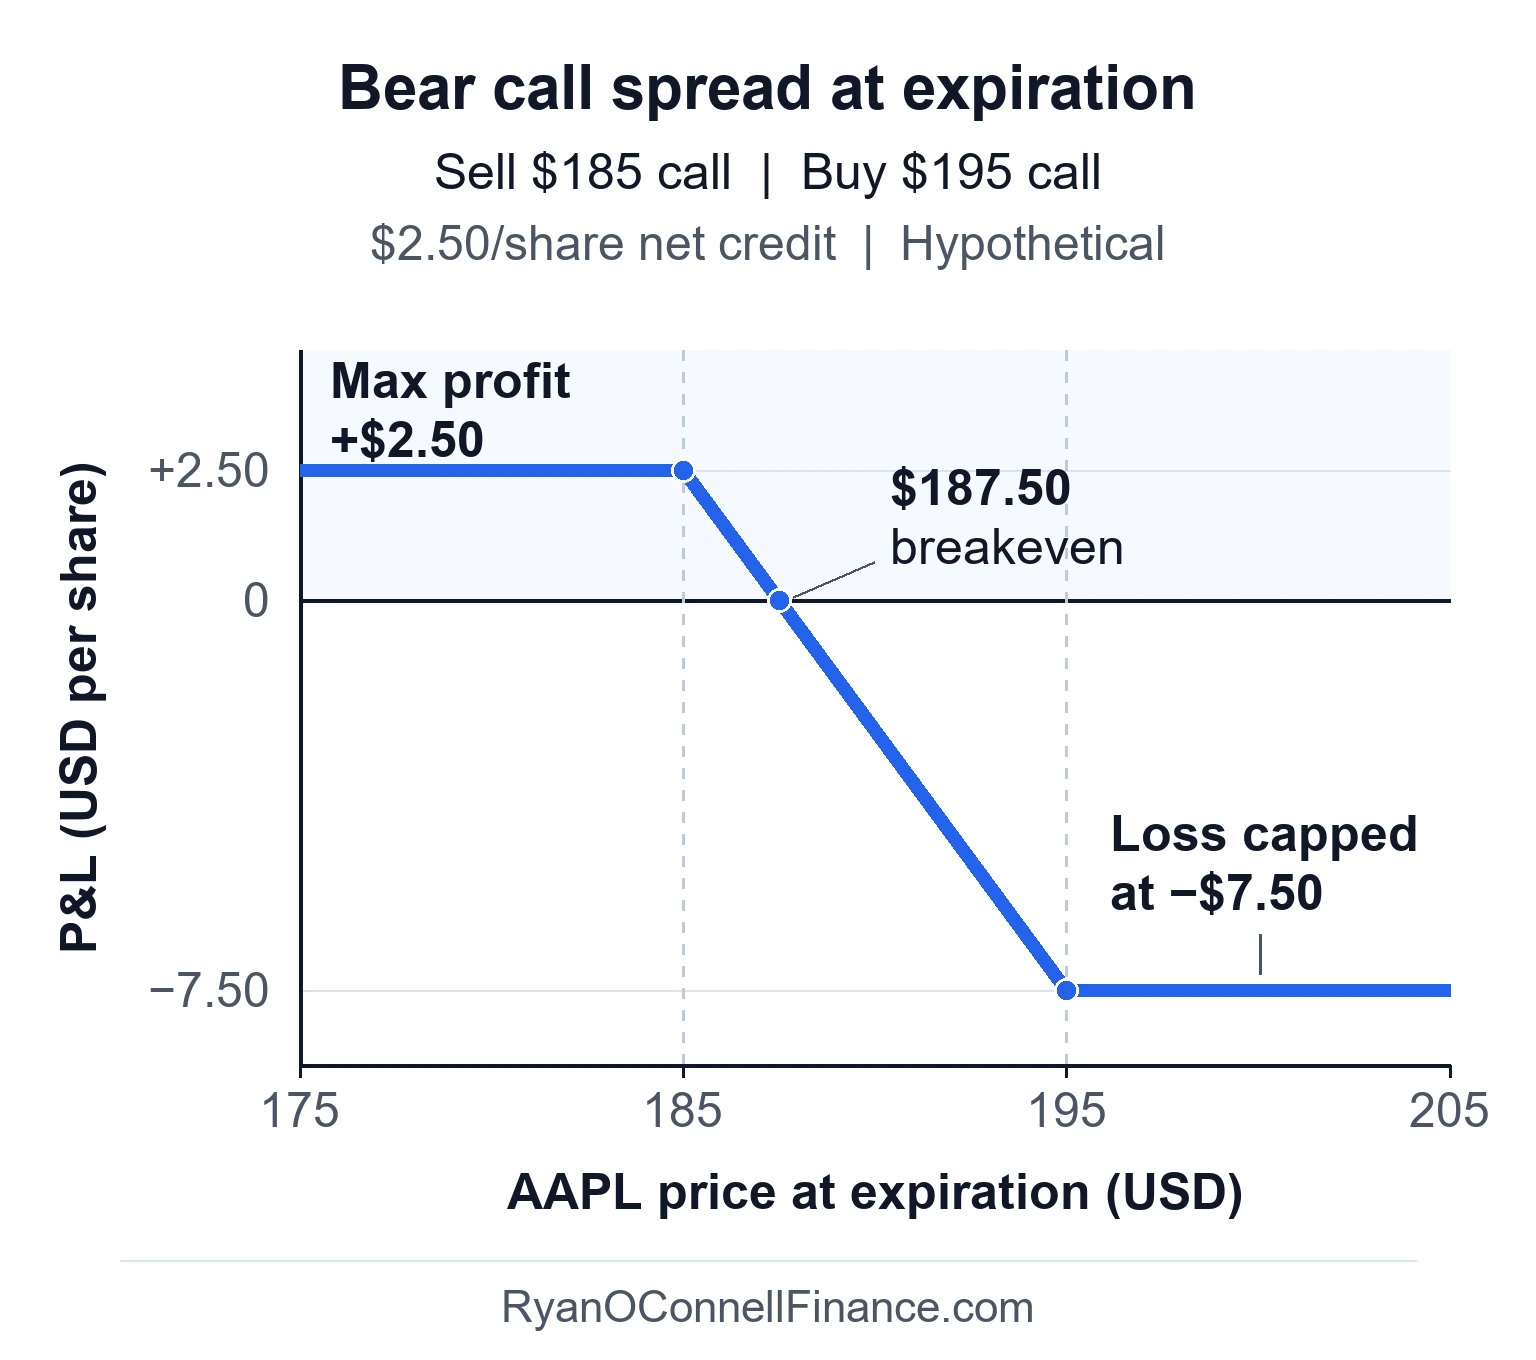
The spread keeps the full $2.50 credit at or below $185 and breaks even at $187.50. At $195, the loss reaches $7.50 per share ($750 for one spread); above that price, each extra dollar lost on the short call is offset by a dollar gained on the long call.
| Scenario | AAPL Price | Short $185 Call | Long $195 Call | Per-Share P&L | Total P&L |
|---|---|---|---|---|---|
| Stock stays below short strike | $180 | Expires worthless | Expires worthless | +$2.50 | +$250 |
| Stock at breakeven | $187.50 | -$2.50 intrinsic | Expires worthless | $0.00 | $0 |
| Stock between strikes | $190 | -$5.00 intrinsic | Expires worthless | -$2.50 | -$250 |
| Stock above long strike | $200 | -$15.00 intrinsic | +$5.00 intrinsic | -$7.50 | -$750 |
Notice that at $200 (or any price above $195), the loss is capped at $7.50 per share. The long $195 call offsets any further losses on the short $185 call beyond the spread width.
Bear Call Spread vs Bear Put Spread
Both spreads express a bearish outlook, but differ in option type, initial cash flow, financing, and margin treatment. The bear put spread is a debit spread using puts, while the bear call spread is a credit spread using calls.
Bear Call Spread
- Credit spread — collect premium upfront
- Uses call options
- Theta can be positive or negative; check the net legs
- Best for neutral-to-bearish outlook
- Requires margin (spread width minus credit)
- Max loss exceeds max profit only if credit is below half the width
Bear Put Spread
- Debit spread — pay premium upfront
- Uses put options
- Theta can be positive or negative; check the net legs
- Best for directionally bearish outlook
- No additional margin beyond the debit paid
- Risk/reward depends on strike selection and debit paid
For the same strikes and expiration, European bear call and bear put counterparts have the same gamma and vega by put-call parity; value and theta differences reflect deterministic financing/carry. Choose between them using executable prices, financing, margin, and exercise/assignment considerations. Different strike selections can create different breakevens and exposures, but collecting rather than paying premium does not itself create a theta advantage.
When to Use a Bear Call Spread
Bear call spreads work best under specific conditions:
- Your outlook is bearish or neutral — you expect the stock to stay flat, drift lower, or at least remain below a resistance level through expiration.
- You want defined risk — unlike selling naked calls, the long call caps your maximum loss at a known amount.
- You prefer collecting premium — credit spreads collect cash on day one, while subsequent profit depends on prices, carry, and the net option sensitivities.
- You have assessed volatility exposure — compare each leg’s IV and the net vega. Falling IV helps a negative-vega position and hurts a positive-vega one; high IV alone does not establish an attractive trade.
- You have a target resistance level — place the short strike at or above a level you believe the stock will not breach.
Managing the trade: Many traders close bear call spreads early when they’ve captured 50-75% of the maximum credit, rather than holding to expiration and risking a reversal. If the spread moves against you, consider closing at a predefined loss threshold (e.g., when losses equal 1.5-2x the credit received) or rolling the spread to higher strikes and a later expiration. Learn more strategies like this in our Options Trading Strategies course.
Common Mistakes
Avoid these common pitfalls when trading bear call spreads:
- Selling the spread too close to the current stock price. At-the-money or near-the-money short strikes generate higher premiums but significantly increase the probability that the stock will move through your breakeven. Choose OTM strikes with a comfortable margin of safety.
- Underestimating early assignment risk. American-style options can be exercised at any time. If your short call goes deep in the money — especially near an ex-dividend date — the holder may exercise early, forcing you to deliver shares you don’t own.
- Not having an adjustment or exit plan. Letting a losing bear call spread run to maximum loss is a common and costly mistake. Define your exit criteria before entering the trade: a loss threshold, a time-based stop, or a technical level that invalidates your thesis.
- Ignoring earnings or catalyst dates. Unexpected earnings surprises, FDA decisions, or macro events can cause the stock to gap through both strikes overnight, making adjustment impossible.
- Holding through expiration near the short strike (pin risk). When the stock closes near your short strike at expiration, you face uncertainty about whether the short call will be assigned. Close spreads before expiration if the stock is near the short strike to avoid unexpected assignment over the weekend.
Risks and Limitations
Bear call spreads have an asymmetric risk profile — your maximum loss is typically several times larger than your maximum profit. Never allocate more capital to credit spreads than you can afford to lose, and always size positions so that a max-loss outcome does not materially impact your portfolio.
Limited profit potential. Your profit is capped at the net credit received. No matter how far the stock falls below your short strike, you cannot earn more than the initial credit.
Larger losses than gains. The spread width minus the credit determines your max loss; it exceeds the max profit only when the credit is less than half the spread width. A $10-wide spread with a $2.50 credit risks $7.50 to make $2.50 — a 3-to-1 risk/reward ratio.
Early assignment on the short call. If the short call moves deep in the money, the holder may exercise early. This is most likely near ex-dividend dates or when the call has little extrinsic value remaining. If assigned, you’ll be short 100 shares until you exercise your long call or close the position.
Margin requirements. Your broker will require margin equal to the spread width minus the credit received. For the AAPL example above, that’s $750 per contract — capital that is tied up until the spread is closed or expires.
For the opposite directional view, see the bull call spread, which is a debit spread that profits from moderate upside.
Frequently Asked Questions
Disclaimer
This article is for educational and informational purposes only and does not constitute investment advice. Options trading involves significant risk and is not suitable for all investors. The examples and calculations shown are at expiration and exclude commissions, fees, and taxes. Always conduct your own research and consult a qualified financial advisor before trading options.
Keep reading
Next in this series
Part 8 of 17 in Option Strategies
Bull Put Spread: Strategy & Payoff DiagramMore in Options & Derivatives
-
Call Options: Buying and Selling Calls Explained
Complete guide to call options — how they work, buying vs selling calls, payoff diagrams, and when to use call options in your trading strategy.
-
Put Options: Buying and Selling Puts Explained
Complete guide to put options — how they work, buying vs selling puts, payoff diagrams, hedging applications, and when to use put options.
-
Option Greeks: The Complete Beginner’s Guide
Complete guide to the five option Greeks — delta, gamma, theta, vega, and rho — what they measure, how they interact, and how to use them for options analysis.

