
Open Interest in Options: How to Read and Use It for Trading

Table of Contents
Open interest is one of the most important — and most misunderstood — metrics in options trading. While most traders focus on price and volume, open interest reveals something different: how many contracts remain outstanding at a given strike and expiration, adding context to activity and potential positioning concentrations. Whether you’re selecting strikes, filtering for liquidity, or trying to confirm a trend, understanding open interest in options gives you a critical edge. This guide covers what open interest is, how it changes, how to interpret it, and how to use it in your options trading decisions.
What Is Open Interest in Options?
Open interest (OI) is the total number of outstanding option contracts that have not been closed, exercised, or expired. Every options contract has two sides — a buyer and a seller. Open interest counts each of these matched contracts as one unit. When a new buyer and a new seller enter a trade, one new contract is created and OI increases by one.
Open interest represents the total number of active positions in a specific option contract. It is tracked per strike price and expiration date — not as a single aggregate number for the entire option chain. Always check OI at the specific strike and expiration you plan to trade.
Open interest applies to both call options and put options. It is distinct from volume, which measures how many contracts traded during a single session. Volume resets each day; open interest does not — it is a cumulative figure that changes only at the end of the trading day after clearing.
How Open Interest Changes
Open interest changes based on whether a trade creates a new contract or closes an existing one. There are three scenarios:
| Scenario | Party A | Party B | OI Change |
|---|---|---|---|
| New position opened | Opens new long (buys to open) | Opens new short (sells to open) | +1 |
| Existing position closed | Closes existing long (sells to close) | Closes existing short (buys to close) | -1 |
| Position transferred | Opens new long (buys to open) | Closes existing long (sells to close) | No change |
Scenario 1: Both parties are opening new positions — one buys to open (new long) and the other sells to open (new short). A new contract is created and OI increases by one.
Scenario 2: Both parties are closing existing positions — the long holder sells to close and the short holder buys to close. The contract is eliminated and OI decreases by one.
Scenario 3: One party is opening a new position while the other is closing an existing one. The contract transfers from the exiting trader to the new one. No new contract is created and no existing contract is eliminated, so OI remains unchanged.
Open interest is updated once per day after clearing. The figure published the next morning may be preliminary and can be revised. Intraday OI changes are not visible — the number you see during the trading session reflects the previous day’s close.
Open Interest vs Volume in Options
Volume and open interest are related but measure different things. Understanding the distinction is essential for reading an options chain correctly.
Volume
- Contracts traded during the current session
- Resets to zero at the start of each trading day
- Measures trading activity
- Can exceed OI (same contract traded multiple times)
- High volume = active trading interest today
Open Interest
- Total outstanding contracts across all sessions
- Cumulative — changes only at end-of-day
- Measures market commitment
- Updated after clearing each night
- High OI = sustained positioning at that strike
The most useful insight comes from reading volume and OI together. Rising OI means more contracts remain outstanding on net; falling OI means fewer remain. High volume with little OI change can reflect transfers or opening and closing trades that offset. These totals do not identify the traders’ motives or directional exposures. For a deeper dive into volume analysis and execution quality, see our guide on trading execution.
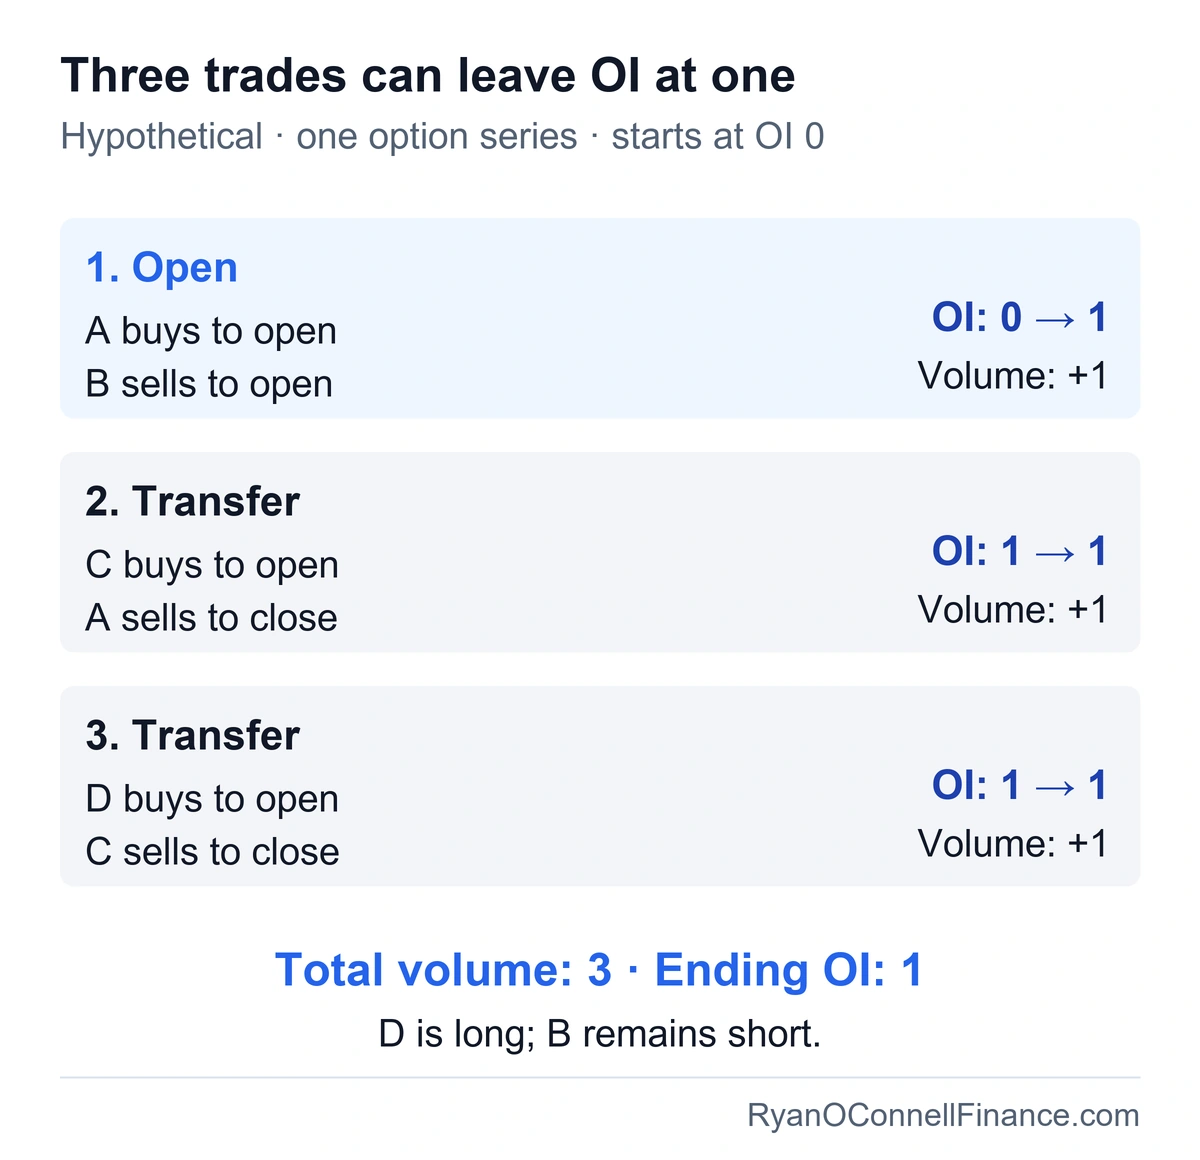
Three trades create only one outstanding contract in this sequence. The long position changes hands from A to C to D while B remains short; each matched trade contributes one to volume, not two.
Open Interest Example
Start with no open contracts in this option series. On Day 1, 500 contracts trade between parties opening positions. On Day 2, 200 contracts open and 100 close; on Day 3, 400 close. Compare each day’s volume with contracts still outstanding.
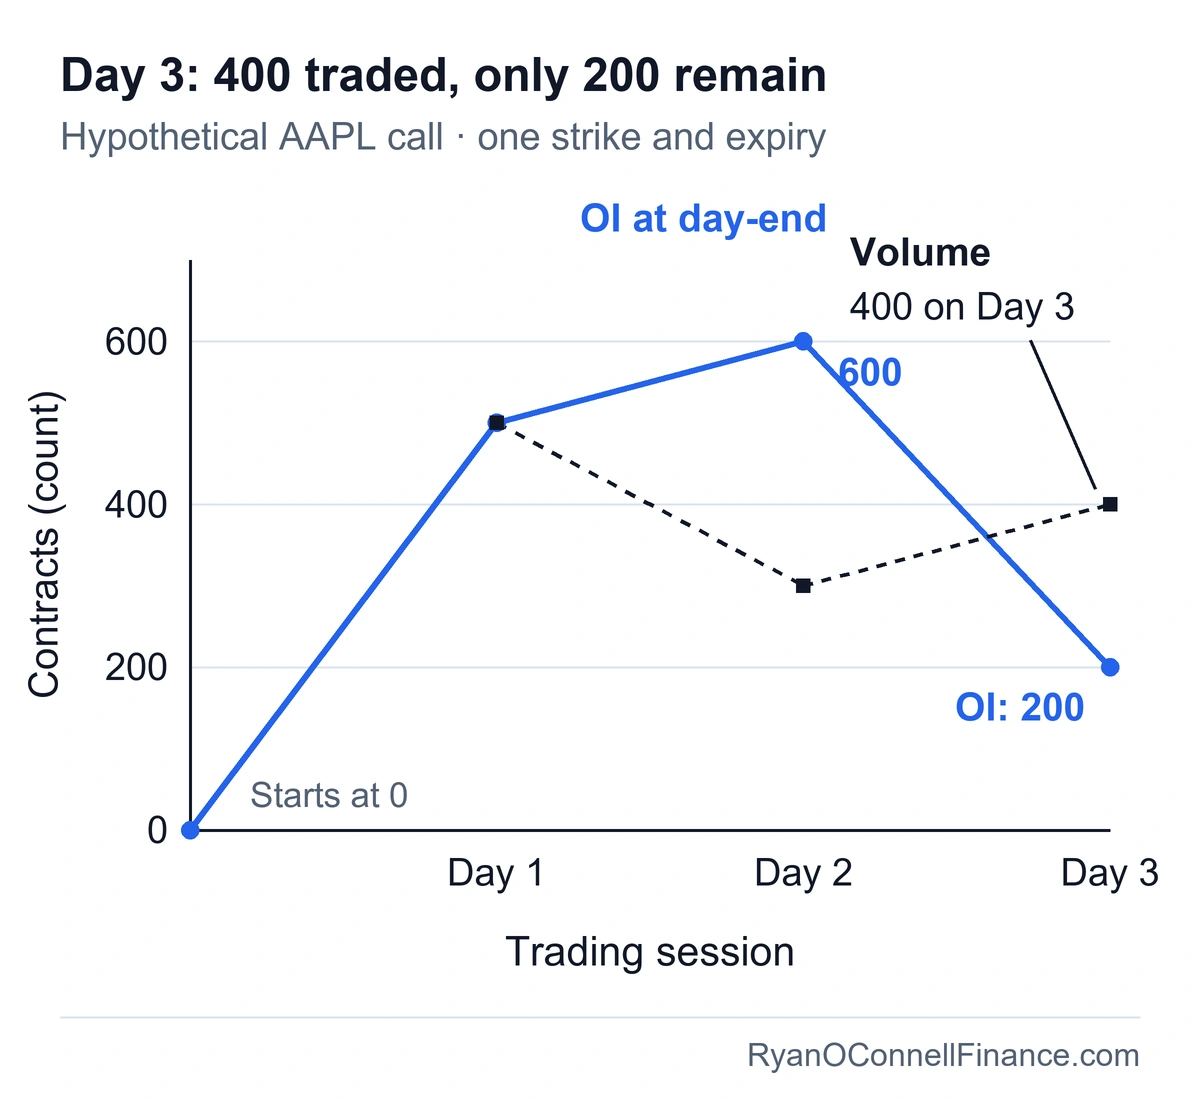
Day 1: 500 contracts trade between new buyers and new sellers. All are new positions, so OI rises from 0 to 500.
Day 2: 300 contracts trade. Of these, 200 match buyers and sellers who are both opening (OI +200), and 100 match holders who are both closing (OI -100). Net change: +100. OI rises to 600.
Day 3: 400 contracts trade, but all match long and short holders closing their positions. OI falls by 400, dropping to 200.
Notice that volume was 400 on Day 3 even though OI dropped — volume measures activity, while OI measures how many positions remain outstanding.
How to Interpret Open Interest
Traders often use the relationship between OI changes and price direction as a heuristic for gauging market sentiment. These are guidelines, not rules — every open contract has both a long and a short holder, so OI alone cannot tell you net direction.
| OI Trend | Price Trend | Interpretation | What It May Suggest |
|---|---|---|---|
| Rising OI | Rising price | More contracts outstanding; both longs and shorts added | Price rises, but OI does not identify the driving side |
| Rising OI | Falling price | More contracts outstanding; both longs and shorts added | Price falls, but OI does not identify the driving side |
| Falling OI | Rising price | Fewer outstanding contracts; longs and shorts both exit | Cannot isolate short covering as the cause of the rise |
| Falling OI | Falling price | Fewer outstanding contracts; longs and shorts both exit | Cannot establish trend exhaustion from OI alone |
Price direction and OI are separate observations. Every open contract has both a long and a short holder, so rising or falling OI does not reveal which side initiated trades or whether a position is part of a hedge. Price and volume add context, but do not resolve those details without further trade-level information.
Open Interest and Liquidity
One of the most practical uses of open interest is as a liquidity filter. Strikes with high OI generally have tighter bid-ask spreads, more market makers quoting the contract, and better fill quality. Strikes with low OI tend to have wider spreads, making it harder and more expensive to enter or exit positions.
However, high OI does not guarantee tight spreads. Far out-of-the-money contracts or options on less actively quoted underlyings can have decent OI but still trade with wide bid-ask spreads. Always check the actual spread before entering a trade, not just the OI number.
Consider two hypothetical option series, each with open interest of 5,000 and standard 100-share contracts. Series A is quoted at $2.00 bid/$2.05 ask, while Series B is $2.00/$2.30. Compare the quoted spread cost per contract.
| Option series | Quoted gap ($/contract) |
|---|---|
| Series A | 5 |
| Series B | 30 |
Hypothetical: both have OI 5,000. A is $2.00 bid / $2.05 ask; B is $2.00 / $2.30. Gap uses 100-share contracts; excludes fees and quote changes.
At unchanged quotes, buying at the ask and immediately selling at the bid would lose $5 for A versus $30 for B per standard contract, before fees. Their identical OI does not tell you that cost; check current bid-ask prices and displayed size.
Open interest also naturally declines as expiration approaches. During the final days before expiry and during roll periods, traders close near-term positions and move to later expirations. This is normal — a sudden drop in OI near expiration does not necessarily signal bearish sentiment.
Consider the difference between a liquid name like AAPL — where popular strikes may show tens of thousands of contracts in OI with penny-wide spreads — versus a smaller name like RIVN (Rivian), where even the most active strikes may carry only a few hundred contracts of OI and spreads of $0.05 to $0.15 or wider. The execution quality difference is significant, especially for multi-leg strategies. For more on how order execution and fill quality affect your trading, see our guide on trading execution.
Before entering any options trade, check the open interest at your target strike and expiration. A few hundred contracts may be a starting screen, but no OI threshold ensures liquidity; check the live spread and quoted size for your intended order.
How to Use Open Interest in Options Trading
Beyond liquidity filtering, open interest data can inform several aspects of trade planning:
Strike selection: When choosing between multiple strike prices, use OI as an activity screen, then compare current spreads and quoted size to assess likely execution costs. This is especially important for multi-leg strategies like spreads and condors, where poor fills on even one leg can significantly affect the trade’s risk-reward profile.
Identifying potential support and resistance: Large concentrations of OI at specific strikes can sometimes act as magnets or barriers for the underlying stock price. This happens partly because dealers who sold options at those strikes must hedge their exposure — as the stock approaches a high-OI strike, the hedging activity itself can influence price movement. For a deeper look at how dealer hedging and OI interact, see our article on gamma squeezes.
Max pain: For one expiration and a fixed OI snapshot, the max pain level is the candidate stock price that minimizes the aggregate intrinsic payout across outstanding calls and puts. It does not measure holders’ actual losses because their premiums, entry dates and hedges are unknown. Some traders monitor this level heading into expiration, but the calculation does not establish that the stock will gravitate toward it.
For example, use this synthetic three-strike chain with standard 100-share contracts. At each candidate settlement price, add call OI × max(stock price – strike, 0) and put OI × max(strike – stock price, 0), then multiply by 100:
| Strike ($) | Call OI (contracts) | Put OI (contracts) |
|---|---|---|
| 90 | 10 | 80 |
| 100 | 80 | 80 |
| 110 | 80 | 10 |
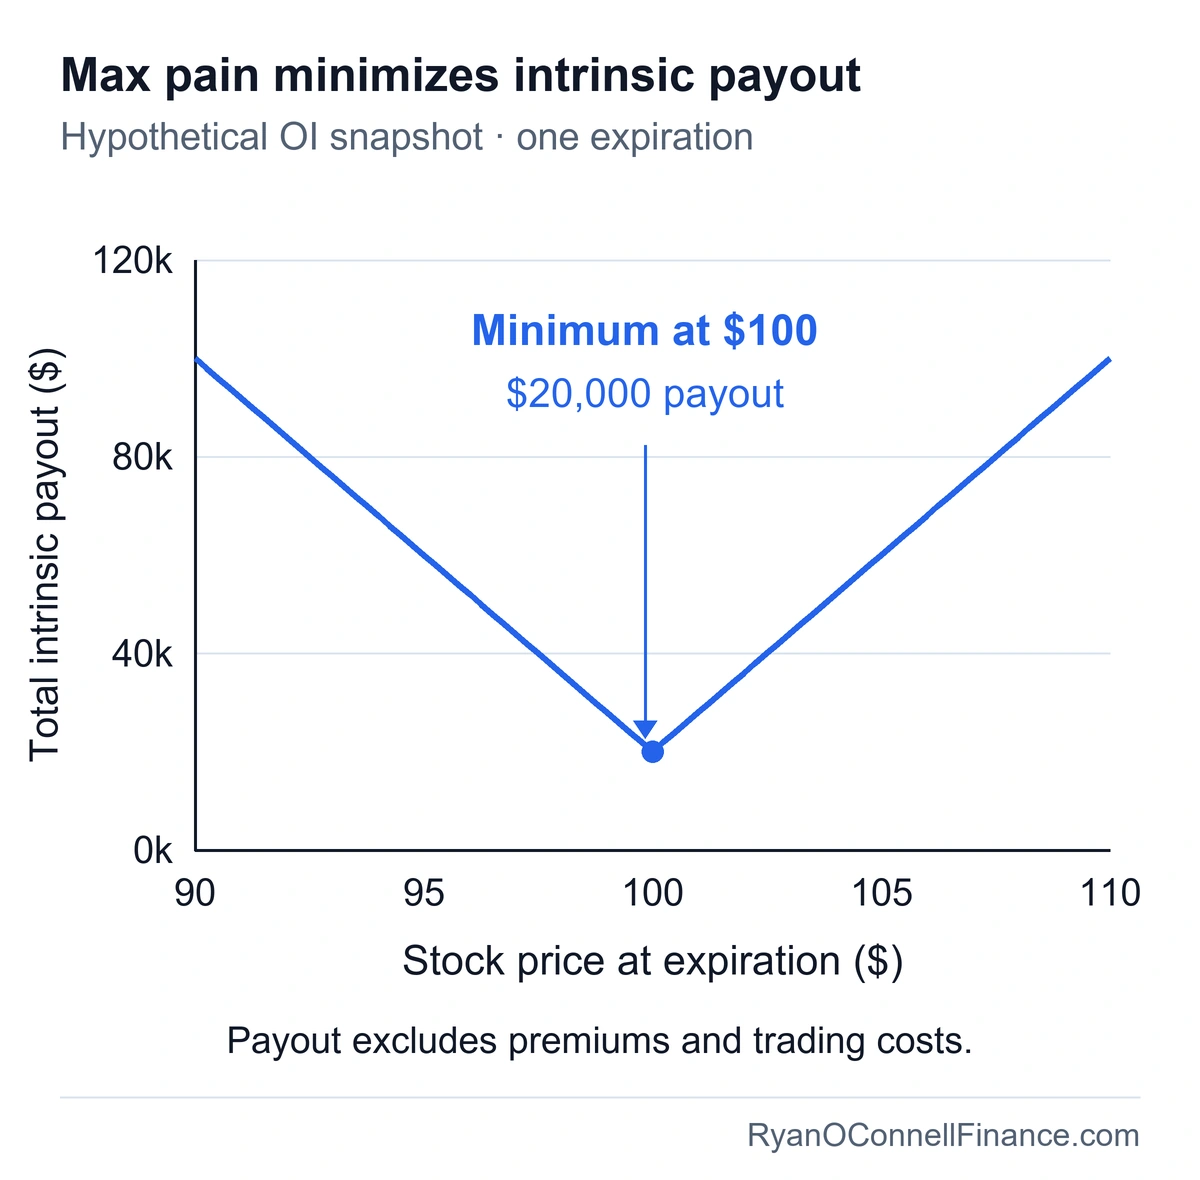
At $100, the $90 calls and $110 puts each contribute $10,000, for a $20,000 minimum. At $90 or $110, total intrinsic payout is $100,000. This is an arithmetic property of the hypothetical OI snapshot, not a price target.
Max pain is a popular concept, but it is not a reliable price predictor. Academic research does not consistently support max pain as a trading strategy. While stocks sometimes do settle near the max pain strike at expiration, there is no robust evidence that this happens frequently enough to trade on. Use it as one data point among many — not as a standalone signal.
Common Mistakes
Open interest is a useful metric, but misinterpreting it can lead to poor trading decisions. Here are the most common mistakes:
1. Confusing volume with open interest. Volume tells you how many contracts traded today and resets each session. Open interest tells you how many contracts remain outstanding. They measure different things — a high-volume day does not necessarily mean OI increased if most trades were closing existing positions.
2. Assuming high OI means the stock will move to that strike. High open interest at a strike reflects existing positions — it does not mean the stock is being “pulled” toward that price. While high-OI strikes can sometimes act as support or resistance due to dealer hedging, this is not a reliable price predictor.
3. Ignoring OI when selecting strikes. Very low open interest can accompany wider bid-ask spreads, harder execution and more slippage, but OI alone does not establish current liquidity. Always check OI before placing a trade, especially for multi-leg strategies where poor fills compound.
4. Using OI as a standalone directional indicator. Because every contract has both a long and a short holder, OI alone tells you nothing about whether the market is net bullish or bearish. OI is a confirmation tool — it adds context to price and volume trends, but it cannot predict direction on its own.
5. Making intraday decisions based on stale OI data. Open interest is an end-of-day figure. The OI number displayed during the trading session reflects the previous day’s close, not current positioning. Do not assume that intraday price moves are reflected in the OI figure you see on your screen — those changes will not appear until the next morning.
Risks and Limitations
Open interest is a valuable tool, but it has significant limitations that every trader should understand before relying on it for decisions.
End-of-day data only. OI is not updated in real time. The figure you see during the trading day is from the previous session’s close. This lag means OI cannot capture intraday positioning shifts.
No directional information. OI counts matched long and short contracts equally. A strike with 10,000 contracts of OI has 10,000 long contracts and 10,000 short contracts; the figure does not reveal who initiated the trades or whether those exposures belong to hedged portfolios.
Institutional hedging can distort signals. Large institutional players — particularly market makers and dealers — often hold options positions as part of complex hedging strategies, not as directional bets. Their activity can inflate OI at certain strikes in ways that do not reflect retail sentiment or directional conviction.
Max pain theory is unreliable. While max pain is widely discussed, the evidence that stocks consistently settle at the max pain strike is weak. Treat it as a supplementary observation, not a tradable signal.
OI must be combined with other data. On its own, open interest provides incomplete information. It becomes meaningful when analyzed alongside price direction, volume, implied volatility, and the specific context of the underlying asset. No single metric tells the full story.
Frequently Asked Questions
Disclaimer
This article is for educational and informational purposes only and does not constitute investment advice. Open interest data, examples, and interpretations are illustrative and should not be used as the sole basis for trading decisions. Always conduct your own research and consult a qualified financial advisor before making investment decisions.
Keep reading
You’ve finished Option Strategies. See all Options & Derivatives articles
More in Options & Derivatives
-
Call Options: Buying and Selling Calls Explained
Complete guide to call options — how they work, buying vs selling calls, payoff diagrams, and when to use call options in your trading strategy.
-
Put Options: Buying and Selling Puts Explained
Complete guide to put options — how they work, buying vs selling puts, payoff diagrams, hedging applications, and when to use put options.
-
Option Greeks: The Complete Beginner’s Guide
Complete guide to the five option Greeks — delta, gamma, theta, vega, and rho — what they measure, how they interact, and how to use them for options analysis.

