
Preferred Stock: Features, Yields & Valuation

Table of Contents
Preferred stock is a hybrid security that combines features of both debt and equity. For income-focused investors and those analyzing corporate capital structures, understanding preferred stock’s unique characteristics — fixed dividends, priority claims, and tax advantages — is essential. This guide covers the types of preferred stock, how yields work, the dividends received deduction, and when preferred stock makes sense in a portfolio.
What Is Preferred Stock?
Preferred stock is an equity security that sits between common stock and bonds in a company’s capital structure. It typically pays a fixed dividend and has a higher claim on assets and earnings than common stock, but a lower claim than bondholders.
Preferred stock is a hybrid security: it’s classified as equity on the balance sheet and pays dividends (not interest), but it behaves like a bond with fixed payments and limited upside. In bankruptcy, preferred shareholders are paid after bondholders but before common stockholders.
Unlike common stockholders, preferred shareholders typically don’t have voting rights. In exchange, they receive priority for dividend payments — the company must pay preferred dividends before any common dividends can be distributed. This priority makes preferred stock attractive to investors seeking reliable income streams.
Most preferred stock is issued at a par value (commonly $25 or $100) with a stated dividend rate. For example, a $25 par preferred stock with a 6% dividend rate pays $1.50 per year ($25 × 6%). These dividends are usually paid quarterly.
Types of Preferred Stock
Preferred stock comes in several varieties, each with distinct features that affect risk and return:
| Type | Key Feature | Investor Implication |
|---|---|---|
| Cumulative | Missed dividends accumulate as arrears before common dividends can resume | Stronger protection; arrears must be cleared before common dividends |
| Non-Cumulative | Missed dividends are forfeited permanently | Higher risk; no recourse if company skips payments |
| Participating | Shares in additional profits beyond stated dividend | Rare today; offers upside beyond fixed rate |
| Convertible | Can be converted into common shares | Provides equity upside while collecting dividends |
| Perpetual | No maturity date | Income stream continues indefinitely; interest rate sensitive |
| Dated (Term) | Has a stated maturity date | Principal returned at maturity; behaves more like a bond |
Cumulative vs. Non-Cumulative
The distinction between cumulative and non-cumulative preferred stock is critical. With cumulative preferred, if a company misses dividend payments, those dividends accrue as “dividends in arrears.” The company cannot pay any common stock dividends until all accumulated preferred dividends are paid. This provides significant protection for preferred shareholders.
With non-cumulative preferred, missed dividends are simply lost — the company has no obligation to make them up later. This weaker position is reflected in higher dividend yields to compensate investors for the additional risk.
Consider two hypothetical issues with the same $25 stated amount and 6% annual dividend, one cumulative and one non-cumulative. An investor holds 100 shares of each, so each would pay $37.50 quarterly when declared. Both start with no arrears, and neither declares or pays a dividend in Q1 or Q2. In Q3, assume both pay the current preferred dividend; the cumulative issuer also clears all arrears before restarting common cash dividends. No interest accrues on the arrears.
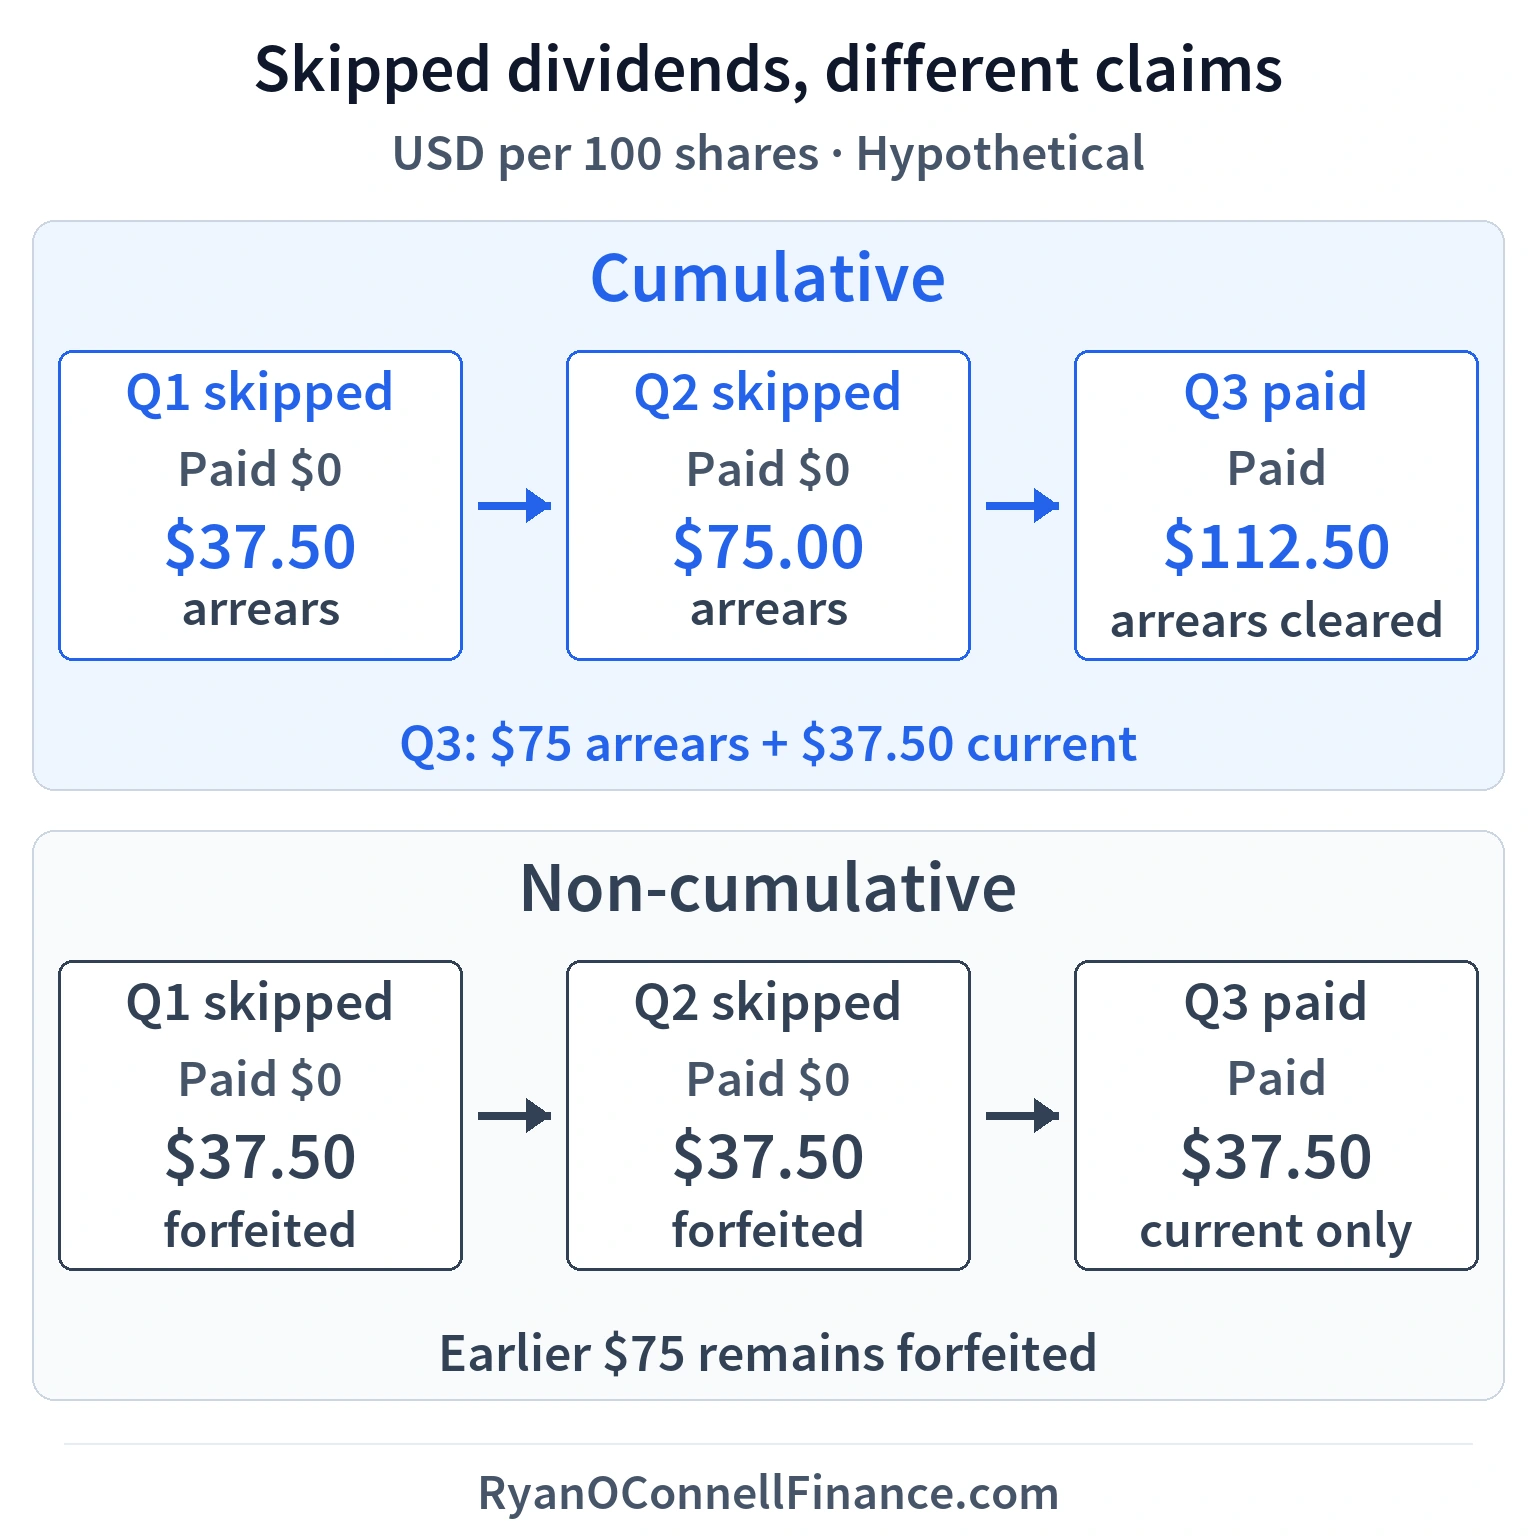
The cumulative issue pays $112.50 in Q3: $75 of arrears plus the $37.50 current dividend. The non-cumulative issue pays only the current $37.50; the earlier $75 stays lost. Cumulative status preserves the arrears claim before common dividends resume, but it does not guarantee that the issuer will ever have the funds to pay it.
Dividend example data (USD per 100 shares)
| Event | Cumulative | Non-cumulative |
|---|---|---|
| Q1 skipped | $0 paid; $37.50 arrears | $0 paid; $37.50 forfeited |
| Q2 skipped | $0 paid; $75.00 total arrears | $0 paid; $75.00 forfeited to date |
| Q3 payment assumed | $112.50 paid; arrears cleared | $37.50 paid; prior $75.00 remains forfeited |
Preferred Stock Features
Beyond dividend structure, preferred stock typically includes several important provisions:
Fixed Dividend Rate — Most preferred stock pays a fixed dividend, either as a dollar amount or percentage of par value. Some adjustable-rate preferred stock resets quarterly based on Treasury benchmarks, but fixed-rate remains the standard.
Call Provisions — Nearly all preferred stock is callable, meaning the issuer can redeem shares at par (plus any accrued dividends) after a specified date. This protects the issuer if interest rates fall — they can refinance at lower rates. For investors, call risk means you may lose a high-yielding security when rates drop.
Sinking Fund — Many preferred issues include a sinking fund provision requiring the company to retire a portion of the outstanding shares annually. This reduces credit risk over time and provides a floor for the stock price, as shares may be called at par for the sinking fund.
Contingent Voting Rights — While preferred shareholders typically don’t vote, many issues grant voting rights if dividends fall into arrears. After a specified number of missed payments (often six quarters), preferred shareholders may elect directors to the board.
Always check the call date and call price before buying preferred stock. A preferred trading at $27 with a $25 call price and an imminent call date could result in a capital loss if the issuer redeems the shares.
Trust Preferred Securities
Trust Preferred Securities (TruPS or TOPrS) are a special category of preferred stock with unique structural features. In a TruPS structure, a parent company creates a Delaware statutory business trust, which issues the preferred securities to investors. The parent company guarantees the trust’s obligations.
The key advantage for issuers: TruPS dividend payments are tax-deductible for the parent company, unlike regular preferred dividends. This makes TruPS cheaper to issue than traditional preferred stock. Rating agencies also give partial equity credit to TruPS, helping improve capital ratios.
For investors, TruPS have important differences from regular preferred stock:
- No DRD benefit — TruPS dividends do not qualify for the dividends received deduction, making them less attractive to corporate investors
- Deferral risk — Issuers can defer dividend payments for up to 20 quarters (5 years) without triggering default, though they cannot pay common dividends during deferral
- Higher yields — To compensate for deferral risk and loss of DRD, TruPS typically offer higher yields than traditional preferred stock
Banks historically issued significant amounts of TruPS to count toward regulatory capital requirements, though post-2008 regulations have limited their use for this purpose.
Preferred Stock Yields
Understanding yield metrics is essential for comparing preferred stock investments:
| Yield Metric | Formula | When to Use |
|---|---|---|
| Dividend Yield | Annual Dividend / Market Price | Income snapshot; excludes price gains or losses |
| Current Yield | Same as dividend yield for preferred | Snapshot of income relative to price |
| Yield to Call | IRR assuming called at first call date | When trading above par near call date |
| Yield to Worst | Minimum of YTC and current yield | Conservative estimate; most realistic return |
Dividend Yield is the simplest measure — annual dividend divided by market price. If a preferred pays $1.50 annually and trades at $24, the dividend yield is 6.25% ($1.50 / $24).
Yield to Call accounts for capital gains or losses if the preferred is redeemed early. If you buy a $25 par preferred at $26 and it’s called at $25 in two years, you’ll lose $1 in principal — yield to call incorporates this loss into the return calculation.
Yield to Worst is the most conservative measure, representing the minimum yield you could receive under reasonable scenarios. Professional investors typically focus on yield to worst when evaluating callable preferred stock.
Dividends Received Deduction
One of the most important tax features of preferred stock is the Dividends Received Deduction (DRD). When one corporation owns preferred stock of another corporation, it can exclude a significant portion of dividend income from taxation.
The DRD allows corporate investors to exclude 50% to 100% of preferred dividends from taxable income, depending on ownership percentage. This makes preferred stock significantly more attractive to corporate investors than bonds, where interest is fully taxable.
Current DRD tiers based on ownership of the dividend-paying company:
| Ownership Level | DRD Percentage | Taxable Portion |
|---|---|---|
| Less than 20% | 50% | 50% of dividends |
| 20% to 80% | 65% | 35% of dividends |
| More than 80% | 100% | 0% of dividends |
This tax advantage creates strong corporate demand for preferred stock, particularly from insurance companies, banks, and other financial institutions with large investment portfolios. The resulting demand allows issuers to pay lower dividend yields than they would otherwise need to offer.
Individual investors don’t receive the DRD — it only applies to corporate holders. However, preferred dividends may qualify for the lower qualified dividend tax rate (0%, 15%, or 20%) rather than ordinary income rates, depending on holding period and other requirements.
Preferred Stock vs. Bonds
Preferred stock and bonds share similarities as fixed-income investments, but important differences affect risk and return:
Preferred Stock
- Equity classification on balance sheet
- Dividends not tax-deductible to issuer
- DRD benefit for corporate holders
- Junior to all debt in bankruptcy
- Missed payments don’t trigger default
- Often perpetual (no maturity)
Corporate Bonds
- Debt classification on balance sheet
- Interest is tax-deductible to issuer
- No DRD benefit; interest fully taxable
- Senior to all equity in bankruptcy
- Missed payments trigger default
- Fixed maturity date with principal return
The priority difference matters most in distress. Bondholders must be paid in full before preferred shareholders receive anything in bankruptcy. This lower priority is reflected in higher yields — preferred stock from the same issuer typically yields 100-200 basis points more than senior bonds.
For a deeper understanding of how preferred stock fits within a company’s financing decisions, see our guide on capital structure theory.
How to Calculate Preferred Stock Yields
Calculating preferred stock yields helps you compare investments and make informed decisions. The most common calculation is dividend yield:
For non-callable, non-convertible perpetual preferred stock with constant dividends paid indefinitely, you can use a perpetuity model with a constant required yield:
A hypothetical preferred stock pays a fixed annual dividend of $1.75 per share in four quarterly installments of $0.4375. Suppose you buy it at $26.50 immediately after a dividend date:
Dividend Yield = $1.75 / $26.50 = 6.60%
Assume all four dividends are paid and the issuer calls the shares for $25 exactly one year later, immediately after the fourth payment. Ignore taxes, fees and reinvestment; there is no conversion feature. The $26.50 purchase price exceeds the call price, so the redemption creates a capital loss even though the dividend is paid.
| Cash-flow component | Cash flow (USD/share) |
|---|---|
| Dividends | 1.75 |
| Call loss | -1.50 |
| Cash profit | 0.25 |
Hypothetical one-year call at $25 after a $26.50 purchase; no taxes, fees or reinvestment.
The $1.50 call loss consumes most of the $1.75 dividend, leaving $0.25 per share in cash profit over the year. The 6.60% current yield measures income relative to purchase price; it does not deduct that loss. Yield to call incorporates both the payment timing and the redemption value, so it is much lower here. The $25 redemption is returned capital, not an additional $25 of profit.
For more complex scenarios involving yield to call calculations, convertible preferred valuations, or comparing multiple preferred issues, use our calculator:
Preferred Stock vs. Common Stock
Understanding how preferred stock differs from common stock helps clarify its role in a portfolio:
Preferred Stock
- Fixed dividend (predictable income)
- Priority for dividends and assets
- Limited or no voting rights
- Limited capital appreciation potential
- Less price volatility
- Behaves more like a bond
Common Stock
- Variable dividend (can grow or be cut)
- Last priority for dividends and assets
- Full voting rights
- Unlimited upside potential
- Higher price volatility
- True ownership stake in company
Preferred stock is best suited for investors prioritizing income stability over growth. Common stock offers greater wealth-building potential but with more risk. Many investors hold both, using preferred stock for yield and common stock for appreciation.
For valuing common stock based on expected dividends, see our guide on the dividend discount model.
Limitations
While preferred stock offers attractive features, investors should understand its limitations:
Preferred stock carries significant interest rate risk. Because most preferred stock is perpetual with fixed dividends, prices move inversely with interest rates — rising rates can cause substantial capital losses. The size of the price change depends on the starting required yield, payment structure and embedded options.
Interest Rate Sensitivity — Perpetual preferred stock behaves like a very long-duration bond. When rates rise, prices fall sharply. This creates risk for investors who may need to sell during a rising-rate environment; perpetual stock has no maturity date at which principal is scheduled to be returned.
Return to the earlier $1.50 annual dividend, now using a hypothetical non-callable, non-convertible perpetuity that pays at each year-end forever. Keep the dividend fixed and assume no missed payments or changes in credit quality or liquidity. Compare constant required annual yields from 5% to 8%, using 6% as the starting case. Each price is calculated as P = D / r, with taxes and fees ignored.
| Required yield (%) | Modeled price (USD/share) |
|---|---|
| 5.00 | 30.00 |
| 5.25 | 28.57 |
| 5.50 | 27.27 |
| 5.75 | 26.09 |
| 6.00 | 25.00 |
| 6.25 | 24.00 |
| 6.50 | 23.08 |
| 6.75 | 22.22 |
| 7.00 | 21.43 |
| 7.25 | 20.69 |
| 7.50 | 20.00 |
| 7.75 | 19.35 |
| 8.00 | 18.75 |
Hypothetical fixed $1.50 annual perpetuity; all plotted points are formula-derived and rounded to cents.
At a 6% required yield, the modeled price is $25. At 7%, it falls to $21.43 — a 14.3% decline for a one-percentage-point rise in required yield, with no change in the dividend. These are valuation cases, not a price history or forecast; callable or convertible preferred stock needs its additional features considered.
Call Risk — When rates fall, issuers often call preferred stock to refinance at lower rates. This forces investors to reinvest at lower yields precisely when attractive alternatives are scarce.
Subordination — In bankruptcy, preferred shareholders recover only after all bondholders are paid in full. Credit deterioration can result in total loss even when bondholders receive partial recovery.
No Growth — Unlike common stock dividends, preferred dividends don’t increase with company profits. Over time, inflation erodes the purchasing power of fixed payments.
Illiquidity — Many preferred issues trade infrequently with wide bid-ask spreads, making it difficult to buy or sell large positions without moving the price.
Common Mistakes
Ignoring Yield to Worst — Buying preferred stock trading above par without calculating yield to call. If called at par, the capital loss can significantly reduce or eliminate your return.
Overlooking Credit Risk — Chasing high yields without assessing the issuer’s financial health. Preferred dividends can be suspended, and in bankruptcy, preferred shareholders often receive nothing.
Treating Preferred Like Bonds — Assuming preferred stock offers bond-like safety. Preferred shareholders have no legal recourse if dividends are suspended (unlike bondholders with missed interest).
Ignoring Tax Implications — Individual investors sometimes buy preferred stock designed for corporate investors (who benefit from DRD). The yield premium may not compensate individuals adequately for the added risks.
Not Checking Call Provisions — Failing to review call dates and call prices before purchase. Understanding when and at what price an issue can be called is essential for realistic return expectations.
Frequently Asked Questions
Disclaimer
This article is for educational and informational purposes only and does not constitute investment advice. Preferred stock involves risks including interest rate risk, credit risk, and call risk. Dividend yields and examples cited are illustrative and may differ based on market conditions. Always conduct your own research and consult a qualified financial advisor before making investment decisions.
Keep reading
Next in this series
Part 10 of 17 in Bond & Money Market Instruments
Emerging Markets Debt: Sovereign Bonds, Hard Currency & EM Credit SpreadsMore in Fixed Income
-
Bond Pricing & Yield to Maturity: Complete Guide
Learn how to calculate bond prices and yield to maturity (YTM) with step-by-step formulas and examples for annual and semi-annual coupon bonds.
-
Interest Rate Risk: Duration, Convexity & Hedging
Comprehensive guide to interest rate risk — how duration, convexity, and key rate duration measure bond price sensitivity, with hedging strategies including…
-
Spot Rates and Forward Rates: Complete Guide
Learn the difference between spot rates and forward rates, how to calculate forward rates from spot rates, and how bootstrapping extracts zero-coupon yields…

