
Annualized Return (CAGR): Formula, Calculation, and Examples

Table of Contents
If you’ve ever compared investment returns over multiple years, you’ve likely encountered a confusing array of metrics: CAGR, geometric mean, arithmetic mean, and annualized return. Many investors—and even some financial professionals—mistakenly use arithmetic mean to report multi-year performance, which can overstate actual compounded growth. This article untangles these three commonly confused return metrics and reveals the critical concept of volatility drag: why geometric mean never exceeds arithmetic mean for the same periods, and how a small-return approximation relates this gap to volatility.
What is Annualized Return (CAGR)?
Annualized return, commonly called CAGR (Compound Annual Growth Rate), is the rate at which an investment grows on an annual basis, assuming all gains are reinvested and compounded. Unlike simple averages, CAGR smooths out multi-year volatility into a single, easy-to-compare rate.
CAGR smooths multi-year returns into a single compounded rate that tells you: “If this investment had grown at a steady rate every year, what would that rate be?” It’s the constant annual return that transforms your beginning value into your ending value.
Fund managers report CAGR because it provides a clear, standardized way to compare performance across different time periods and investment vehicles. A fund with a 10% CAGR over 5 years delivered the same ending wealth as one that grew exactly 10% every single year—even if the actual year-to-year returns varied wildly.
CAGR is distinct from arithmetic average return. The arithmetic average simply adds up all the annual returns and divides by the number of years. This approach ignores the compounding effect of gains and losses, which is why it almost always overstates actual wealth accumulation. We’ll explore this critical distinction in depth below.
Annualized Return Formula (CAGR)
Understanding how to calculate annualized returns requires knowing which formula to use based on your available data. There are three primary metrics, each serving different purposes.
CAGR Formula
Where:
- Ending Value — the final portfolio or investment value at the end of the measurement period
- Beginning Value — the initial portfolio or investment value at the start of the measurement period
- n — the number of years (can be fractional, such as 2.5 years for a 30-month period)
This is the explicit annualization formula for any holding period. CAGR works whether you’re measuring nominal returns or real (inflation-adjusted) returns. Use CAGR when you have only beginning and ending values, with no interim data needed. It’s the most common formula in fund performance reports and long-term investment comparisons.
Try our Annualized Return (CAGR) Calculator to compute this instantly with your own data.
Geometric Mean Return Formula
Where:
- R1, R2, …, Rn — individual period returns (expressed as decimals: e.g., 10% = 0.10)
- n — number of periods
- 1 + Ri — the growth factor for period i (also called the “return relative”)
Use geometric mean when you have period-by-period returns and want the compounded growth rate per observation period. The geometric mean of annual returns equals CAGR. A geometric mean calculated from monthly returns is a monthly rate; annualize it as (1 + Rgeometric, monthly)12 – 1 before comparing it with CAGR.
Calculate this with our Geometric Mean Return Calculator.
Holding Period Return Formula
Where:
- Ending Value — final value at end of holding period
- Beginning Value — initial value at start of holding period
- HPR — total percentage return (not per year)
Holding period return measures your cumulative gain or loss over the entire period without converting it to an annual rate. It’s best for short periods (less than one year) or when the time dimension doesn’t matter. For example, if you want to know your total return from a 3-month trade, use HPR—don’t annualize it.
Use our Holding Period Return Calculator for instant calculations.
Arithmetic Mean Formula (For Comparison)
Arithmetic mean is the simple average: add up all returns and divide by the number of periods. While easy to calculate, it should be avoided for measuring realized multi-period compounded growth. It’s useful for expected one-period return modeling and forward-looking probability distributions, but not for measuring what actually happened to your wealth over multiple years.
The arithmetic mean is commonly misused in performance reporting because it produces higher—and more impressive-looking—numbers than geometric mean or CAGR. But those higher numbers are misleading: they don’t reflect the compounding reality of wealth accumulation.
CAGR vs Average Annual Return (Arithmetic vs Geometric)
This is where most investors get confused. Why do arithmetic mean and geometric mean produce different results for the same set of returns? The answer lies in volatility drag—the mathematical reality that compounding amplifies losses more than gains.
When you compound returns, each percentage applies to the balance left by the previous period. A 10% gain followed by a 10% loss does not leave you at breakeven—you end up with a 1% loss. Without interim cash flows, reversing the order of a given set of returns changes the path but not the ending wealth.
The gap between arithmetic and geometric mean is approximately:
Rgeometric ≈ Rarithmetic – (0.5 × σ2)
Where σ2 is the variance of returns (not standard deviation). Under this small-return approximation, greater variance implies a larger gap between the two means.
Note: This approximation works best for small returns expressed as decimals, and assumes returns share the same periodicity. For large or non-normal returns, the gap may differ.
For comparable small-return distributions with the same arithmetic mean, this approximation suggests that greater variance generally reduces the geometric mean. Higher variance alone does not order geometric means across arbitrary return distributions; distribution shape and higher moments also matter.
The Classic Example: +50% / -50% Returns
Start with $100, gain 50% in Year 1, then lose 50% in Year 2.
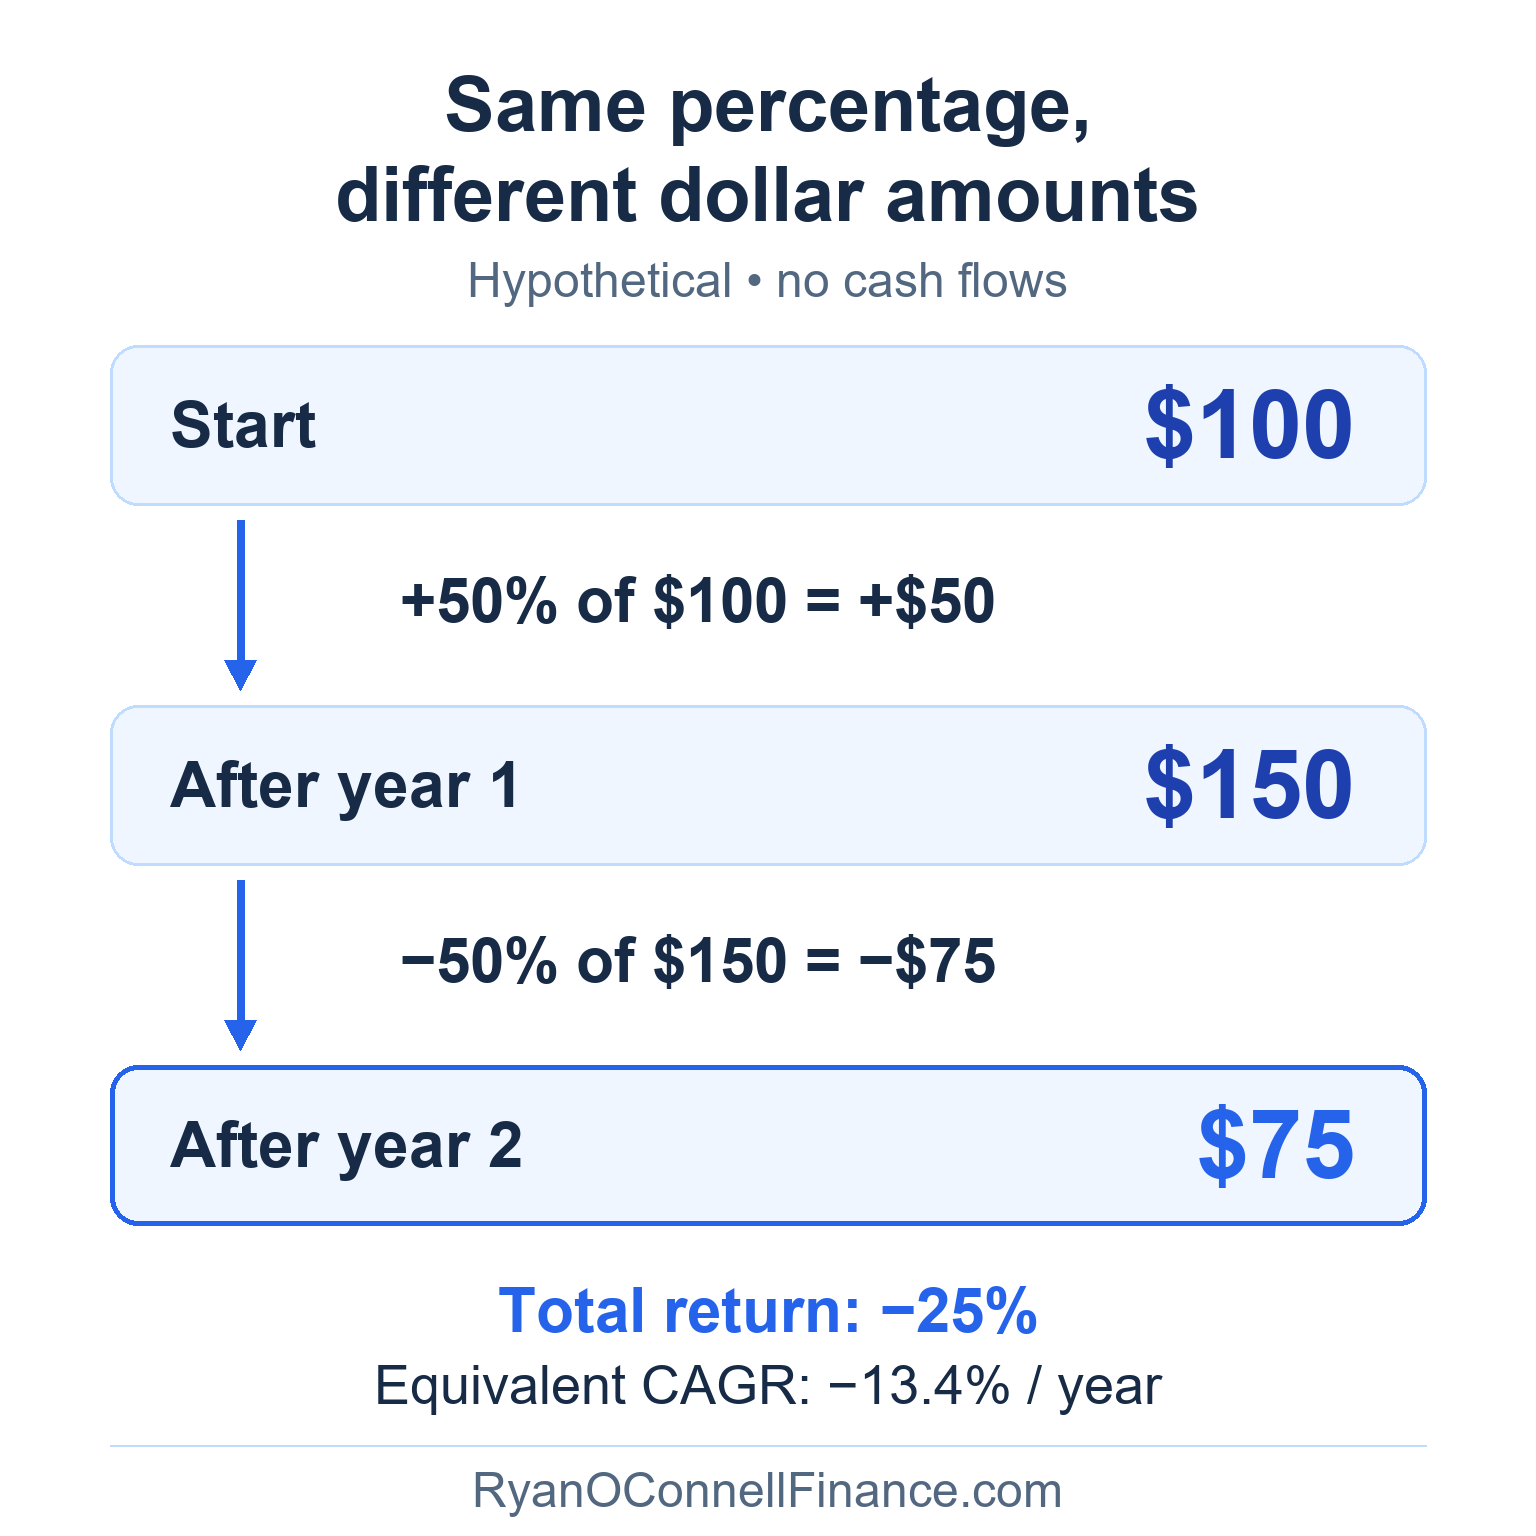
The arithmetic mean is 0%, but the investment loses 25% overall. Its equivalent constant annual rate is (0.75)1/2 – 1 = -13.4%. That CAGR matches the ending wealth; it does not describe the return earned in either individual year.
Use standard deviation alongside the realized compounded return. For comparable small-return distributions, the variance approximation helps explain the arithmetic/geometric gap; calculate the actual product of growth factors when measuring a specific investment path.
For a deeper exploration of volatility and its impact on portfolio outcomes, see our guide on Standard Deviation in Finance.
How to Annualize Monthly, Quarterly, and Daily Returns
One of the most common questions about annualized returns is how to convert shorter-period returns (monthly, quarterly, daily) into annual rates. The general formula handles all frequencies.
Common frequency conversions:
- Monthly → Annual: m = 12 → (1 + Rmonthly)12 – 1
- Quarterly → Annual: m = 4 → (1 + Rquarterly)4 – 1
- Daily → Annual: m = 252 → (1 + Rdaily)252 – 1 (252 trading days)
- Weekly → Annual: m = 52 → (1 + Rweekly)52 – 1
A mutual fund returns 1.5% in a single month. If we annualize this (assuming consistent performance):
Annualized return = (1.015)12 – 1 = 19.6%
Warning: This calculation assumes the 1.5% monthly return persists for 12 consecutive months, which is unrealistic. Only annualize returns measured over meaningful periods (at least 3-6 months).
The formula above works for a single-period return. When you have multiple monthly observations with varying returns, the method you use matters. See the dedicated section on Annualizing Monthly Returns: Simple vs Log Methods below for a detailed comparison of the two standard approaches, including a worked example and guidance on when to use each.
When Cash Flows Complicate Matters
CAGR assumes no contributions or withdrawals during the measurement period. If you’re adding money to your portfolio regularly—such as monthly retirement contributions—CAGR will overstate your personal return because it treats added capital as investment gains.
Use Time-Weighted Return (TWR) to measure manager skill independent of cash flows, or Money-Weighted Return (MWR/IRR) to measure your dollar-weighted personal experience. TWR removes the timing impact of deposits and withdrawals, while MWR reflects how much your actual dollars grew given when you added or removed capital.
Nominal vs Real Returns
All returns discussed in this article are nominal (not adjusted for inflation). To calculate real annualized return, use: (1 + Nominal) / (1 + Inflation) – 1, compounded annually. For example, if your portfolio earned a 10% CAGR and inflation averaged 3%, your real CAGR is approximately (1.10 / 1.03) – 1 = 6.8%.
Annualizing Monthly Returns: Simple vs Log Methods
When working with monthly return data — the most common frequency in portfolio analysis — two distinct workflows produce annualized figures: the simple return approach and the log return approach. Both yield the same annualized result when applied correctly, but they differ in mathematical properties that matter for different analytical tasks.
Simple Return Method (Product Form)
Simple returns measure the straightforward percentage change in price each period. To annualize from monthly data when returns vary month to month, compound each month’s return using the product of growth factors:
When n = 12 (a full year of monthly observations), the exponent becomes 1 and the formula simplifies to the product of all 12 growth factors minus one. For fewer than 12 months, the 12/n exponent scales the cumulative return to an annual basis:
Simple returns have one critical property for portfolio analysis: they are additive across portfolio weights within the same period. A portfolio’s return in a given month equals the weighted sum of its component returns (using start-of-period weights). This makes simple returns the natural choice for cross-sectional portfolio performance attribution.
You may see the formula (1 + R̄monthly)12 – 1 used as a shortcut. This is only exact if R̄ is the geometric mean of monthly returns (or if all monthly returns are identical). If R̄ is the arithmetic mean, this shortcut overstates the true annualized return due to volatility drag. Always use the product form above for variable monthly data.
Log Return Method
Log returns (also called continuously compounded returns) express returns in logarithmic space. The workflow converts simple returns to log returns, aggregates by summation, then converts back:
Log returns are additive across time: the multi-period log return is the sum of single-period log returns. This makes them the preferred representation in quantitative finance and time-series modeling, where compounding consistency simplifies statistical analysis. They are used extensively in options pricing (Black-Scholes assumes log-normally distributed prices) and risk modeling.
Simple Returns
- Additive across assets (portfolio weights, same period)
- Intuitive percentage interpretation
- Used in portfolio attribution and performance reports
- Annualize by compounding growth factors (product form)
- Cannot be directly summed across time
Log Returns
- Additive across time (compounding-consistent)
- Preferred in academic and quantitative research
- Used in options pricing and risk modeling
- Annualize by summing, scaling, then converting back
- Requires R > -100% (undefined for total loss)
Both methods produce the same annualized return when applied correctly. The product of simple growth factors equals the exponentiated sum of log returns: ∏(1 + Rt) = eΣrt. Choose the method that fits your analytical workflow — simple returns for portfolio-level analysis, log returns for time-series analysis.
Worked Example: Six Illustrative Monthly Returns
Illustrative returns for six consecutive months (hypothetical inputs, not verified historical index performance):
| Month | Simple Return | Growth Factor | Log Return |
|---|---|---|---|
| January | +6.28% | 1.0628 | +0.0609 |
| February | -2.44% | 0.9756 | -0.0247 |
| March | +3.67% | 1.0367 | +0.0360 |
| April | +1.56% | 1.0156 | +0.0155 |
| May | +0.43% | 1.0043 | +0.0043 |
| June | +6.61% | 1.0661 | +0.0640 |
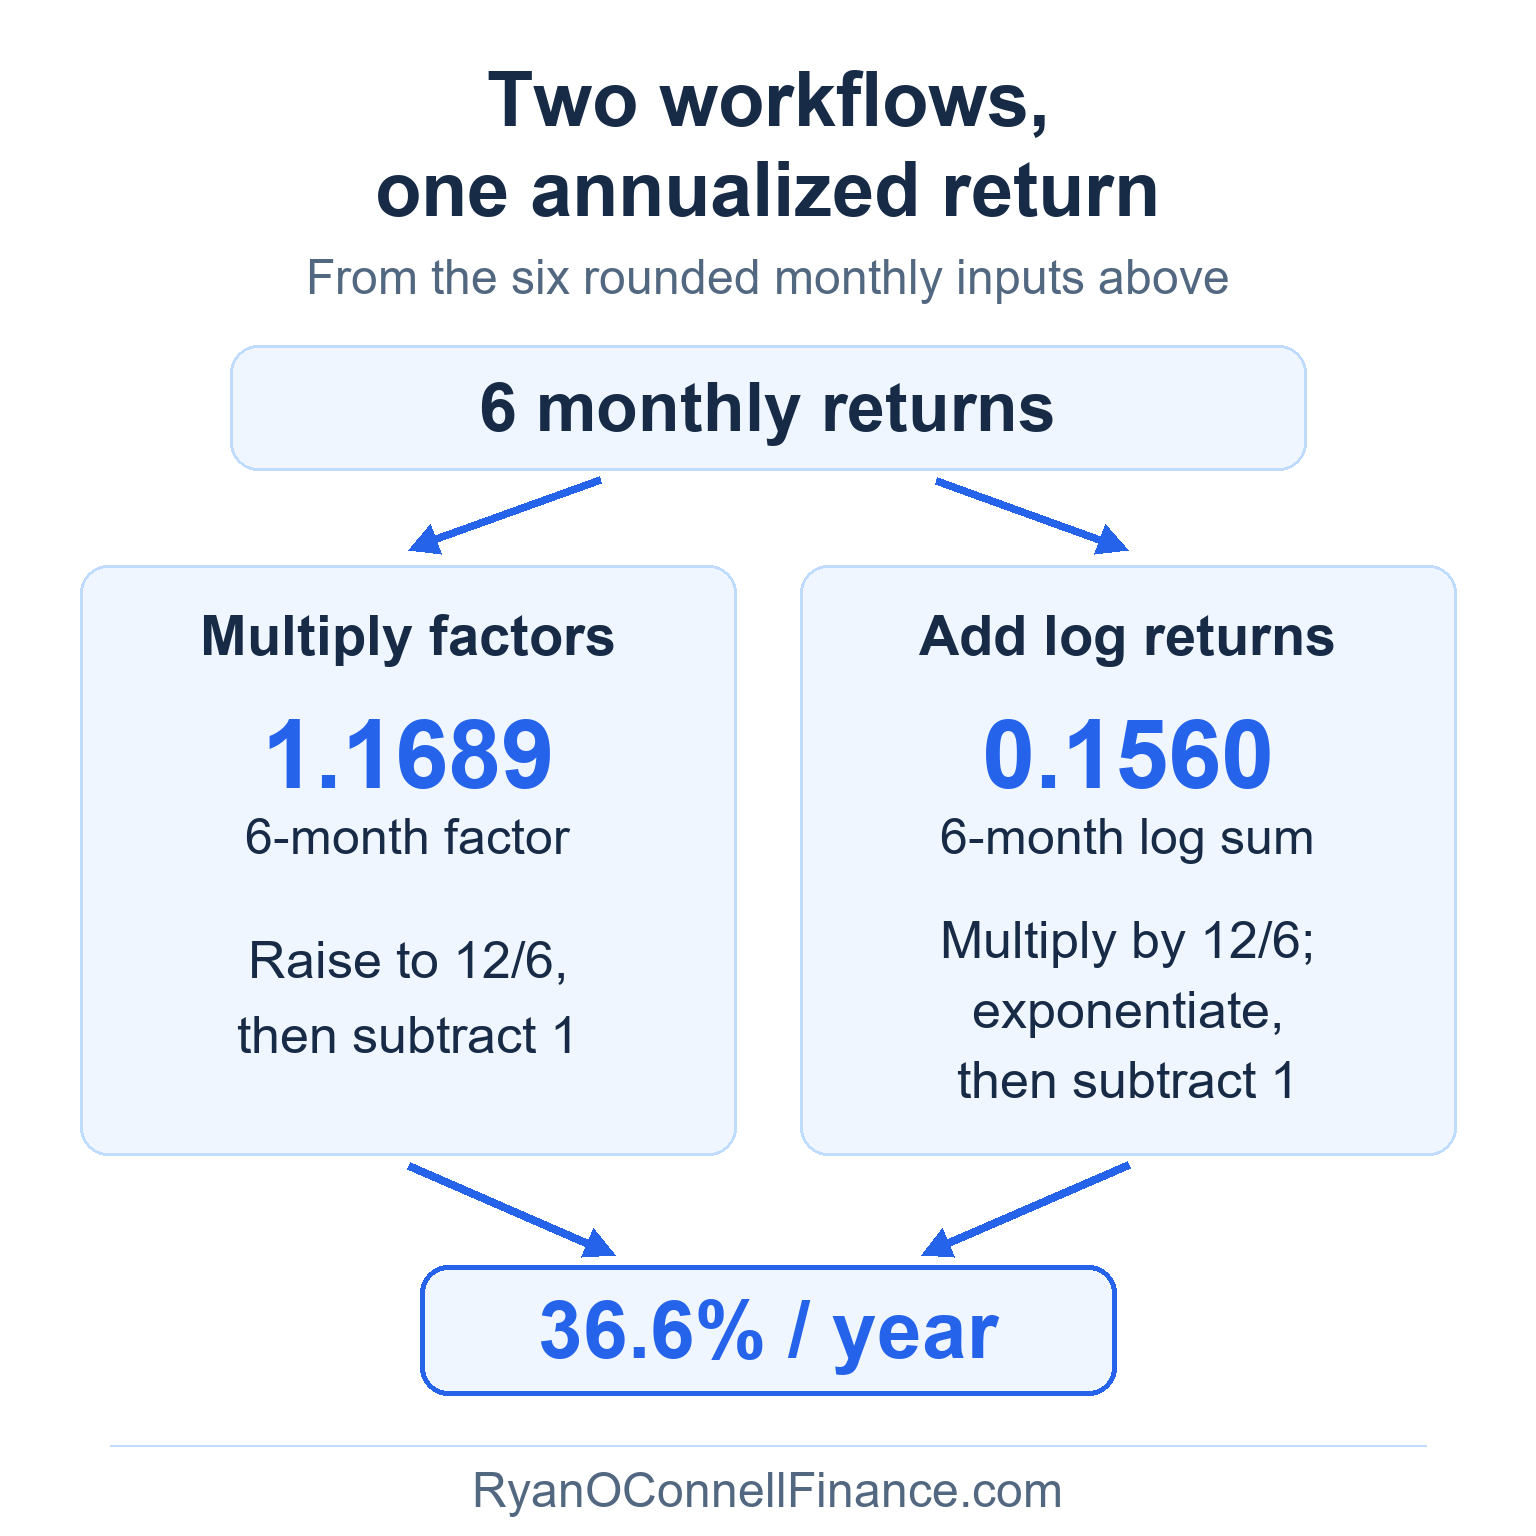
The six-month holding period return is 16.9%. Both workflows scale the measurement period by 12/6 = 2 and produce 36.6% annualized, using unrounded intermediate calculations. This annualization is not a forecast of the next six months.
A frequent error is to compute the arithmetic mean of monthly returns and then compound it: (1 + R̄)12 – 1. In this example, the arithmetic mean is 2.685% per month, giving (1.02685)12 – 1 = 37.4%. This overstates the true annualized return of 36.6% because it ignores the compounding drag from volatility. Always use the product of growth factors or the sum of log returns — never the arithmetic mean as a shortcut for realized returns.
When computing annualized returns from monthly data, use a total return series (adjusted close prices that include dividends and distributions) rather than price-only data. Omitting dividends can understate equity index returns by 1-2% per year. Ensure all monthly observations use consistent frequency — mixing monthly and daily data in the same calculation produces incorrect results.
Annualizing Standard Deviation
Just as returns must be annualized for meaningful comparison, so must volatility. Standard deviation measured at monthly or daily frequency must be scaled to an annual basis for cross-asset comparison and risk reporting.
Common conversions:
- Monthly → Annual: σannual = σmonthly × √12 (≈ × 3.464)
- Daily → Annual: σannual = σdaily × √252 (≈ × 15.875)
If the S&P 500 has a monthly standard deviation of 4.5%:
σannual = 4.5% × √12 = 4.5% × 3.464 = 15.6%
This 15.6% annualized volatility is the figure you would see in risk reports and use in calculations like the Sharpe ratio.
The square-root-of-time rule assumes that returns are independent and identically distributed (i.i.d.) across periods — meaning each month’s return is uncorrelated with the next. In practice, this assumption is often violated:
- Positive autocorrelation (momentum) causes √T scaling to understate true annual risk — consecutive moves in the same direction compound more than the formula predicts
- Negative autocorrelation (mean-reversion) causes √T scaling to overstate true annual risk — reversals dampen long-horizon volatility
- Volatility clustering (calm periods followed by turbulent periods) further violates the i.i.d. assumption
Despite these limitations, √T scaling is the standard approach in practice because it is simple, transparent, and reasonably accurate for most liquid assets. For a deeper treatment of volatility measurement and its limitations, see our guide on Standard Deviation in Finance.
When to Use Each Return Metric
CAGR (Compound Annual Growth Rate)
- Formula: [(Ending Value / Beginning Value)1/n] – 1
- When to use: Measuring growth rate when you have only beginning and ending values
- Pros: Simple to calculate, smooths out volatility, easy to compare across time periods and investments
- Cons: Hides interim volatility and drawdowns; backward-looking
- Best for: Fund performance reports, long-term investment comparisons, headline performance numbers
- To evaluate CAGR alongside risk, pair it with the Sharpe ratio, which measures risk-adjusted returns
Arithmetic Mean Return
- Formula: (R1 + R2 + … + Rn) / n
- When to use: Expected one-period return modeling and probability distributions
- Pros: Easy to calculate, useful in statistics and forecasting
- Cons: OVERSTATES realized compounded growth
- Best for: Forward-looking single-period estimates, not realized multi-period measurement
- Warning: Avoid for measuring actual multi-year performance—it ignores compounding effects
Geometric Mean Return
- Formula: [(1+R1) × (1+R2) × … × (1+Rn)]1/n – 1
- When to use: Measuring actual compounded growth when you have period-by-period returns
- Pros: Accurate for compounded growth, accounts for volatility drag, equals CAGR when the input returns are annual
- Cons: More complex to calculate than arithmetic mean; always ≤ arithmetic mean
- Best for: Academic analysis, performance attribution, volatility-aware return measurement
- When comparing multi-period performance across investments, geometric mean prevents overstating growth from volatile returns
Real-World Example: S&P 500 (2018-2022)
Let’s apply these concepts to real data: the S&P 500 Total Return Index over a volatile 5-year period that includes both strong bull market years and a significant bear market correction.
Annual Returns (S&P 500 Total Return data, approximate):
- 2018: -4.38% (market correction)
- 2019: +31.49% (strong recovery)
- 2020: +18.40% (COVID recovery after March drawdown)
- 2021: +28.71% (continued bull market)
- 2022: -18.11% (inflation/rate-driven bear market)
Starting Investment: $10,000 (January 1, 2018)
Ending Value: $15,690 (December 31, 2022)
Calculations:
1. Arithmetic Mean: (-4.38 + 31.49 + 18.40 + 28.71 – 18.11) / 5 = 11.22% per year
2. Geometric Mean: [(0.9562) × (1.3149) × (1.1840) × (1.2871) × (0.8189)]0.2 – 1 = 9.43% per year
3. CAGR: [($15,690 / $10,000)1/5] – 1 = 9.43% per year
4. Holding Period Return: ($15,690 – $10,000) / $10,000 = 56.90% total
| Metric | Result | What It Tells You |
|---|---|---|
| Arithmetic Mean | 11.22% per year | OVERSTATES actual growth |
| Geometric Mean | 9.43% per year | True compounded growth |
| CAGR | 9.43% per year | Same as geometric (as expected) |
| Holding Period Return | 56.90% total | Total 5-year gain |
| Volatility Drag | 1.79 percentage points per year | Cost of volatility |
Interpretation: An investor who put $10,000 into an S&P 500 index fund on January 1, 2018, would have approximately $15,690 by December 31, 2022. The arithmetic mean of 11.22% makes it sound like you averaged strong double-digit returns, but that overstates reality. The geometric mean and CAGR both correctly show 9.43% compounded annual growth. The 1.79 percentage point gap is volatility drag—the price of year-to-year swings, including the sharp -18.11% loss in 2022.
How to Calculate Annualized Returns
Follow these five steps to calculate annualized returns correctly:
- Identify your data: Do you have beginning and ending values only, or do you have period-by-period returns?
- Choose the right formula: Use CAGR for beginning/ending values; use geometric mean for period returns
- Match the time period: Ensure your measurement window is in years (or convert it: 30 months = 2.5 years)
- Apply the formula: Execute the calculation using the appropriate formula above
- Interpret in context: Compare your result to a relevant benchmark (e.g., S&P 500) or the risk-free rate
Use at least 3-5 years of data for meaningful CAGR analysis. Shorter periods amplify noise and can produce misleading snapshots of performance. A fund with 25% returns over one year might have 5% CAGR over ten years—the longer window gives you the real story.
For a comprehensive walkthrough of performance evaluation techniques, see our Portfolio Analytics & Risk Management course, which covers return measurement, risk metrics, and portfolio analysis in depth.
Common Mistakes with Annualized Returns
Avoid these seven common errors when calculating and interpreting annualized returns:
1. Using Arithmetic Mean for Multi-Year Returns
The mistake: “My portfolio returned 10%, 5%, and -3% over three years, so my average return is 4% per year.”
Why it’s wrong: Arithmetic mean ignores compounding. It overstates actual growth.
The correct approach: Use geometric mean: [(1.10) × (1.05) × (0.97)]1/3 – 1 = 3.86% per year.
Real-world impact: Over 20 years, the difference between 4% and 3.86% compounds to a 3% difference in ending wealth.
2. Ignoring the Compounding Effect
The mistake: Assuming a +10% return followed by a -10% return leaves you at breakeven.
Why it’s wrong: $100 → $110 → $99. You lost 1%.
The correct approach: Use geometric mean: [(1.10) × (0.90)]1/2 – 1 = -0.50% per year.
Real-world impact: Equal percentage gains and losses do not cancel. Without interim cash flows, the order of a given set of returns changes the path but not the ending wealth; with contributions or withdrawals, sequence can also affect the ending value.
3. Annualizing Short Periods
The mistake: “My fund returned 5% in January, so it’s on track for 60% annual returns!”
Why it’s wrong: Short periods amplify noise and assume unrealistic persistence. One month of data tells you almost nothing about sustainable annual performance.
The correct approach: While annualizing short periods is mathematically valid, it’s generally unhelpful for decision-making. Avoid annualizing periods shorter than 3-6 months—the results are often unstable and misleading. For periods under one year, consider reporting the holding period return to avoid overstating performance expectations.
Real-world impact: This mistake leads to wild overestimates and poor investment decisions based on short-term noise. See Maximum Drawdown for more on volatility over time.
4. Comparing CAGR Across Different Time Periods
The mistake: Comparing Fund A’s 3-year CAGR to Fund B’s 5-year CAGR.
Why it’s wrong: Different measurement windows capture different market environments.
The correct approach: Always compare returns over the same evaluation period.
Real-world impact: Misleading performance comparisons that favor funds measured during bull markets.
5. Forgetting About Fees and Taxes
The mistake: Calculating CAGR on gross returns without accounting for expense ratios or taxes.
Why it’s wrong: Investors earn net returns, not gross returns.
The correct approach: Use after-fee, after-tax returns for personal wealth analysis.
Real-world impact: A 1% annual fee reduces a 10% CAGR to 9%, which compounds to 17% less wealth over 20 years.
6. Mixing Price Return vs Total Return
The mistake: Comparing a price-only index CAGR to a total return (including dividends) CAGR.
Why it’s wrong: Dividends can add 1-2% per year—omitting them understates actual investor experience.
The correct approach: Always specify whether returns include dividends or distributions.
Real-world impact: The S&P 500 price return (2018-2022) is approximately 7%, but total return is approximately 9.4%—a massive difference.
7. Mixing Gross, Net-of-Fee, and After-Tax Returns
The mistake: Comparing Fund A’s gross return to Fund B’s net-of-fee return.
Why it’s wrong: Different return types aren’t comparable.
The correct approach: Always compare apples-to-apples (gross-to-gross, net-to-net, after-tax-to-after-tax).
Real-world impact: A 0.5% expense ratio difference can flip a winning fund into a losing one over long periods.
Limitations of CAGR and Annualized Returns
CAGR is a powerful tool, but it has important limitations every investor should understand:
1. CAGR Smooths Over Volatility
CAGR shows only the endpoint—it hides the path your investment took to get there. Two hypothetical investments can both earn an 8% CAGR over four years: one earns 8% each year, while the other alternates +40% and approximately -16.69%.
| Elapsed time (years) | Volatile (USD) | Steady 8% (USD) |
|---|---|---|
| 0 | 10000.00 | 10000.00 |
| 1 | 14000.00 | 10800.00 |
| 2 | 11664.00 | 11664.00 |
| 3 | 16329.60 | 12597.12 |
| 4 | 13604.89 | 13604.89 |
Hypothetical; no cash flows. The volatile path alternates +40% and approximately -16.69%; values are calculated before rounding to cents.
Both $10,000 investments finish at about $13,605 after four years. The volatile path falls about 16.7% in Years 2 and 4, losses that its 8% CAGR alone does not reveal.
Use CAGR alongside standard deviation or maximum drawdown to understand the volatility you endured. The Sharpe ratio combines return and volatility into a single risk-adjusted metric.
2. Backward-Looking Measurement
CAGR tells you what happened, not what will happen. A fund with 15% CAGR over the last decade may not repeat that performance in the next decade. Market conditions, economic cycles, and management changes all affect future returns.
Past performance does not guarantee future results. Don’t extrapolate CAGR into the future without considering changing fundamentals.
3. Sensitive to Start and End Dates
CAGR depends heavily on when you start and stop measuring. Measuring the S&P 500 CAGR from a market peak (like 2007) vs. a trough (like 2009) yields very different results, even if the end date is the same. Comparing rolling returns across equal-length windows helps expose that start-date dependence, while overlapping windows require careful interpretation.
Use consistent, meaningful measurement periods. Full market cycles (peak-to-peak or trough-to-trough) give you the most representative picture.
4. Ignores Cash Flows
CAGR assumes no contributions or withdrawals during the period. If you added $5,000 halfway through the measurement window, CAGR will overstate your actual growth rate because it treats that $5,000 as investment gains.
For portfolios with cash flows, use time-weighted return (TWR) or money-weighted return (MWR/IRR). See our guide on Time-Weighted vs Money-Weighted Returns for when to use each.
CAGR is a powerful tool, but it should never be your only metric. Combine it with volatility measures (like standard deviation), risk-adjusted metrics (like Sharpe ratio), and downside risk metrics (like maximum drawdown) for a complete picture of investment performance.
Frequently Asked Questions
Disclaimer
This article is for educational and informational purposes only and does not constitute investment advice. Return data cited are approximate and may differ based on data source and methodology. Always conduct your own research and consult a qualified financial advisor before making investment decisions.
Keep reading
Next in this series
Part 15 of 20 in Portfolio Analytics
Systematic vs Unsystematic Risk: What’s the Difference?More in Portfolio Management
-
Investment Policy Statement & RRTTLLU Framework: Complete Guide
Learn what an investment policy statement (IPS) is, how to write one using the RRTTLLU framework, and why it is the cornerstone of the portfolio management…
-
Portfolio Rebalancing: Strategies, Costs, and Best Practices
Learn when and how to rebalance your portfolio, compare calendar vs threshold strategies, and understand the real costs of rebalancing.
-
Financial Leverage in Investing: How to Amplify Returns (and Losses)
Learn how financial leverage amplifies portfolio returns and losses, how to measure leverage ratio, and the risks of using borrowed capital to invest.


