
Time-Weighted vs Money-Weighted Return: Key Differences Explained

Table of Contents
When measuring investment returns, the method you use can dramatically change the result — even for the same portfolio with the same ending balance. Time-Weighted Return (TWR) and Money-Weighted Return (MWR) answer fundamentally different questions: TWR measures how well the investments performed, while MWR measures how well you did as an investor, including your cash flow timing decisions. Understanding the difference is essential for portfolio evaluation, manager selection, and personal financial planning.
What is Time-Weighted Return?
Time-Weighted Return (TWR) is a method that measures investment performance by eliminating the impact of cash flows. It breaks the total holding period into sub-periods between each cash flow (deposit or withdrawal), calculates the return for each sub-period independently, then geometrically links those returns together.
TWR removes the timing and size of cash flows to isolate the investment manager’s skill. A fund manager with excellent stock picks gets the same TWR regardless of when clients deposit or withdraw money. This makes TWR the fair standard for evaluating and comparing manager performance.
TWR is the industry standard for mutual funds, pension funds, and institutional investors. It’s used by performance measurement systems worldwide and is typically required by the Global Investment Performance Standards (GIPS) for most public-market composites. When combined with risk metrics like the Sharpe ratio and Jensen’s alpha, TWR provides a complete picture of risk-adjusted manager skill.
What is Money-Weighted Return (IRR)?
Money-Weighted Return (MWR), also called Internal Rate of Return (IRR), measures the actual return experienced by the investor, fully accounting for the timing and size of cash flows. MWR solves for the rate that makes the net present value of all investor cash flows, including the initial investment, subsequent deposits and withdrawals, and the terminal portfolio value, equal to zero.
MWR captures your actual investor experience. If you invested a large sum right before a market crash, your MWR will be lower than TWR even though the portfolio’s investment performance didn’t change. Conversely, if you withdrew funds before a downturn, your MWR will be higher than TWR.
MWR is widely used in private equity, real estate investing, personal financial planning, and capital budgeting. It tells you whether your cash flow timing decisions helped or hurt your overall returns. When MWR is reported as an annualized return, it can be compared with other annualized investment returns; a periodic IRR must first be converted to the same annual basis.
Time-Weighted Return vs Money-Weighted Return: Key Differences
TWR and MWR are not “better” or “worse” — they answer different questions. TWR asks: “How well did the investments perform?” MWR asks: “How well did I do as an investor, including my cash flow timing decisions?” The same portfolio can produce dramatically different results depending on which method you use.
| Aspect | Time-Weighted Return (TWR) | Money-Weighted Return (MWR) |
|---|---|---|
| What it measures | Investment performance only | Investor experience with timing |
| Cash flow impact | Removed (neutralized) | Included (dollar-weighted) |
| Best for | Evaluating fund managers | Personal portfolio assessment |
| Industry use | Mutual funds, GIPS composites | Private equity, financial planning |
| Also known as | Geometric return | Internal Rate of Return (IRR) |
The Time-Weighted Return Formula
TWR is calculated by geometrically linking the returns of each sub-period between cash flows. Here are the two key formulas:
The key insight is that TWR breaks the measurement period at each cash flow, creating clean sub-periods. Each sub-period’s return is calculated independently, then geometrically linked. This neutralizes the timing effect — whether a $10,000 deposit happened in Period 1 or Period 2 doesn’t affect the TWR, because each period is measured separately. By geometrically linking these sub-period returns, TWR isolates the portfolio’s actual investment performance from the investor’s deposit and withdrawal decisions.
Note on cash flow sign conventions: In TWR calculations, deposits are treated as positive (they increase portfolio value) and withdrawals as negative. This differs from IRR/MWR convention where deposits are negative (cash out of pocket) and withdrawals are positive (cash back to you). Both conventions are correct for their respective methods.
The Money-Weighted Return Formula
MWR is found by solving for the discount rate that makes the Net Present Value (NPV) of all cash flows equal to zero:
Sign convention: Initial investment and deposits are negative (cash outflows), while withdrawals and the ending value are positive (cash inflows). General cash-flow patterns usually require numerical solution using a financial calculator or Excel. Some simple cases, including the two-year example below, also admit an algebraic solution.
For dated cash flows, Excel’s XIRR() returns an annualized MWR. With an initial investment on January 1, 2023, a withdrawal on January 1, 2024, and the ending value on January 1, 2025, use =XIRR({-100000,60000,35000},CHOOSE({1,2,3},DATE(2023,1,1),DATE(2024,1,1),DATE(2025,1,1))), which returns approximately -3.7% per year. XIRR uses actual days, so it differs slightly from the equal-year IRR calculated below.
In rare cases with non-conventional cash flow signs (e.g., alternating large deposits and withdrawals), the IRR equation may have multiple solutions or no real solution. Most typical investment scenarios (initial deposit + periodic contributions + final withdrawal) have a unique IRR. Always sanity-check IRR results against expected market returns.
In practice, portfolio accounting systems may use Modified Dietz approximations for faster daily return calculations, then reconcile to precise XIRR periodically. For most individual investors, Excel’s XIRR with actual transaction dates is the gold standard for calculating MWR.
TWR vs MWR: A Real Example
Consider a hypothetical portfolio with a single cash flow between two annual periods. The same portfolio produces different TWR and MWR results:
Suppose you invest $100,000 at the start of Year 1. The portfolio earns 10% that year, you withdraw $60,000 at year-end, and the remaining investment loses 30% in Year 2. How does withdrawing before the loss change the money exposed to it?
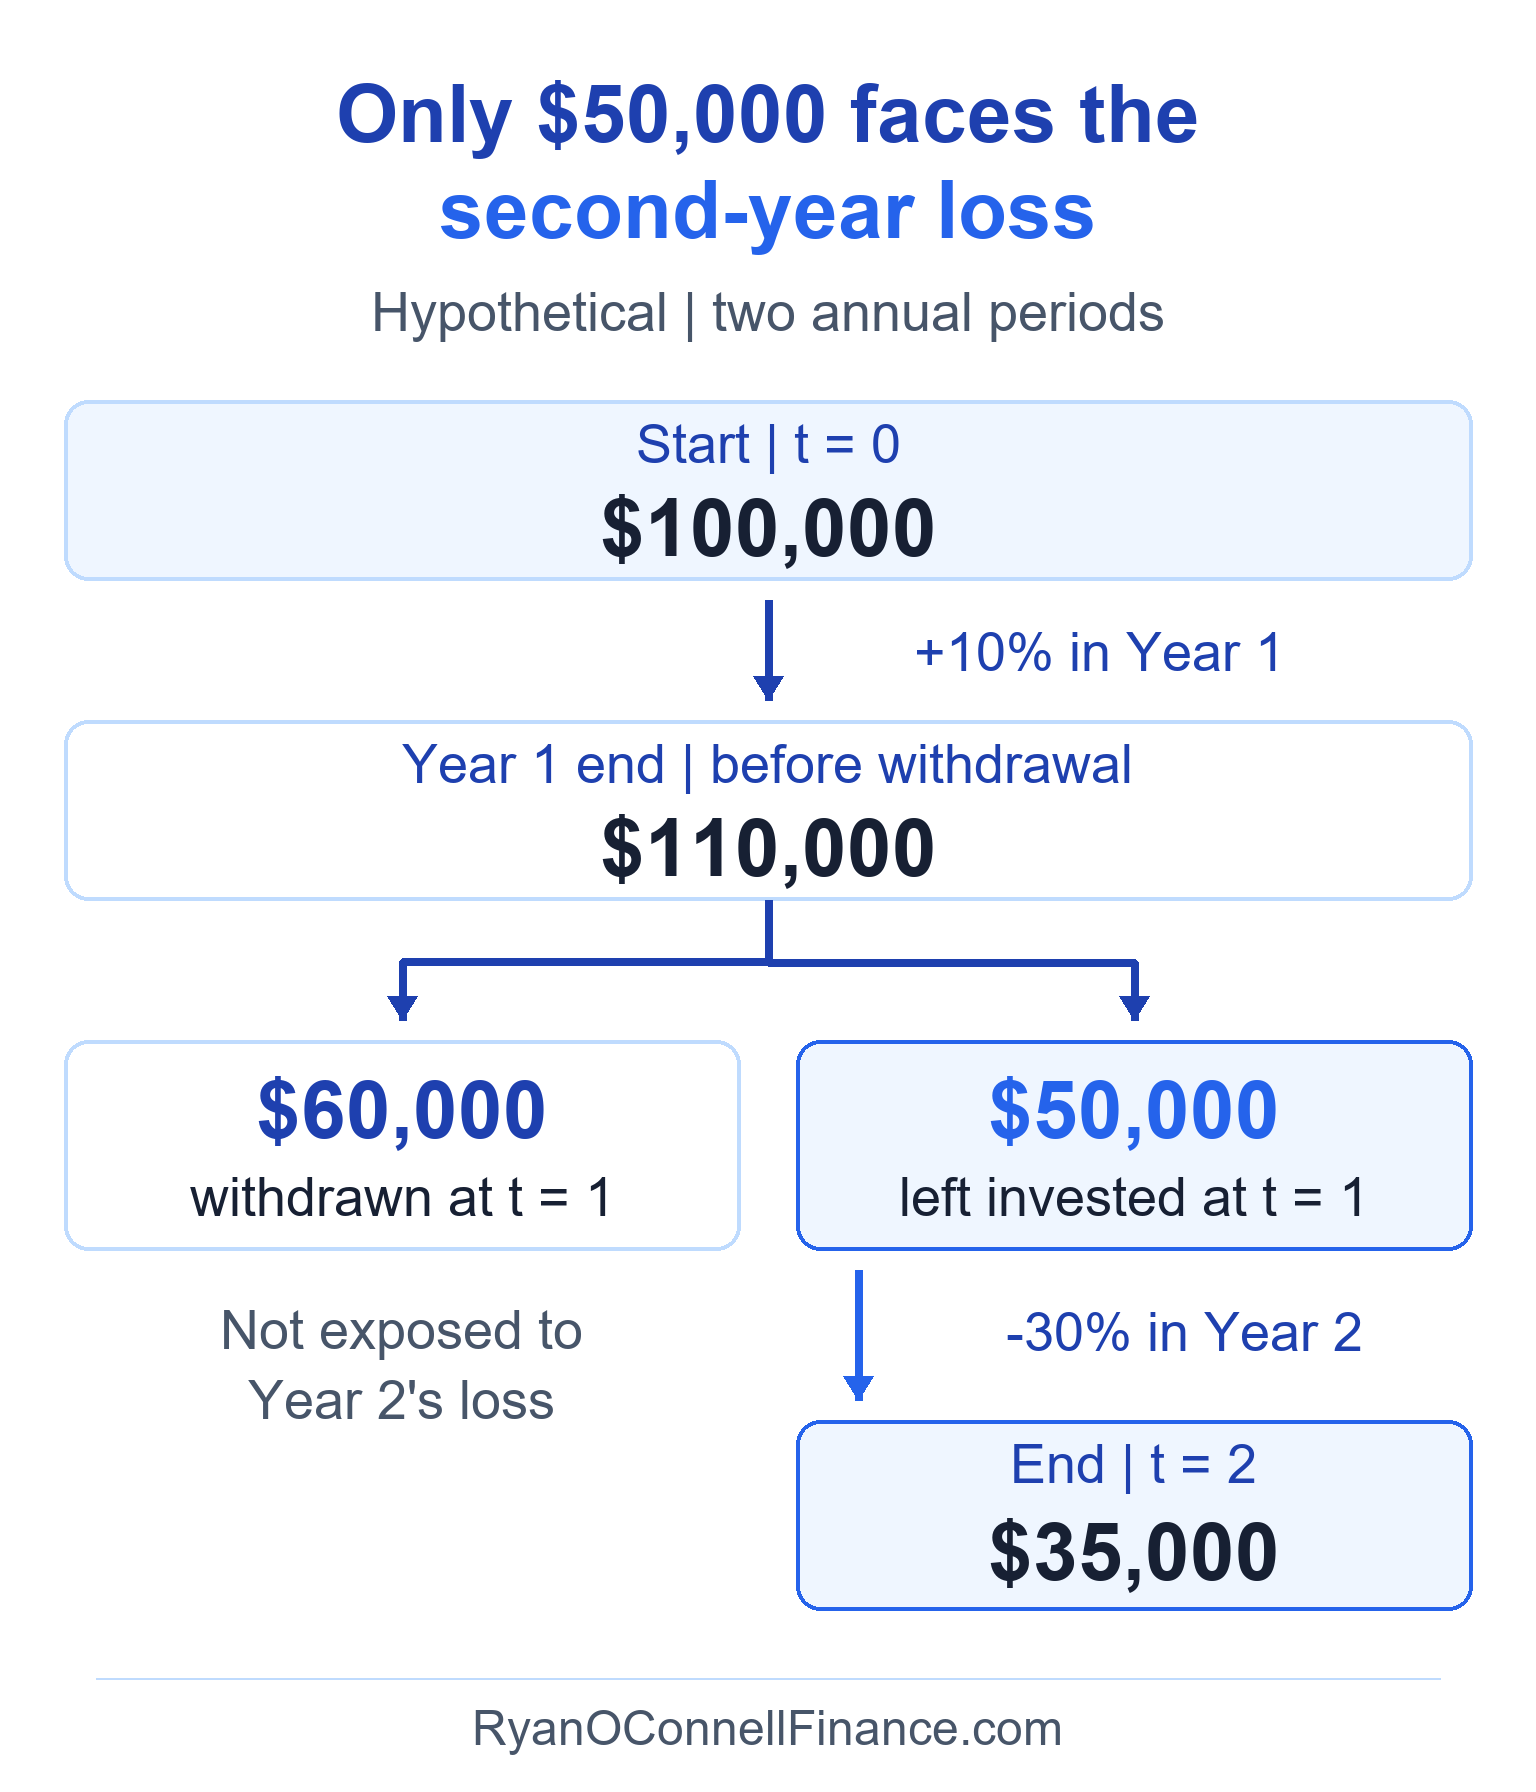
The withdrawal reduces the balance from $110,000 to $50,000; Year 2’s 30% loss therefore applies only to the $50,000 still invested.
Time-Weighted Return Calculation
Year 1 return: R1 = ($110,000 – $100,000) / $100,000 = +10%
Year 2 return: R2 = ($35,000 – $50,000) / $50,000 = -30%
TWR = [(1 + 0.10) × (1 – 0.30)] – 1 = [1.10 × 0.70] – 1 = 0.77 – 1 = -23% total return
Annualized TWR = (0.77)1/2 – 1 = -12.3% per year
Money-Weighted Return Calculation
Cash flows (sign convention):
- t=0: -$100,000 (initial investment, negative)
- t=1: +$60,000 (withdrawal, positive)
- t=2: +$35,000 (ending value, positive)
IRR equation: 0 = -100,000 + 60,000/(1+MWR) + 35,000/(1+MWR)2
Solving the equal-year IRR equation: MWR ≈ -3.7% per year
| Return method | Annualized return (%) |
|---|---|
| TWR | -12.3 |
| MWR | -3.7 |
Hypothetical; two equal one-year periods. Fees and returns on cash after it leaves the portfolio are not modeled.
Annualized MWR is -3.7%, compared with -12.3% for TWR—a difference of 8.6 percentage points. The $60,000 withdrawal left just $50,000 exposed to Year 2’s 30% loss, so the investor’s money-weighted result is less negative.
TWR vs MWR: When to Use Each
Choosing between TWR and MWR depends on what question you’re trying to answer. Here’s when to use each method:
Time-Weighted Return (TWR)
Decision Rules:
- ✅ Use TWR when: Evaluating fund managers or investment advisors
- ✅ Use TWR when: Comparing performance across different funds or strategies
- ✅ Use TWR when: You need GIPS-compliant reporting (most public-market composites)
Why It Matters:
- Removes impact of client deposits/withdrawals that managers don’t control
- Fair comparison of manager skill across different funds
- Industry standard for mutual funds, pension funds, institutional investors
Example Use Case: “Which fund manager picked better stocks over the past 5 years?”
Money-Weighted Return (MWR / IRR)
Decision Rules:
- ✅ Use MWR when: Evaluating your personal investment experience
- ✅ Use MWR when: Analyzing private equity or real estate investments
- ✅ Use MWR when: The manager controls external cash flows (e.g., closed-end funds, certain private markets)
Why It Matters:
- Captures the actual dollar-weighted return you experienced
- Includes timing and size of all your deposits and withdrawals
- Tells you if your market timing decisions helped or hurt
Example Use Case: “Did my 401(k) contributions over the past decade produce good returns given when I added money?”
TWR and MWR answer different questions, and neither is inherently “better.” The key decision: Are you evaluating someone else’s skill (use TWR) or your own results including timing decisions (use MWR)? Note that GIPS typically requires TWR for public-market manager composites, but allows MWR in specific cases where managers control external cash flows (e.g., certain private equity or closed-end structures).
How to Calculate TWR and MWR
Here are the practical steps for calculating each method:
Time-Weighted Return
- Identify all cash flow dates — Note every deposit and withdrawal with exact dates
- Split the period into sub-periods — Create a sub-period between each cash flow
- Calculate each sub-period return — Use (value just before the next flow / value just after the previous flow) – 1, with no external cash flow inside the sub-period
- Geometrically link the returns — Multiply: (1 + R1) × (1 + R2) × … – 1
- Annualize if needed — Use: [(1 + TWR)1/years] – 1
Money-Weighted Return
- List all cash flows with dates — Deposits are negative, withdrawals are positive
- Include beginning value — Add as negative cash flow at t=0
- Include ending value — Add as positive cash flow at final date
- Use Excel’s XIRR() function — Or use a financial calculator’s IRR function
- Check the time basis — XIRR is annualized. Standard IRR is per cash-flow period; convert it to an annual rate when those periods are not years
Common Mistakes When Using TWR and MWR
Here are the most frequent errors investors and analysts make when calculating and interpreting these return metrics:
- Using MWR to evaluate fund managers: This penalizes or rewards managers for cash flows they don’t control. If clients deposit money before a crash, the manager looks bad even if they made excellent investment decisions. Always use TWR for comparing manager skill (this is why GIPS typically requires TWR for most public-market composites).
- Using TWR for personal performance: If you’re evaluating your own portfolio and you control when deposits happen, TWR won’t tell you how well you timed the market. MWR is more relevant for assessing your personal investment experience including your timing decisions.
- Ignoring the difference entirely: Many investors calculate simple return [(ending – beginning) / beginning] and don’t account for mid-period cash flows at all. This is neither TWR nor MWR and can be wildly misleading when you have large deposits or withdrawals during the period.
- Arithmetic averaging instead of geometric linking for TWR: TWR requires multiplying (1+R1)×(1+R2)×… and subtracting 1, not adding R1+R2+…/n. Arithmetic averaging overstates returns when volatility is high and produces mathematically incorrect results.
- Comparing mismatched time bases: Put TWR and MWR on the same annualized basis before examining their gap. An annualized TWR of -5% and MWR of +2% can reflect favorable cash flow timing, such as adding before gains or withdrawing before losses. Neither calculation is uniquely the “true” return; they answer different questions.
- Using inconsistent dates or frequencies in MWR: XIRR requires actual transaction dates. Using approximate monthly intervals instead of precise dates can materially change the IRR result, especially for short holding periods or large cash flows.
- Ignoring possible multiple IRR solutions: With non-conventional cash flow patterns (alternating signs, multiple direction changes), there may be multiple IRR values or no real solution. Always sanity-check IRR results against expected market returns.
- Mixing net-of-fee and gross-of-fee returns: When comparing TWR vs MWR or across managers, ensure you’re using consistent fee treatment. Comparing gross TWR (before fees) to net MWR (after fees) is an apples-to-oranges comparison.
- Mixing total, periodic, and annualized returns: Convert cumulative TWR and any periodic IRR to an annual rate before comparing them with annualized returns. XIRR is already annualized. A 20% total return over 5 years is only 3.7% annualized — a crucial distinction when evaluating performance.
Most brokerage statements show simple dollar gains, not TWR or MWR. You need to calculate these manually using Excel (XIRR for MWR) or dedicated portfolio tracking software. Very few retail platforms auto-calculate true TWR, so don’t assume your statement shows the right metric.
Limitations of TWR and MWR
Both TWR and MWR are backward-looking metrics. They tell you what happened in the past but don’t predict future returns. Historical TWR and MWR can both be misleading if market conditions, portfolio composition, or investment strategy changes going forward.
Time-Weighted Return Limitations
- Ignores investment size: A fund with $1 billion gets the same TWR as one with $1 million, even though managing scale is significantly harder and may constrain available strategies.
- Does not isolate cash flow costs: TWR removes the direct value change from deposits and withdrawals. Trading costs or losses caused by flow-driven liquidations still affect measured investment performance, but TWR alone does not identify their cause.
- Computationally intensive: Requires portfolio valuation at every cash flow date, which is impractical for daily-traded accounts with frequent transactions.
Money-Weighted Return Limitations
- Mixes skill and luck: Can’t separate manager investment skill from cash flow timing luck, making it impossible to isolate what’s repeatable.
- Unfair for external managers: Penalizes managers for client behavior they don’t control (panic selling at bottoms, greed buying at tops).
- Not comparable across portfolios: Two managers can have vastly different MWRs purely due to different client cash flow patterns, not investment skill.
- Sensitive to timing: A single large cash flow at an unlucky time can dominate the entire return calculation and misrepresent the overall experience.
The limitation that matters most depends on your use case. For comparing fund managers, TWR’s complexity is worth it for fairness and comparability. For personal portfolios with infrequent cash flows, MWR’s simplicity and relevance to your actual experience make it the better choice. Regardless of which method you use, combining it with risk metrics like the Sharpe ratio, Treynor ratio, and standard deviation gives a more complete picture of risk-adjusted performance.
Frequently Asked Questions
Disclaimer
This article is for educational and informational purposes only and does not constitute investment advice. TWR and MWR calculations are simplified examples and may differ from actual portfolio accounting methods used by financial institutions. The example scenarios are for illustrative purposes only and do not represent actual investment results. Always conduct your own research and consult a qualified financial advisor before making investment decisions.
Keep reading
Next in this series
Part 14 of 20 in Portfolio Analytics
Annualized Return (CAGR): Formula, Calculation, and ExamplesMore in Portfolio Management
-
Investment Policy Statement & RRTTLLU Framework: Complete Guide
Learn what an investment policy statement (IPS) is, how to write one using the RRTTLLU framework, and why it is the cornerstone of the portfolio management…
-
Systematic vs Unsystematic Risk: What’s the Difference?
Learn the difference between systematic (market) risk and unsystematic (company-specific) risk, why diversification eliminates only one type…
-
Portfolio Rebalancing: Strategies, Costs, and Best Practices
Learn when and how to rebalance your portfolio, compare calendar vs threshold strategies, and understand the real costs of rebalancing.


