Quantity Theory of Money: The Equation of Exchange Explained
Table of Contents
Why does printing money cause inflation? The quantity theory of money provides the most enduring answer in economics. First articulated by David Hume in the 18th century, formalized by Irving Fisher in the early 20th century, and revived as the modern monetarist statement by Milton Friedman, this theory draws a direct line from money supply growth to rising prices. Whether you’re analyzing hyperinflation in Zimbabwe, evaluating Federal Reserve policy, or studying for an economics exam, the quantity theory is the essential framework linking money to inflation.
What Is the Quantity Theory of Money?
The quantity theory of money holds that, with velocity and real output unchanged, the general price level is directly proportional to the quantity of money in circulation. In practical terms, with velocity stable, money supply growth faster than real output growth implies inflation.
The quantity theory of money states that changes in the money supply are the primary driver of changes in the price level. If the money supply doubles while velocity and real output stay the same, prices will double. This is often summarized as “inflation is always and everywhere a monetary phenomenon” (Milton Friedman).
The theory rests on a critical assumption: the velocity of money — how quickly money circulates through the economy — is relatively stable over time. If velocity is stable, then any increase in the money supply beyond what real economic growth absorbs must show up as higher prices.
This framework is considered a long-run theory. In the short run, changes in money supply can affect real output and employment. But over longer horizons, most economists agree that sustained money growth above real GDP growth translates into sustained inflation.
The Equation of Exchange (MV = PY)
The quantity theory is expressed through the equation of exchange, one of the most important identities in monetary economics:
Where:
- M — the money supply (e.g., M2)
- V — the velocity of money (how many times each dollar is spent per year)
- P — the overall price level
- Y — real GDP (the quantity of goods and services produced)
An important distinction: the equation of exchange is an identity — it is true by definition because velocity is defined as V = (P × Y) / M. The quantity theory adds economic assumptions:
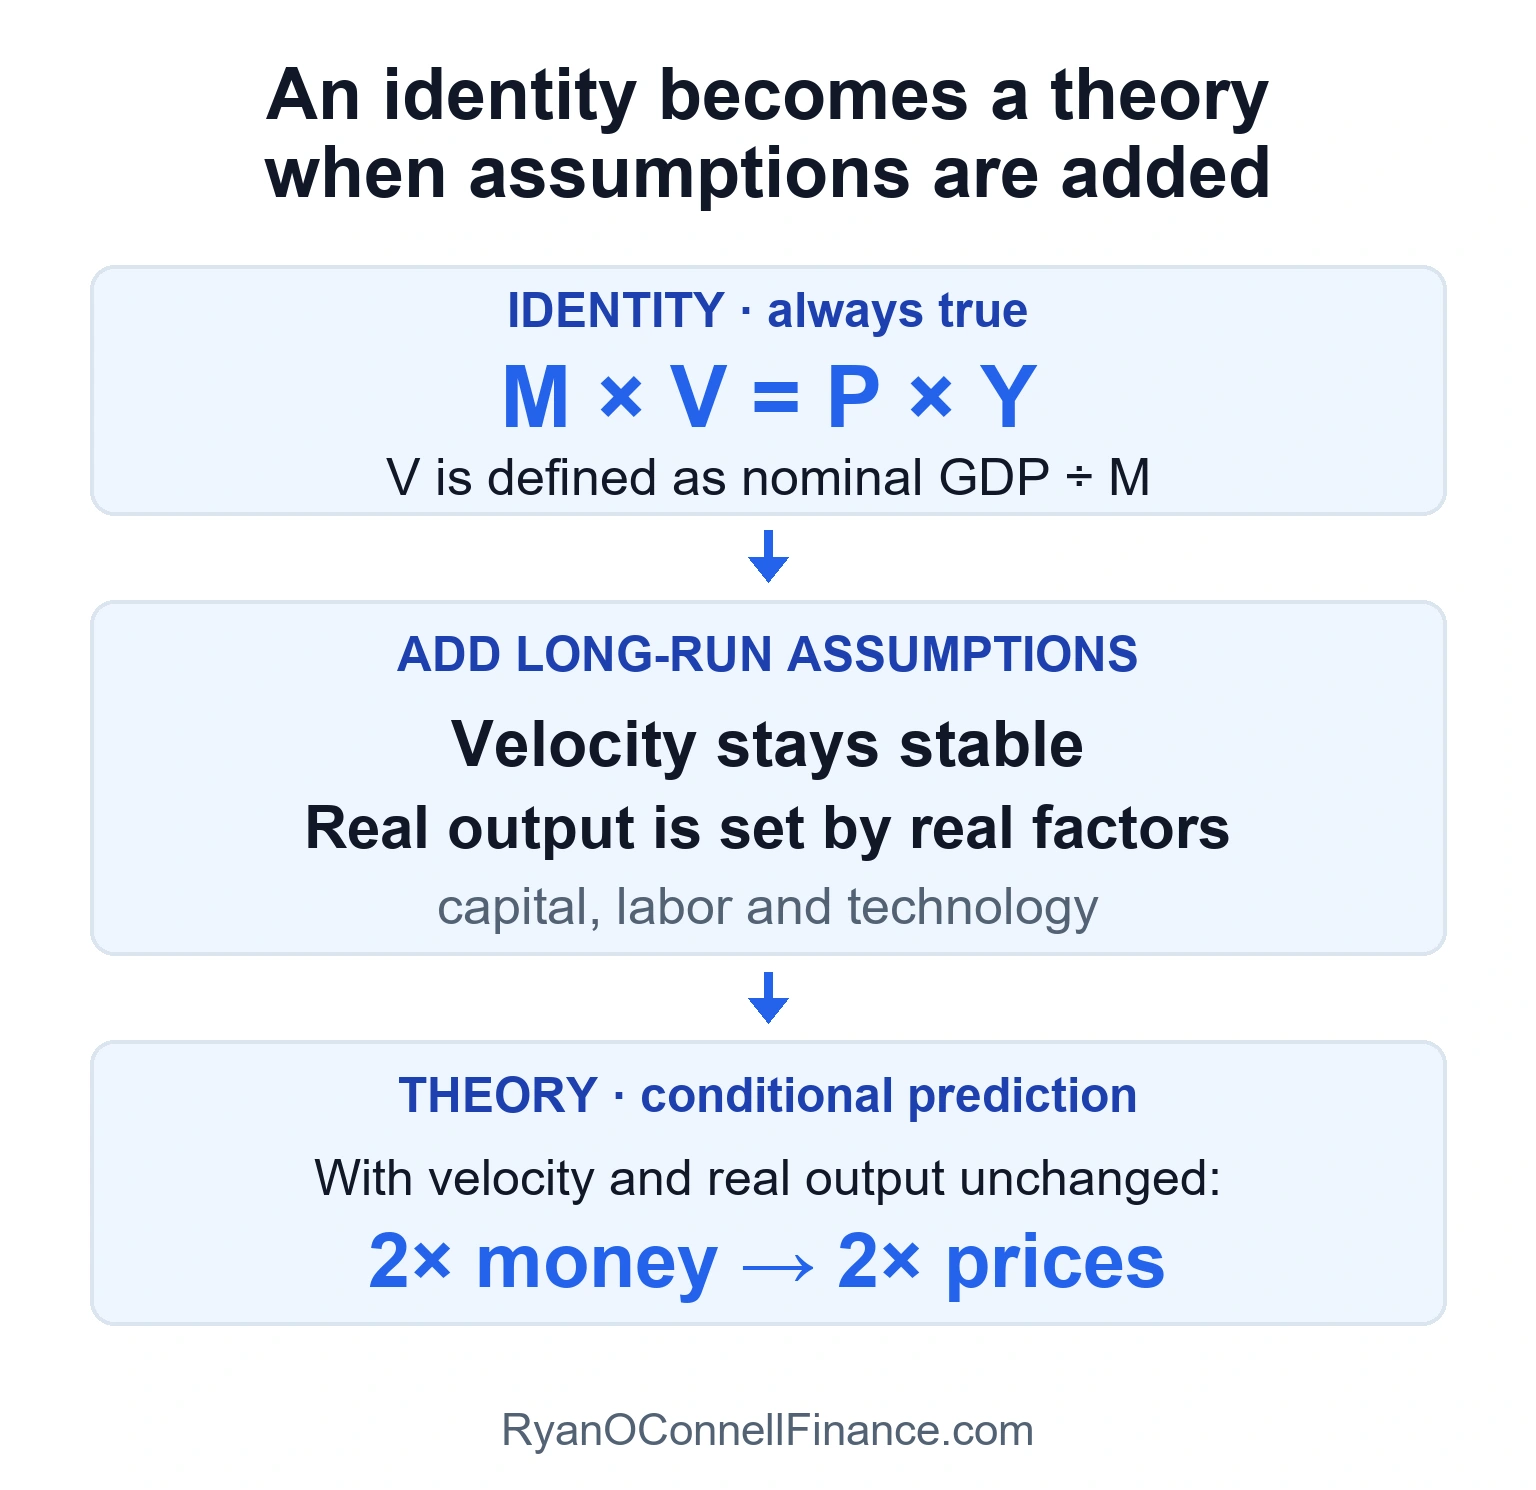
Stable velocity and real output determined by real factors make the price prediction possible. Without those assumptions, MV = PY alone does not tell us how prices respond to a change in money.
A note on versions: Irving Fisher’s original formulation used MV = PT, where T represents the total volume of transactions. The modern version replaces T with Y (real GDP), focusing on final output rather than all transactions. Both are valid; MV = PY is the standard form in macroeconomics today because real GDP is easier to measure and more directly relevant to policy.
In growth-rate form, the equation becomes especially useful:
If velocity growth is approximately zero (the stability assumption), this simplifies to: Inflation ≈ Money Growth − Real GDP Growth. This is the core prediction of the quantity theory.
Velocity of Money
Velocity measures how rapidly money circulates through the economy — how many times the average dollar changes hands in a given year to purchase final goods and services.
For example, if nominal GDP is $27 trillion and the M2 money supply is $21 trillion, then velocity is approximately 1.3 — meaning each dollar is spent about 1.3 times per year on final goods and services.
U.S. M2 velocity was relatively stable in the range of roughly 1.7 to 2.1 from the 1960s through the mid-2000s (about 1.8 in 1960, peaking above 2.1 around 2000), supporting the quantity theory’s assumptions. However, velocity dropped sharply after the 2008 financial crisis and plunged further during COVID-19, falling to approximately 1.13 in mid-2020 as the Fed massively expanded M2 while spending slowed. Velocity is closely related to money demand — when people want to hold more money (higher money demand), velocity falls, and vice versa.
The velocity stability assumption works best over long time horizons and during periods of moderate, stable monetary policy. During financial crises, recessions, or periods of quantitative easing, velocity can shift dramatically — which is why short-run predictions based on the quantity theory often miss the mark.
How Money Growth Causes Inflation
The quantity theory’s key prediction follows a clear logical chain. If velocity is stable and real output (Y) is determined by real factors — capital, labor, and technology — then changes in the money supply must be absorbed by changes in the price level.
This logic relies on two related classical principles:
- The Classical Dichotomy — Real variables (real GDP, employment, real interest rates) are determined by real factors, while nominal variables (price level, nominal wages, nominal interest rates) are determined by the money supply. The two sets of variables are independent in the long run.
- Monetary Neutrality — Changes in the money supply affect nominal variables but do not alter real variables in the long run. With velocity unchanged, doubling the money supply eventually doubles all prices and nominal wages, but leaves real output, real wages, and real interest rates unchanged.
Suppose the Federal Reserve increases the money supply by 8% per year, and the economy’s real GDP grows at 3% per year. If velocity is stable:
Inflation ≈ Money Growth − Real GDP Growth = 8% − 3% = 5%
The growth-rate approximation gives 5% inflation. The exact one-year calculation is (1.08 / 1.03) − 1 ≈ 4.85% when velocity is unchanged.
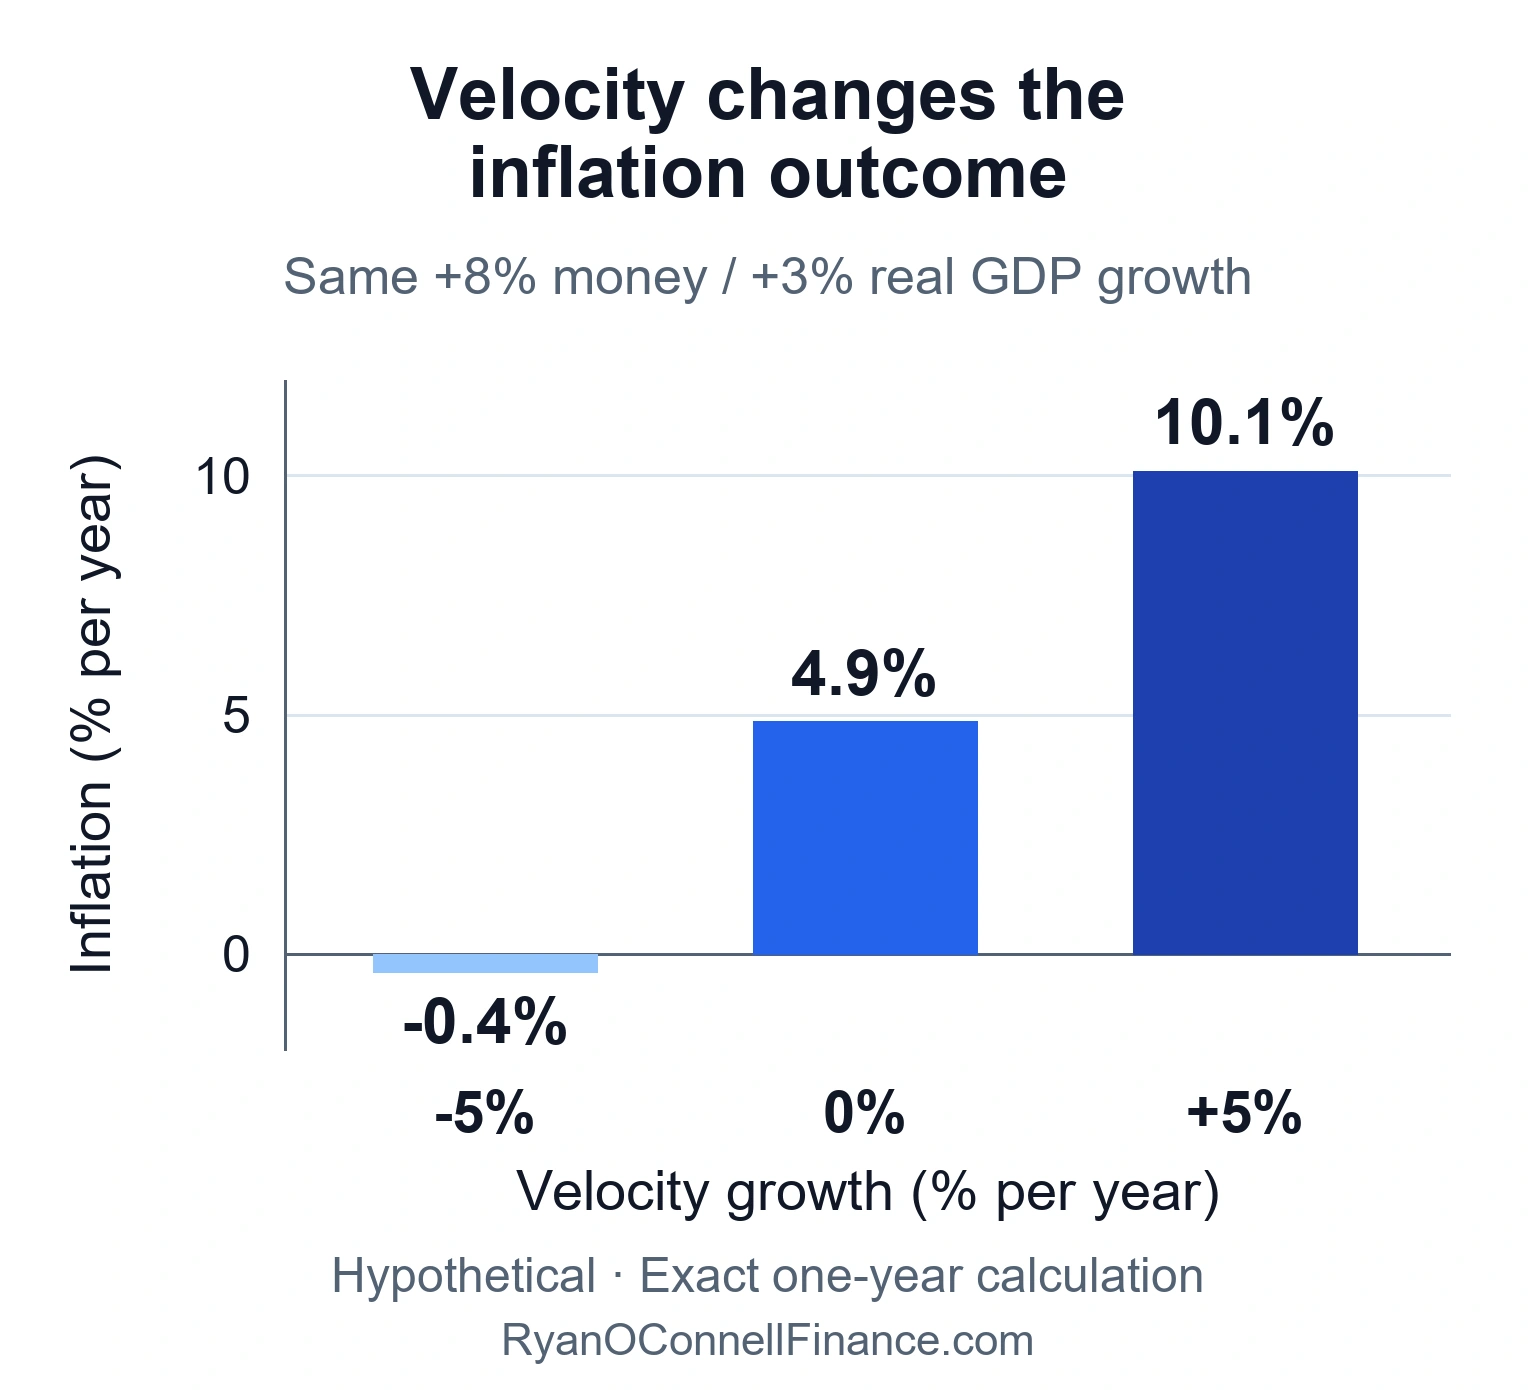
A 5% decline in velocity nearly offsets the price pressure in this example; a 5% rise amplifies it. Money growth alone is therefore insufficient for a short-run inflation forecast.
Historical Evidence and Hyperinflation
The quantity theory’s predictions are most dramatically confirmed by episodes of extreme money supply growth. When central banks rapidly expand the money supply — typically to finance government deficits — the result is predictably severe inflation.
| Country | Period | Peak Monthly Inflation | Cause |
|---|---|---|---|
| Zimbabwe | 2007–2008 | 79.6 billion % | Massive money printing to fund government spending |
| Germany (Weimar) | 1922–1923 | 29,500% | Money creation to pay war reparations |
| Hungary | 1945–1946 | 4.19 × 10¹⁶ % | Post-war reconstruction financed by money printing |
| Venezuela | 2016–2019 | ~220% | Monetization of fiscal deficits amid oil price collapse |
In every case, the pattern is identical: governments printed money to finance spending → money supply growth vastly exceeded real output growth → prices skyrocketed. When money growth was eventually curtailed, inflation stabilized — exactly as the quantity theory predicts.
A modern example reinforces the pattern. U.S. M2 grew approximately 25% in 2020 as the Federal Reserve responded to COVID-19 with aggressive monetary expansion. With a lag of roughly two years, CPI inflation peaked at 9.1% in June 2022 — the highest in four decades. While supply-chain disruptions and fiscal stimulus also contributed, the massive M2 expansion was a key driver, consistent with the quantity theory’s predictions.
Cross-country data also supports the theory. Research by Robert Barro and others shows a strong positive correlation between long-run money supply growth rates and inflation rates across countries. Nations with money growth of 50%+ per year consistently experience high inflation, while countries like Switzerland and Japan, with disciplined monetary policy, maintain low inflation.
The quantity theory works best for large, sustained differences in money growth. For moderate money growth rates (2–10% per year), the relationship between money growth and inflation is much noisier in the short run. Changes in velocity, financial innovation, and shifts in money demand can obscure the connection for years or even decades.
The Fisher Effect
The quantity theory has a direct implication for interest rates, known as the Fisher effect (named after Irving Fisher, who also formalized the quantity theory):
For this comparison, assume the long-run real interest rate stays fixed as expected inflation changes. Under that additional assumption, the Fisher equation implies that higher expected inflation raises nominal rates approximately one for one. Monetary neutrality with respect to the money-stock level alone does not establish that the real rate is invariant to a lasting change in money growth; saving, investment and other real conditions also matter.
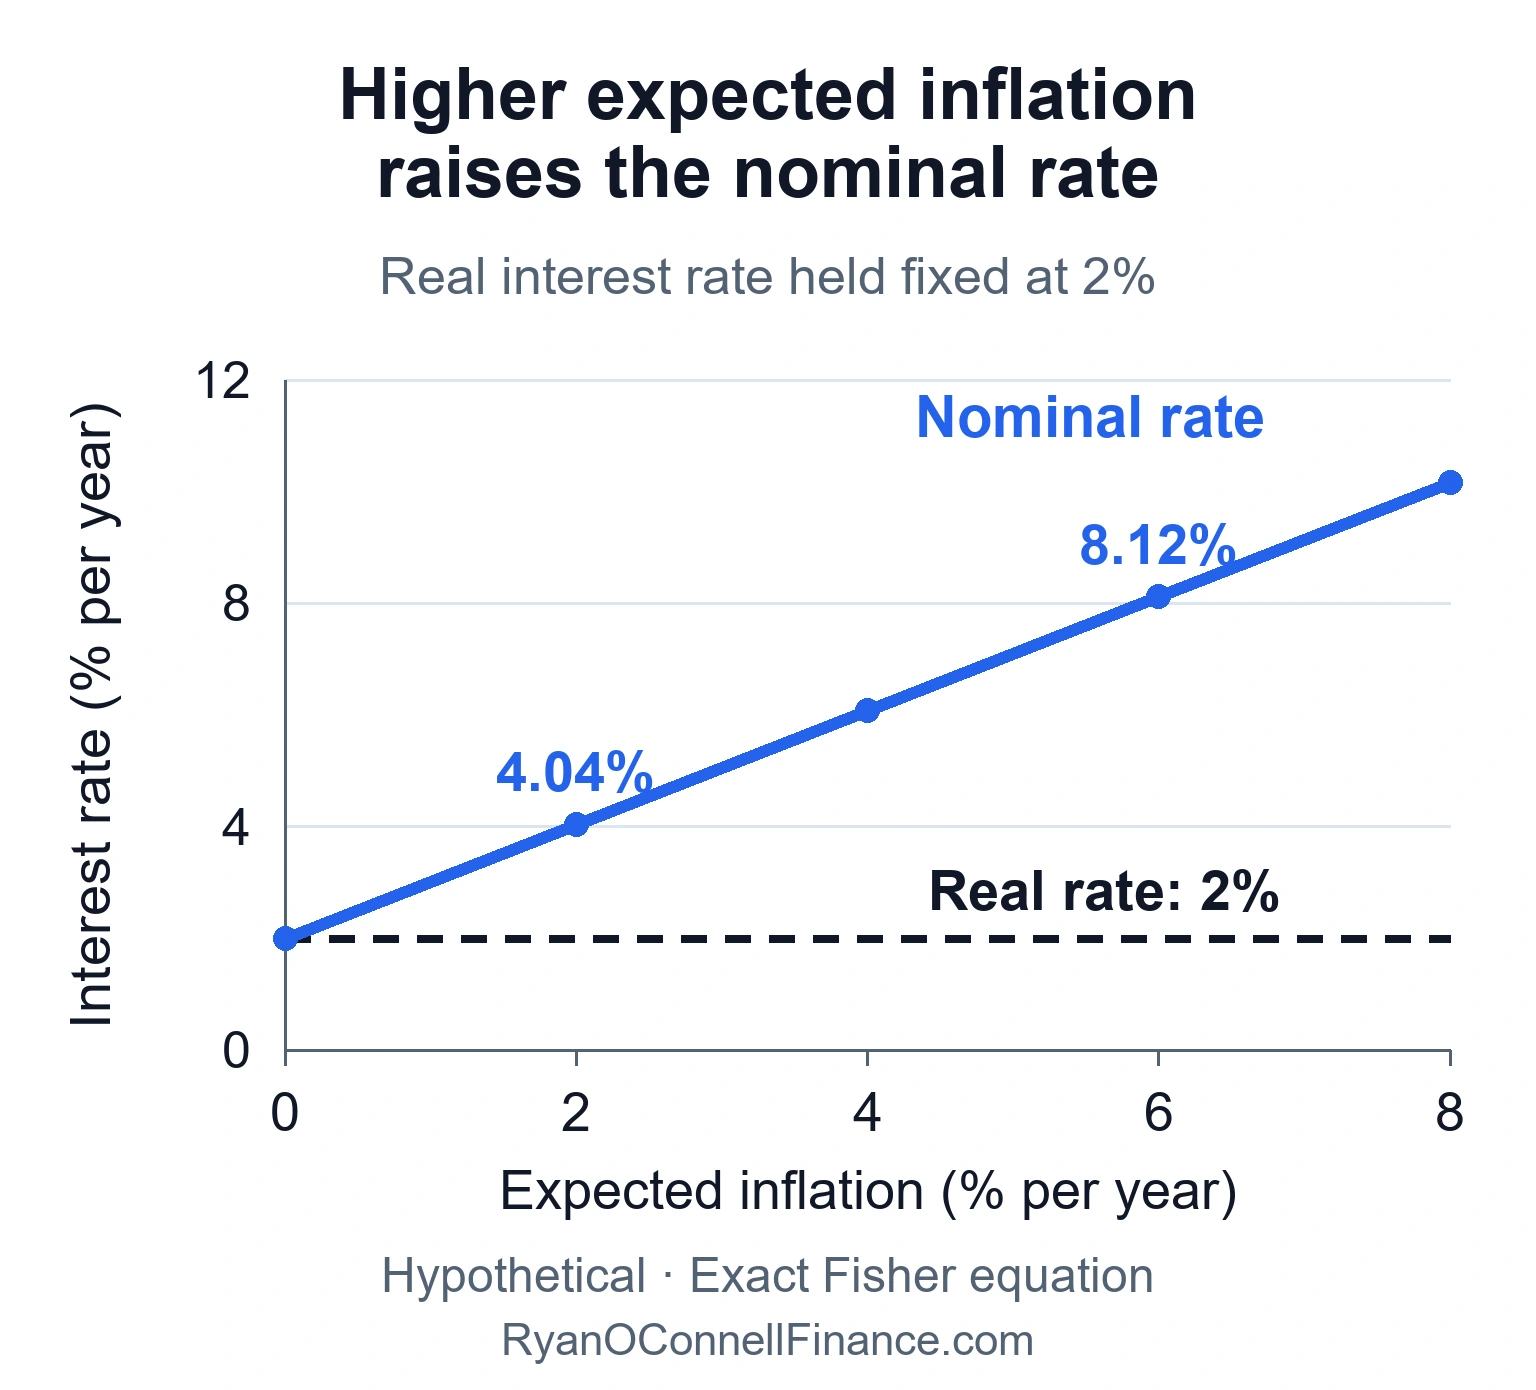
The nominal rate compensates lenders for the expected loss of purchasing power; the assumed real return remains 2%. The exact equation includes the interaction between the real rate and expected inflation, so the nominal increase is slightly larger than the approximation.
The U.S. experience in the 1970s and 1980s illustrates the Fisher effect clearly. As inflation rose from 3% in the mid-1960s to over 13% by 1980, the yield on 10-year Treasury bonds climbed from roughly 5% to over 15%. When Paul Volcker’s Federal Reserve sharply reduced money growth and brought inflation back down to 3–4% by the mid-1980s, nominal interest rates fell correspondingly. Over these decades, nominal rates broadly tracked inflation movements, consistent with the Fisher effect’s long-run prediction — though real rates did fluctuate, particularly during the Volcker disinflation.
How to Analyze Money Growth and Inflation
You can apply the quantity theory framework using publicly available data. The key is comparing money supply growth to real GDP growth over meaningful time periods:
- Track M2 growth: The Federal Reserve publishes weekly M2 data on FRED (Federal Reserve Economic Data). Look at year-over-year percentage changes rather than week-to-week noise.
- Compare to real GDP growth: Under the quantity theory (assuming stable velocity), M2 growth that exceeds real GDP growth signals inflation pressure. For example, if M2 is growing at 10% and real GDP at 3%, the theory predicts roughly 7% inflation. You can also use the full framework: %ΔM + %ΔV ≈ %ΔP + %ΔY.
- Watch velocity trends: FRED also publishes M2 velocity (quarterly). Declining velocity can absorb money growth without inflation; rising velocity amplifies it.
- Allow for lags: Money supply changes typically take 12 to 24 months to fully show up in price data. Compare current inflation to money growth from 1–2 years earlier for a more meaningful signal.
The quantity theory is most useful as a long-run warning system, not a short-run forecasting tool. When M2 growth persistently exceeds 10% per year while real GDP grows at 2–3%, the theory signals that inflation pressure is building — even if price increases have not yet appeared in the data.
Quantity Theory vs. Keynesian Economics
These two frameworks answer different questions about different time horizons. Understanding when each applies is more useful than choosing one over the other:
Quantity Theory (Long-Run Focus)
- Velocity is stable — predictable relationship between money and prices
- Money is neutral in the long run — affects only prices, not real output
- Inflation is a monetary phenomenon — caused by excessive money growth
- Long-run focus — best for explaining sustained inflation trends
- Policy implication: control the money supply to control inflation
Keynesian / Sticky-Price (Short-Run Focus)
- Velocity varies with interest rates, expectations, and economic conditions
- Money can affect real output in the short run due to sticky prices and wages
- Inflation can be demand-driven or cost-driven — not solely monetary
- Short-run focus — emphasizes business cycles and aggregate demand
- Policy implication: active fiscal and monetary policy to stabilize output
These frameworks answer different horizon questions rather than contradicting each other. The quantity theory provides the best framework for understanding long-run inflation trends and extreme episodes like hyperinflation — asking “why is inflation persistently high?” The Keynesian view better explains short-run fluctuations in output and employment — asking “why did the economy slow this quarter?” Central banks like the Federal Reserve effectively blend both perspectives — managing money growth for long-run price stability while adjusting interest rates for short-run stabilization.
Common Mistakes
Understanding these common errors helps avoid misapplying the quantity theory:
1. Confusing the Equation of Exchange with the Quantity Theory — The equation MV = PY is an identity that is always true by definition. The quantity theory additionally assumes stable velocity and real output determined by real factors. Many students treat the equation itself as the theory, missing this crucial distinction.
2. Applying the Theory to Short-Run Analysis — The quantity theory is a long-run framework. In the short run, money supply changes can affect real output, velocity can shift, and prices may be sticky. Using the theory to predict next quarter’s inflation from this month’s money supply data is a misapplication.
3. Assuming Instant Transmission — Money supply increases do not cause immediate inflation. Empirical research suggests transmission lags of 12 to 24 months. The U.S. M2 expansion during COVID-19 (2020) contributed to elevated inflation that peaked in 2022 — a roughly two-year lag.
4. Treating Velocity as Constant Rather Than Stable — The theory assumes velocity is approximately stable, not perfectly constant. Velocity can and does change, especially during financial crises. The sharp decline in M2 velocity after 2008 is a key reason why the Fed’s quantitative easing did not produce the hyperinflation some predicted.
5. Confusing Broad Money (M2) with the Monetary Base — Quantitative easing creates central-bank reserves, while commercial-bank lending creates deposits. Reserves settle payments between banks; banks do not lend reserves to households as deposits. Reserve growth does not mechanically produce proportional M2 growth: lending also depends on demand, credit risk, capital and profitability. The quantity theory’s predictions depend on broad money (M2) growth — the money that actually circulates in the economy — not on the size of the Federal Reserve’s balance sheet.
Limitations of the Quantity Theory
While powerful as a long-run framework, the quantity theory has significant limitations that economists and investors should keep in mind:
The quantity theory’s central assumption — stable velocity — has been challenged by real-world data. U.S. M2 velocity fell from 2.0 in 2007 to 1.1 in 2020, a 45% decline that severely weakened the short-run predictive power of the money-to-inflation link.
1. Velocity Instability — Financial innovation (credit cards, electronic payments, money market funds) and policy shifts (quantitative easing, interest on reserves) can cause sustained changes in velocity that break the simple money-to-inflation relationship.
2. Better for High-Inflation Countries — The cross-country correlation between money growth and inflation is strongest for countries with high money growth rates (above 20% per year). For low-inflation economies like the U.S., Japan, and the Eurozone, the relationship is much weaker in practice.
3. No Explanation of Relative Prices — The theory explains the overall price level but says nothing about why some prices rise faster than others. For understanding specific price dynamics (housing, energy, healthcare), other frameworks are needed.
4. Exogenous Money Assumption — The theory assumes central banks control the money supply directly. In modern economies with fractional-reserve banking, much of the money supply is created endogenously by commercial banks through lending, complicating the causal story.
5. Ignores Expectations and Credibility — Central bank credibility can anchor inflation expectations regardless of temporary money supply fluctuations. A credible inflation-targeting central bank can expand the money supply during a crisis without triggering inflation because the public expects the expansion to be temporary.
The quantity theory of money remains the most important framework for understanding why sustained money supply growth leads to inflation. Its predictions are most reliable over long time horizons and for large differences in money growth rates. For short-run analysis and moderate money growth, it should be supplemented with attention to velocity trends, inflation expectations, and real economic conditions.
Frequently Asked Questions
Disclaimer
This article is for educational and informational purposes only and does not constitute investment or financial advice. Economic data and historical figures cited are approximate and sourced from publicly available references. The quantity theory of money is a theoretical framework with known limitations. Always conduct your own research and consult qualified professionals before making financial decisions.
Keep reading
Next in this series
Part 22 of 33 in Economics Essentials
The Costs of Inflation: Shoeleather, Menu Costs & MoreMore in Economics
-
Supply and Demand: How Markets Determine Prices
Supply and demand is the foundational economic model explaining how prices are set, how markets reach equilibrium, and what causes surpluses and shortages.
-
Gross Domestic Product (GDP)
Gross domestic product (GDP) is the total market value of all final goods and services produced within a country.
-
Inflation & Consumer Price Index (CPI) Explained: How It Works & Why It Matters
Learn what inflation is, how the Consumer Price Index (CPI) measures it, and why it matters for investment decisions.