Exchange Rate Determination: Nominal & Real Exchange Rates
Table of Contents
The real exchange rate is one of the most important prices in an open economy. While the nominal exchange rate tells you how many units of one currency trade for another, the real exchange rate reveals something far more useful: how expensive one country’s goods are relative to another’s, after adjusting for price level differences. Whether you are analyzing trade competitiveness between nations, evaluating how inflation differentials erode currency values, or studying the macroeconomic forces that drive currency movements, understanding the distinction between nominal and real exchange rates is essential.
This guide covers the complete framework: the nominal and real exchange rate definitions, the real exchange rate formula, how to calculate and interpret it, how appreciation and depreciation affect trade flows, and the macroeconomic forces that determine exchange rates in both the short run and long run.
What Is a Real Exchange Rate?
A nominal exchange rate is the market-quoted rate at which one currency trades for another. When you see that the dollar-euro rate is 1.10, that means one euro costs 1.10 U.S. dollars. The nominal rate is what you encounter at currency exchanges, in FX markets, and on financial news tickers.
The real exchange rate measures the relative price of foreign goods in terms of domestic goods under the convention used here. It takes the nominal exchange rate and adjusts it for differences in price levels between countries. While the nominal rate tells you the price of foreign currency, the real exchange rate tells you the price of foreign goods — making it a key price for trade competitiveness and net export flows.
The distinction matters because nominal exchange rates can be misleading. A currency may nominally weaken (depreciate) while the country’s goods become less competitive in international markets — if faster domestic inflation more than offsets that depreciation. Only the real exchange rate captures both currency movements and relative price changes simultaneously.
The Real Exchange Rate Formula
The real exchange rate adjusts the nominal rate by the ratio of foreign to domestic price levels:
Where:
- S = nominal exchange rate (domestic currency per unit of foreign currency — e.g., 1.10 USD per EUR)
- Pf = foreign price level (in foreign currency)
- Pd = domestic price level (in domestic currency)
For equivalent baskets, the RER is measured in domestic baskets per foreign basket. When the RER rises, foreign goods are becoming more expensive relative to domestic goods — meaning domestic goods are more competitive internationally. When the RER falls, domestic goods are becoming relatively more expensive and less competitive.
This article follows the convention S = domestic currency per foreign currency, consistent with our purchasing power parity guide. Some macroeconomics textbooks (including Mankiw) use the inverse convention (foreign currency per domestic). The formulas are equivalent — just be consistent within any single analysis.
How to Calculate the Real Exchange Rate
Single-Good Example
Given: A standard basket of consumer goods costs $100 in the United States and €95 in the euro area. The nominal exchange rate is S = 1.10 USD/EUR (it costs $1.10 to buy one euro).
RER = 1.10 × (95 / 100) = 1.045
Interpretation: European goods cost about 4.5% more than equivalent American goods after converting currencies. From the U.S. perspective, the real exchange rate above 1.0 means foreign goods are relatively expensive — American goods are price-competitive in this market.
Tracking Real Exchange Rate Changes Over Time
In practice, economists track changes in the real exchange rate over time using consumer price indices (CPI). While CPI levels cannot be compared directly across countries (each country’s index has a different base year and basket), CPI growth rates are valid for measuring how the real exchange rate has shifted. Cross-country level comparisons require PPP-based price indices published by the World Bank (International Comparison Program) or the OECD.
Given: In early 2020, the yen traded at approximately 110 JPY/USD. By late 2024, it had weakened to about 150 JPY/USD — a rise of roughly 36% in the JPY-per-USD quote S. Over the same period, U.S. cumulative CPI inflation was approximately 22%, while Japan’s cumulative CPI inflation was approximately 11%.
The real exchange rate change combines the nominal depreciation with the inflation differential. From Japan’s perspective (domestic = yen, foreign = dollar):
RER change factor ≈ Nominal S change factor × (Foreign inflation factor / Domestic inflation factor) = 1.36 × (1.22 / 1.11) ≈ 1.50
Interpretation: Japan’s bilateral real exchange rate against the U.S. rose by roughly 50% over four years. Under our formula, a rising RER means American goods became substantially more expensive relative to Japanese goods. This real yen weakness boosted Japanese export competitiveness — helping support export volumes even as Japan’s overall goods trade balance remained in deficit.
Bilateral RER vs Real Effective Exchange Rate (REER)
The examples above show bilateral real exchange rates — comparing two currencies. But countries trade with many partners simultaneously. The real effective exchange rate (REER) solves this by calculating a trade-weighted average of bilateral real exchange rates across all major trading partners.
Central banks, the IMF, and the Bank for International Settlements (BIS) publish REER indices for most economies. An important convention difference: BIS and IMF REER indices measure the real value of the domestic currency, so a rising REER means the domestic currency has appreciated in real terms — making domestic goods less competitive. This is the opposite direction from the bilateral RER formula above, where a rising RER means foreign goods are getting more expensive (domestic goods more competitive). When reading REER data, always check the index convention before interpreting direction.
The Balassa-Samuelson effect is an important consideration when interpreting REER levels across countries at different stages of development. Developing economies systematically have lower price levels because non-tradeable goods (haircuts, rent, local services) are cheaper due to lower wages. This means their RER will naturally differ from developed-economy benchmarks without implying true “misvaluation.” For a deeper analysis, see our guide on purchasing power parity.
How Appreciation and Depreciation Affect Trade
A currency appreciates when it strengthens — buying more foreign currency than before. It depreciates when it weakens — buying less. These movements can occur in both nominal and real terms, and the distinction is critical. The table below holds domestic and foreign price levels fixed; it shows the usual direction of the trade response in the simplified model.
| Movement | Nominal Effect | Real Effect on Trade |
|---|---|---|
| Domestic currency appreciates | Buys more foreign currency (S falls) | Domestic goods relatively more expensive → net exports decrease |
| Domestic currency depreciates | Buys less foreign currency (S rises) | Domestic goods relatively cheaper → net exports increase |
In the simplified open-economy framework used here, recorded net exports (NX) equal net capital outflow (NCO) by accounting identity, omitting net primary income, transfers, capital-account adjustments and measurement errors. The model explains how the real exchange rate reconciles planned net exports with modeled net capital outflow; adjustment does not make the accounting identity true. Holding the net-export schedule and other conditions fixed:
- An increase in modeled net capital outflow shifts the net supply of domestic currency right. The new equilibrium has a higher RER under this quotation: a real depreciation that makes domestic goods relatively cheaper and raises planned net exports.
- A decrease in modeled net capital outflow shifts net supply left and lowers equilibrium RER: real appreciation with lower planned net exports. Positive or negative NCO identifies a net outflow or inflow; its sign alone does not establish a currency movement.
This adjustment process can be visualized as a market for foreign-currency exchange. The net supply of dollars reflects NCO: domestic acquisition of foreign assets minus foreign acquisition of domestic assets. The schematic describes net flows, not gross foreign-exchange turnover. Its positive-NCO case is hypothetical, not an observation about the actual U.S. balance. In this simplified model, NCO is fixed at the given real interest rate, so the supply curve is vertical. The demand for dollars reflects net exports (NX). Under this article’s convention, RER = S × (Pf / Pd), a higher RER makes foreign goods more expensive relative to U.S. goods. This raises net exports and the quantity of dollars demanded, so the demand curve slopes upward.
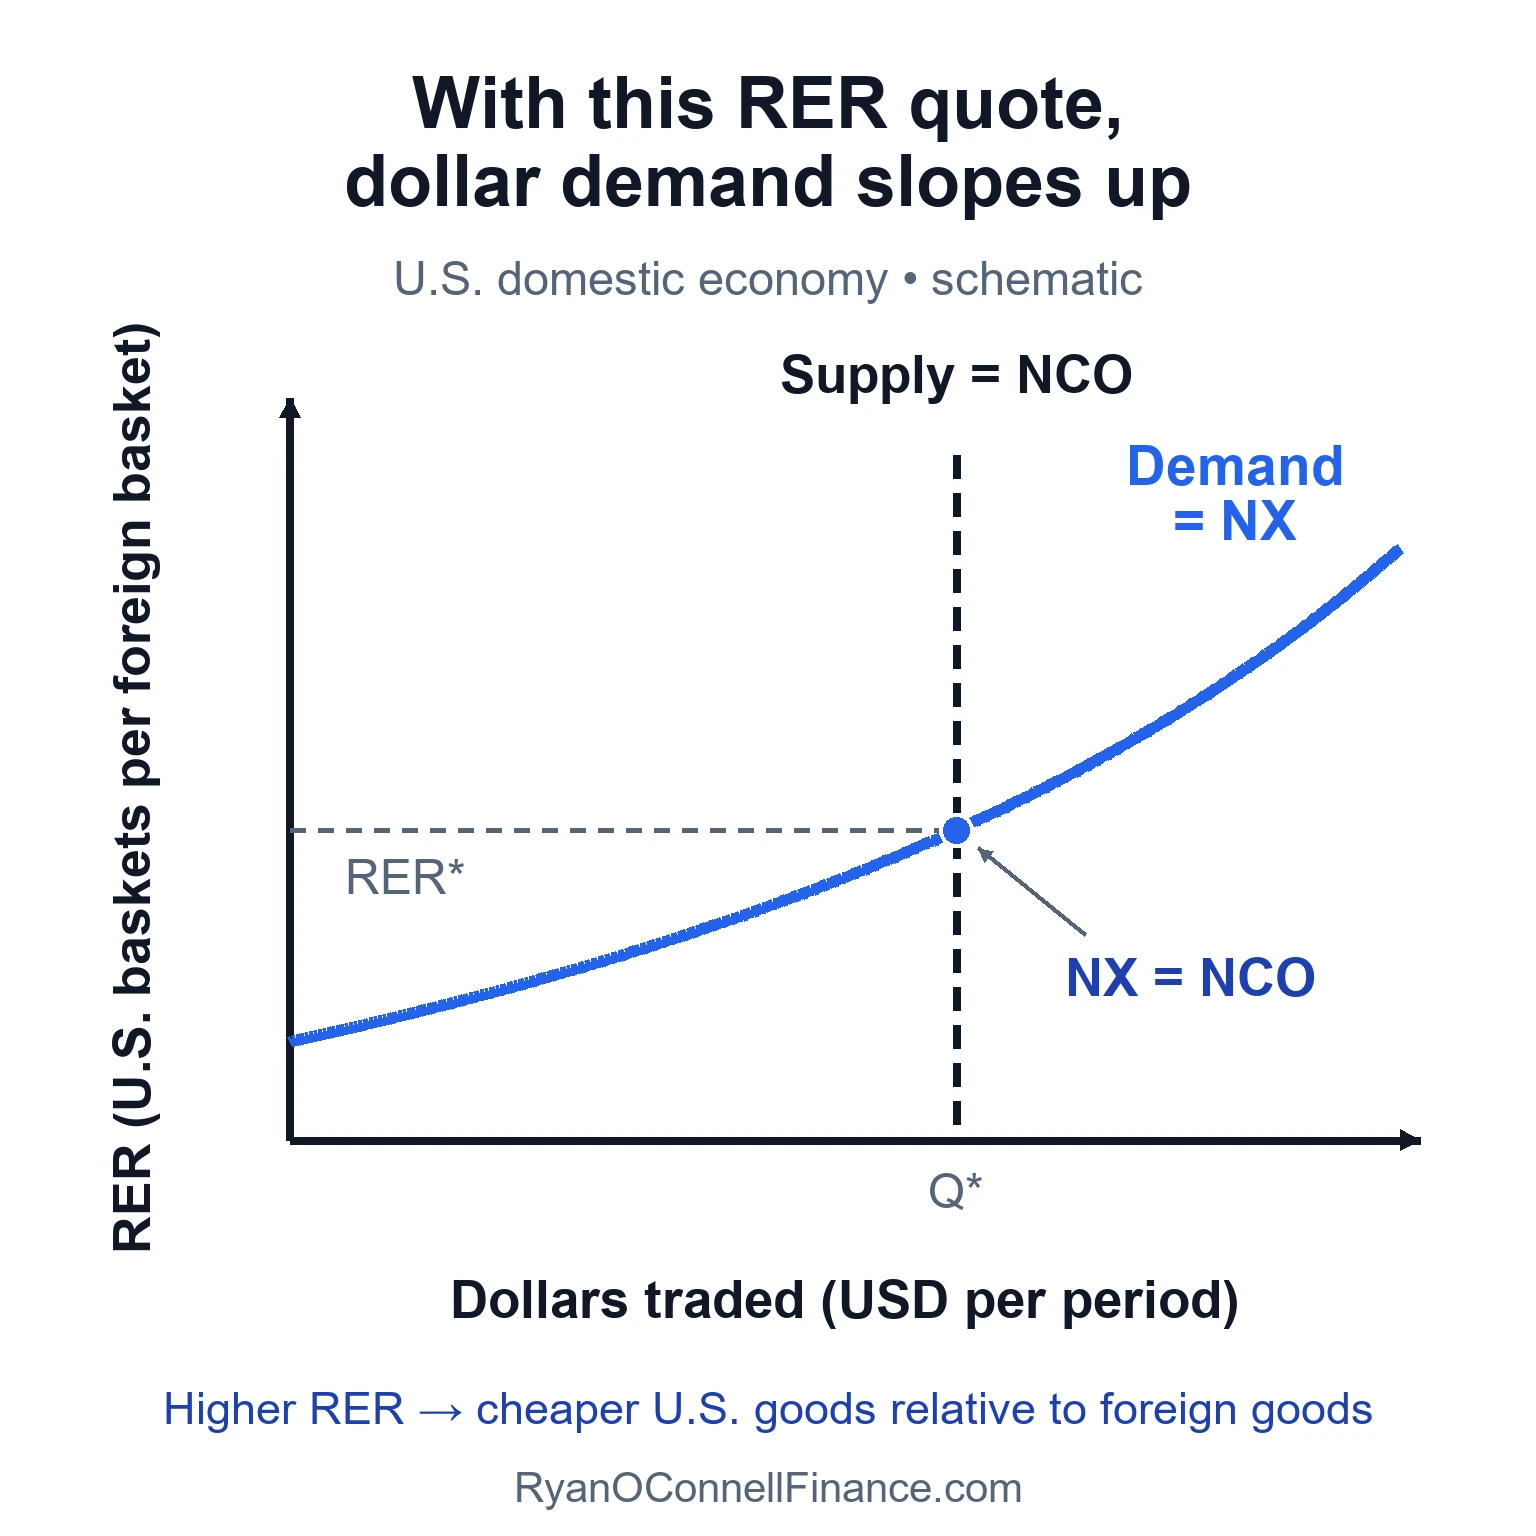
The intersection equates planned NX with modeled NCO. Moving up this RER axis means a real depreciation of the U.S. dollar: U.S. goods become cheaper relative to foreign goods.
Historical example: Between 1970 and 1998, the U.S. dollar lost over 50% of its value against the German mark but more than doubled against the Italian lira. Germany’s average annual inflation was 3.5%, well below the U.S. rate of 5.3%, so the dollar depreciated in nominal terms. Italy’s average annual inflation was 9.6%, far exceeding U.S. inflation, so the dollar appreciated against the lira. These movements illustrate how inflation differentials drive long-run nominal exchange rate trends — a core prediction of purchasing power parity.
What Determines the Real Exchange Rate?
Exchange rate determination involves different forces at different time horizons. Separating long-run and short-run drivers helps explain why currencies can deviate dramatically from “fair value” for extended periods.
Long-Run Nominal Determinants
Relative price levels and inflation differentials are the dominant long-run drivers of nominal exchange rates. Countries with persistently higher inflation see their currencies depreciate over time, as the same unit of currency buys less and less relative to a lower-inflation trading partner. This is the central prediction of purchasing power parity. Money supply growth rates ultimately determine inflation, so monetary policy is the fundamental long-run anchor for nominal exchange rates.
Long-Run Real Determinants
Productivity differences (the Balassa-Samuelson effect) cause real exchange rates to deviate systematically across countries. Rapidly developing economies experience real appreciation as productivity gains in their tradeable-goods sectors push up wages economy-wide, raising the price of non-tradeable goods.
National saving and investment patterns determine whether a country is a net exporter or importer of capital. In this simplified model, a larger saving-investment gap increases net capital outflow. With the net-export schedule and other conditions unchanged, the equilibrium moves toward real depreciation and a larger trade surplus. A surplus or positive net outflow does not by itself establish that a currency is undervalued relative to an equilibrium benchmark.
Short-Run Determinants
Interest rate differentials drive massive short-run capital flows. When a country raises interest rates relative to its trading partners, global investors shift funds into that country’s assets, causing the currency to appreciate. For a detailed analysis of the interest rate–exchange rate link, see interest rate parity.
Capital flows, speculation, and expectations can dominate exchange rate movements over months and quarters. Changes in risk appetite, geopolitical events, and shifts in market expectations about future policy all move currencies in ways that have little to do with trade competitiveness or price levels.
Central bank intervention — direct buying or selling of foreign exchange reserves — can influence exchange rates in the short run, though the effectiveness of sustained intervention is debated among economists.
PPP anchors exchange rates in the long run, but capital flows dominate short-run movements. This is why exchange rate forecasting is notoriously difficult — the famous “Meese-Rogoff puzzle” demonstrated that simple random-walk models often outperform structural economic models at forecasting exchange rates over horizons of one year or less.
Nominal Exchange Rate vs Real Exchange Rate
Nominal Exchange Rate
- Market-quoted rate between two currencies
- Determined by FX supply and demand
- Affected by inflation differentials over time
- Used in currency transactions, FX trading, and financial reporting
- Does not directly reflect purchasing power or trade competitiveness
- Can be misleading if inflation rates differ significantly between countries
Real Exchange Rate
- Nominal rate adjusted for relative price levels
- Measures the relative price of foreign goods in domestic goods under this article’s convention
- Determines trade competitiveness and net export flows
- Used by economists, central banks, and the IMF for policy analysis
- Captures both currency movements and inflation differentials
- Better indicator for evaluating long-run currency valuation
Common Mistakes
1. Confusing nominal appreciation with real appreciation. A currency can nominally appreciate while depreciating in real terms if foreign prices rise enough relative to domestic prices to more than offset the nominal appreciation. Conversely, faster domestic inflation can offset a nominal depreciation and produce a real appreciation. Always check the real exchange rate before drawing conclusions about trade competitiveness.
2. Assuming exchange rate movements always reflect fundamentals. In the short run, capital flows driven by speculation, risk appetite, and expectations often dominate exchange rate movements. The yen carry trade unwind of 2024, for example, moved USD/JPY by over 10% in weeks — far more than any shift in trade fundamentals would justify. For more on these dynamics, see our guide on the carry trade.
3. Using bilateral rates when trade-weighted indices are more appropriate. A country’s overall competitiveness depends on its exchange rate against all major trading partners, not just one. The REER (real effective exchange rate) provides a more complete picture than any single bilateral rate.
4. Ignoring that PPP holds only in the long run. Purchasing power parity is a useful long-run anchor, but short-run deviations are large, persistent, and can last years or even decades. Using PPP as a short-run trading signal without considering mean-reversion timelines can be costly.
5. Assuming an unchanged nominal rate means the real rate is unchanged. Consider a hypothetical five-year extension of the article’s example: domestic inflation stays at 5% per year, foreign inflation stays at 2%, and the nominal rate S stays fixed.
| Time (years) | Real RER (index) | Nominal S (index) |
|---|---|---|
| 0 | 100.00 | 100.00 |
| 1 | 97.14 | 100.00 |
| 2 | 94.37 | 100.00 |
| 3 | 91.67 | 100.00 |
| 4 | 89.05 | 100.00 |
| 5 | 86.51 | 100.00 |
Hypothetical; both indices start at 100. Annual inflation is 5% domestically and 2% abroad; S is fixed.
After five years, the RER index falls to 86.51, a 13.5% decline, despite an unchanged nominal rate. Domestic goods become relatively more expensive — a real appreciation of the domestic currency that erodes price competitiveness.
Limitations of Real Exchange Rate Analysis
Exchange rate models have notoriously poor short-run forecasting ability. The “Meese-Rogoff puzzle” — one of the most robust findings in international finance — shows that structural economic models consistently fail to outperform a simple random walk at forecasting exchange rates over horizons of one year or less.
1. Non-traded goods and services. Haircuts, rent, healthcare, and many other services cannot be arbitraged across borders. Since these make up a large share of any country’s price level, the law of one price — which underpins PPP and real exchange rate equilibrium — applies imperfectly at best.
2. Transaction costs and trade barriers. Tariffs, transportation costs, regulatory differences, and non-tariff barriers prevent price equalization even for traded goods. These frictions mean real exchange rates can deviate from theoretical equilibrium for extended periods.
3. Capital flows can overwhelm trade fundamentals. Daily foreign exchange trading volume is approximately $9.6 trillion (per the 2025 BIS Triennial Survey) — dwarfing global trade in goods and services. Capital account transactions, not trade flows, drive the vast majority of short-run exchange rate movements.
4. Measurement challenges. Calculating the real exchange rate requires comparable price indices across countries. CPI baskets differ in composition, base years vary, and data publication lags can be substantial — especially for developing economies. These measurement issues add uncertainty to any real exchange rate estimate.
Frequently Asked Questions
Disclaimer
This article is for educational and informational purposes only and does not constitute financial or investment advice. Exchange rate data cited reflects approximate values at the time of writing and may differ based on the data source and measurement methodology. Real exchange rate calculations depend on the price indices and conventions used. Always conduct your own research and consult qualified professionals before making investment or policy decisions.
Keep reading
Next in this series
Part 26 of 33 in Economics Essentials
Aggregate Demand & Aggregate Supply: The AD-AS Model ExplainedMore in Economics
-
Supply and Demand: How Markets Determine Prices
Supply and demand is the foundational economic model explaining how prices are set, how markets reach equilibrium, and what causes surpluses and shortages.
-
Gross Domestic Product (GDP)
Gross domestic product (GDP) is the total market value of all final goods and services produced within a country.
-
Inflation & Consumer Price Index (CPI) Explained: How It Works & Why It Matters
Learn what inflation is, how the Consumer Price Index (CPI) measures it, and why it matters for investment decisions.