Trade Balance, Balance of Payments & Capital Flows
Table of Contents
A nation’s trade balance reflects its relationship with the global economy. When a country imports more than it exports, it runs a trade deficit. In the simplified textbook model developed below, that deficit is matched by net capital inflow; real-world balance-of-payments accounts also include income, transfers, and other adjustments. Whether you are analyzing U.S. trade policy, evaluating how budget deficits spill over into trade imbalances, or studying for an economics exam, understanding the trade balance, the balance of payments, and the identity between trade flows and capital flows is essential. This guide covers the complete framework: how the trade balance is measured, how the balance of payments works, the fundamental NX = NCO identity, the saving-investment connection, the twin deficits hypothesis, and what happens when capital flows reverse suddenly.
What Is the Trade Balance?
The trade balance — also called net exports — measures the difference between a country’s exports and its imports. It is one of the four components of GDP (Y = C + I + G + NX) and the most direct measure of a nation’s trade position with the rest of the world.
The trade balance equals exports minus imports: NX = Exports − Imports. When exports exceed imports, the country runs a trade surplus (NX > 0). When imports exceed exports, the country runs a trade deficit (NX < 0). When the two are equal, the country has balanced trade (NX = 0). A trade surplus or deficit is not inherently good or bad — the economic context determines whether it reflects strength or weakness.
Several factors influence a country’s trade balance:
- Consumer tastes for domestic versus foreign goods
- Prices of goods at home and abroad
- Exchange rates — a weaker currency makes exports cheaper and imports more expensive (see exchange rates in macroeconomics)
- Incomes at home and abroad — rising domestic income increases imports
- Transportation costs between trading partners
- Government trade policies such as tariffs and quotas
Trade policy can affect the composition of trade. Below, we derive the simplified textbook link between net exports, national saving, and domestic investment, while distinguishing it from the broader current-account identity used in real-world accounts.
The Balance of Payments
The balance of payments (BOP) is the accounting record of all economic transactions between a country’s residents and the rest of the world over a given period. It consists of three accounts.
| Account | What It Records | Examples |
|---|---|---|
| Current Account | Trade in goods and services, primary income (including investment income and employee compensation), and current transfers (secondary income) | Merchandise exports/imports, service fees, dividend and interest payments, foreign aid, remittances |
| Capital Account | Capital transfers and transactions in nonproduced, nonfinancial assets | Debt forgiveness, investment grants, purchases of trademarks or franchises |
| Financial Account | Transactions in financial assets and liabilities | Foreign direct investment (FDI), portfolio investment (stocks, bonds), central bank reserve transactions |
A country’s net lending or borrowing is measured by the combined current and capital accounts. Ignoring the statistical discrepancy, current account + capital account = financial account under the BEA/BPM6 convention: the financial-account balance is net acquisition of foreign financial assets minus net incurrence of liabilities to foreigners. A combined deficit therefore corresponds to a negative financial-account balance and net borrowing from abroad. That borrowing can involve acquiring fewer foreign assets as well as incurring more liabilities to foreigners.
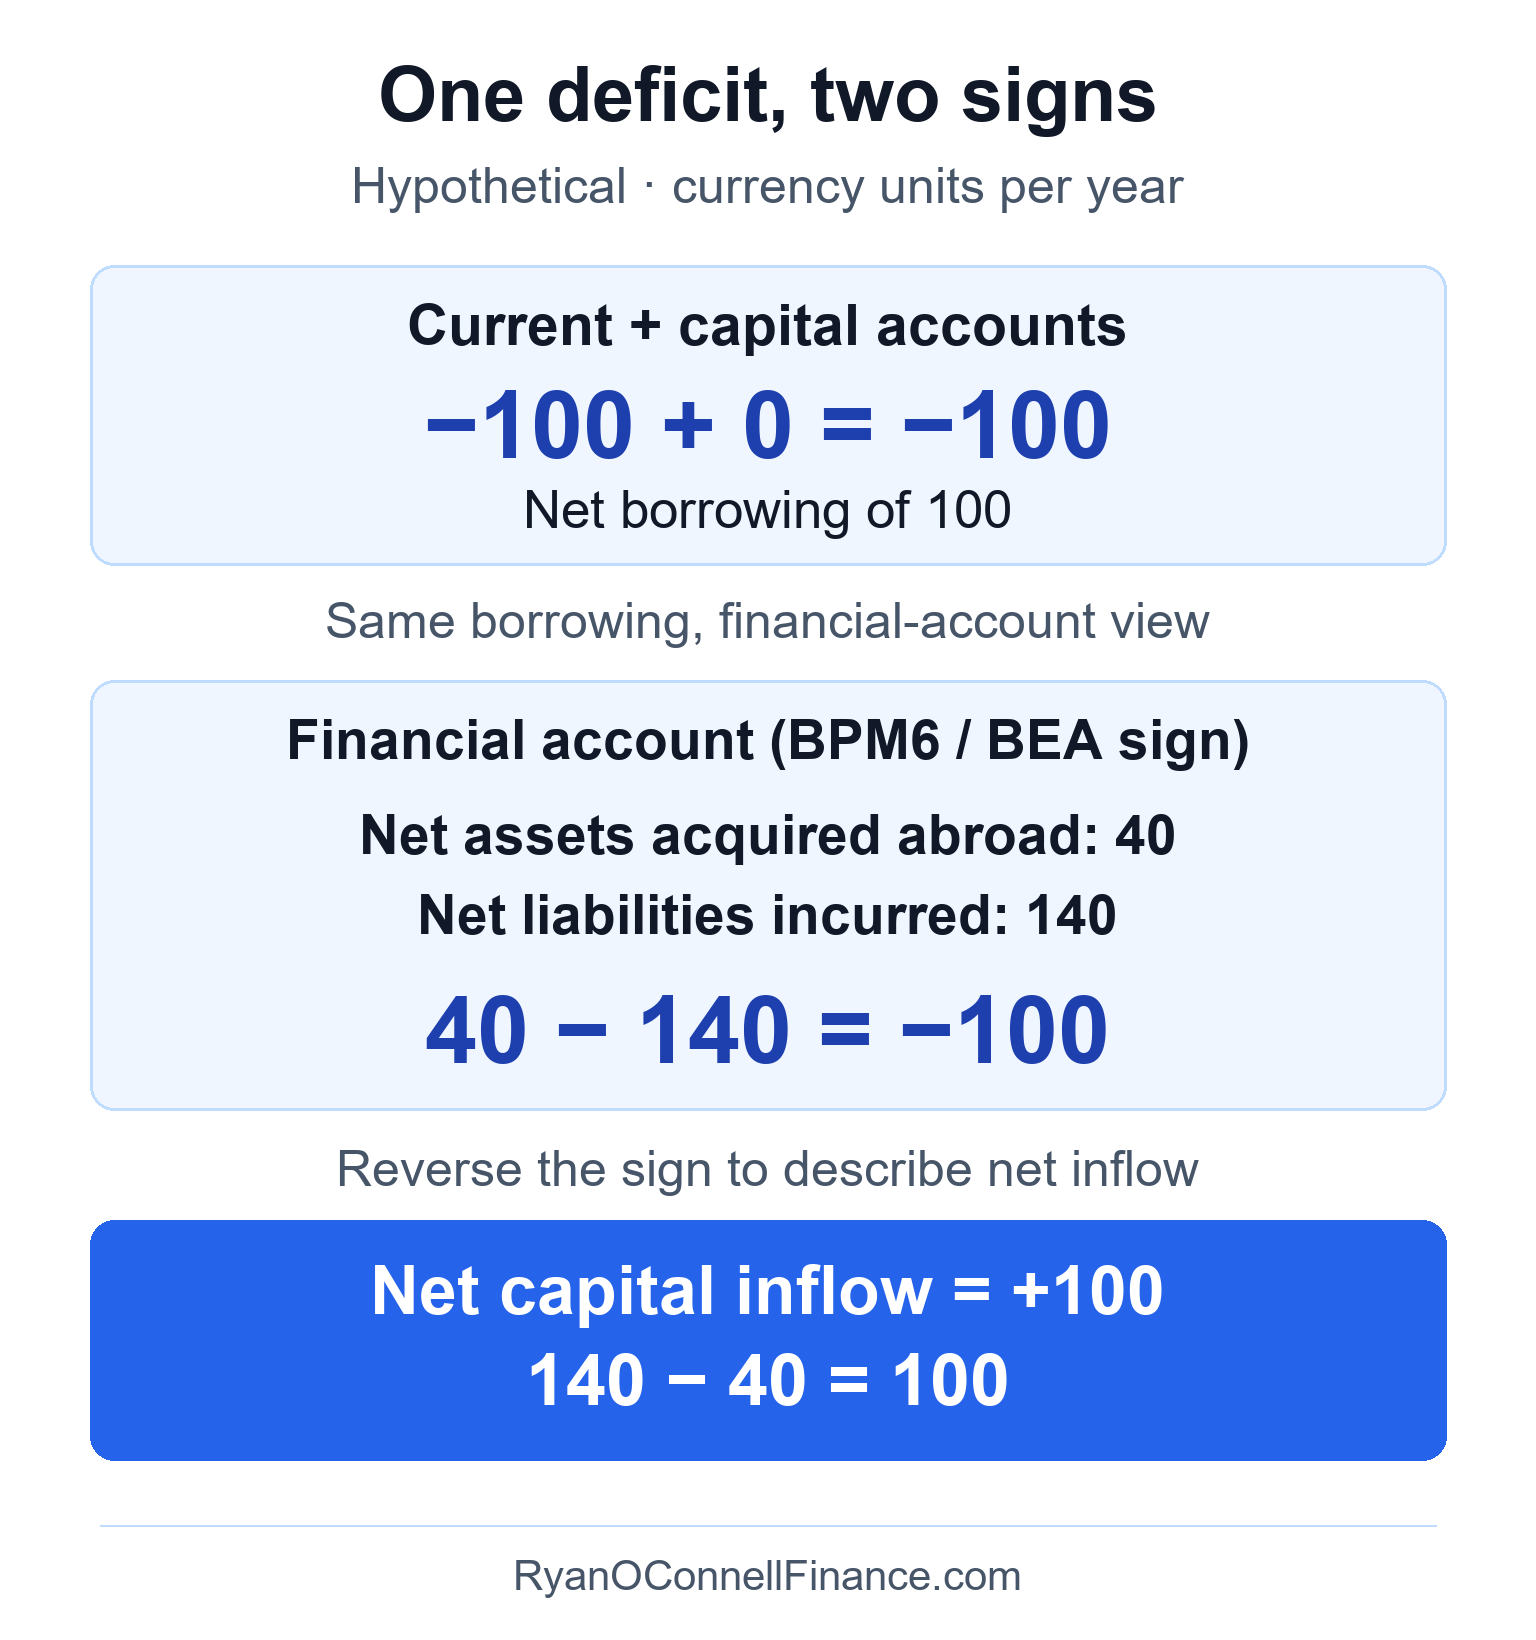
The financial-account balance of −100 and net capital inflow of +100 describe the same net borrowing, using opposite sign conventions. Both outward and inward investment can occur at the same time; the balance records their difference.
The capital account is usually small relative to the current and financial accounts. Some presentations instead define the financial balance as inflows minus outflows; with that sign, current account + capital account + financial balance = 0, ignoring measurement errors. Check the sign convention before comparing balances. See BEA’s international-account methods (September 2026, chapter 21).
Trade Balance vs Current Account
The trade balance and the current account are related but not identical. The trade balance measures only the trade in goods and services (exports minus imports). The current account includes the trade balance plus net primary income (including investment income and compensation of employees) and net current transfers (foreign aid, remittances). For most countries, the trade balance is the largest component of the current account, but the two figures can differ significantly.
| Measure | What It Includes | U.S. Example (2024) |
|---|---|---|
| Trade Balance (Goods Only) | Merchandise exports − merchandise imports | Large deficit (~$1.21 trillion) |
| Trade Balance (Goods & Services) | Goods + services exports − goods + services imports | Smaller deficit (~$918 billion) — U.S. runs a services surplus |
| Current Account Balance | Trade balance + net primary income + net current transfers | Deficit of ~$1.13 trillion — larger than goods & services deficit due to net transfer outflows |
Headlines about the “U.S. trade deficit” can refer to different measures, so always check whether the figure covers goods only, goods and services, or the full current account.
Net Capital Outflow
Net capital outflow (NCO) measures net acquisition of foreign financial assets minus net incurrence of liabilities to foreigners. Acquisitions are net of disposals, rather than gross purchases alone. It captures the net flow of capital across borders, with an outward-positive sign.
NCO includes both foreign direct investment (building a factory abroad or acquiring a foreign company) and foreign portfolio investment (buying foreign stocks or bonds). To connect NCO directly to net exports, the textbook model assumes zero net primary income, zero net current transfers, a zero capital-account balance, and no statistical discrepancy. Under those assumptions, the current account equals NX and the financial-account balance equals NCO.
Within this simplified framework, net exports equal net capital outflow: NX = NCO. This is an accounting identity, not a causal theory. A trade deficit (NX < 0) then corresponds to net borrowing (NCO < 0), while a trade surplus corresponds to net lending. In full balance-of-payments accounts, the combined current and capital accounts — rather than goods-and-services trade alone — match the financial-account balance, apart from measurement errors.
In that model, a trade deficit and a net capital inflow are two sides of the same coin. In the wider accounts, this correspondence concerns net external borrowing, including income and transfers. Spending, saving, investment, and exchange rates adjust jointly; the accounting identity alone does not establish which change caused the others (for more, see exchange rates in macroeconomics).
The Saving-Investment Identity
Under the same textbook assumptions, NX = NCO connects to the relationship between saving and investment. Starting from the GDP identity (Y = C + I + G + NX) and defining saving in this model as S = Y − C − G, we can derive:
A hypothetical example makes the financing gap visible:
| Accounting quantity | Amount (currency units/year) |
|---|---|
| Saving (S) | 80 |
| Investment (I) | 100 |
| Gap (S − I) | -20 |
Hypothetical annual flows; the simplified model sets net income, transfers, the capital-account balance, and measurement errors to zero.
Saving of 80 cannot cover domestic investment of 100, so net financing from abroad supplies the remaining 20. With the outward-positive sign, NX = NCO = −20 in this model.
The three general scenarios below use those same textbook assumptions.
| Scenario | Exports vs Imports | NX | NCO | Saving vs Investment |
|---|---|---|---|---|
| Trade Surplus | Exports > Imports | Positive | Positive (capital outflow) | S > I — surplus saving lent abroad |
| Balanced Trade | Exports = Imports | Zero | Zero | S = I — no net external financing; gross cross-border investment can continue |
| Trade Deficit | Imports > Exports | Negative | Negative (capital inflow) | S < I — borrowing from abroad to fund investment |
The saving-investment identity is an accounting identity, not a causal theory. It does not tell us which variable adjusts. In full national accounts, gross national saving (based on gross national disposable income) minus gross domestic investment corresponds to the current-account balance; net income and transfers can make that balance differ from NX. Whether a trade deficit reflects low national saving, a domestic investment boom, or some combination depends on the specific economic circumstances. For the mechanics of how saving and investment interact through interest rates in a closed economy, see our guide on the loanable funds market.
The Twin Deficits Hypothesis
The twin deficits hypothesis holds that government budget deficits and trade deficits tend to move together. The mechanism works through the saving channel: when the government runs a budget deficit, public saving (T − G) turns negative. Lower public saving reduces national saving unless offset by higher private saving. From the identity S = I + NCO, lower saving (holding investment constant) means lower NCO — more capital inflows and a wider trade deficit.
One possible chain, with mobile capital and a flexible exchange rate, runs: budget deficit → lower national saving → higher real interest rates (as the government competes for funds in the loanable funds market) → capital inflows attracted by higher returns → currency appreciation → exports become expensive, imports become cheap → trade deficit widens. This mechanism is closely related to the crowding out effect, where government borrowing displaces private investment.
The United States experienced a textbook case of twin deficits during the 1980s. Large tax cuts under the Reagan administration widened the budget deficit substantially. National saving fell by approximately 3.2 percentage points of GDP between 1980 and 1987. As predicted by the twin deficits mechanism, net capital inflows surged from about 0.5% to 3.1% of GDP over the same period, and the trade deficit widened correspondingly.
The 1990s counterexample: During the 1990s, the federal budget swung into surplus, yet the trade deficit persisted and widened. The reason: a domestic investment boom driven by the technology sector (investment rose from 13.4% to 17.7% of GDP) attracted massive foreign capital even as government saving improved. This shows that twin deficits are a tendency, not a law — private saving and investment behavior also matter.
The twin deficits hypothesis works through the saving channel. A sufficient private-saving increase can offset lower public saving, so the trade deficit need not widen. The specific Ricardian equivalence benchmark compares debt financing with current-tax financing of an unchanged government-spending path: under strong assumptions, households save the tax reduction to meet future taxes. It does not establish neutrality of additional government purchases, and its assumptions need not hold in practice. The broader policy effects of fiscal deficits are explored in monetary and fiscal policy and aggregate demand and aggregate supply.
Why the U.S. Runs a Persistent Trade Deficit
In 2024, the United States imported approximately $4.1 trillion in goods and services while exporting approximately $3.2 trillion, producing a goods-and-services trade deficit of roughly $918 billion. The broader current account deficit was approximately $1.13 trillion. For these real-world figures, net external borrowing corresponds to the broader current-plus-capital balance, with a statistical discrepancy in measured data; it is not exactly the goods-and-services trade deficit. Financial flows are net: U.S. residents can also acquire assets abroad.
| Item | Amount (2024, Approx.) |
|---|---|
| Goods & Services Exports | ~$3.2 trillion |
| Goods & Services Imports | ~$4.1 trillion |
| Trade Deficit (NX) | ~$918 billion |
| Current Account Deficit | ~$1.13 trillion |
Foreign investors channel these funds into U.S. Treasury securities, corporate bonds, equities, and real estate. Major creditor economies include Japan, China, the United Kingdom, and European economies. The U.S. has been the world’s largest net debtor since the mid-1980s.
Why can the United States sustain such large deficits? Three factors: the dollar’s role as the world’s primary reserve currency creates persistent foreign demand for dollar-denominated assets; the U.S. has the world’s deepest and most liquid capital markets; and foreign investors perceive U.S. assets — especially Treasuries — as relatively safe. The U.S. saving-investment shortfall corresponds to its broader current-account deficit, and net external financing fills the gap.
Note that the trade balance can adjust with a lag after exchange rate changes — a pattern known as the J-curve effect. When the dollar depreciates, the trade deficit may initially widen (because existing import contracts are now more expensive in dollar terms) before eventually narrowing as trade volumes adjust to the new exchange rate. For the full exchange rate adjustment mechanism, see exchange rates in macroeconomics.
Capital Flight
Capital flight occurs when investors abruptly reduce demand for a country’s assets and move funds abroad. Without offsetting flows, net capital outflow rises sharply. It can be highly destabilizing.
Capital flight is a large and sudden reduction in the demand for assets located in a country. Without offsetting flows, it increases net capital outflow. It can weaken the domestic currency, raise financing costs, and reduce domestic investment; the exchange-rate regime and policy response affect the outcome. The trigger is typically a loss of investor confidence caused by political instability, policy uncertainty, or fear of default or devaluation.
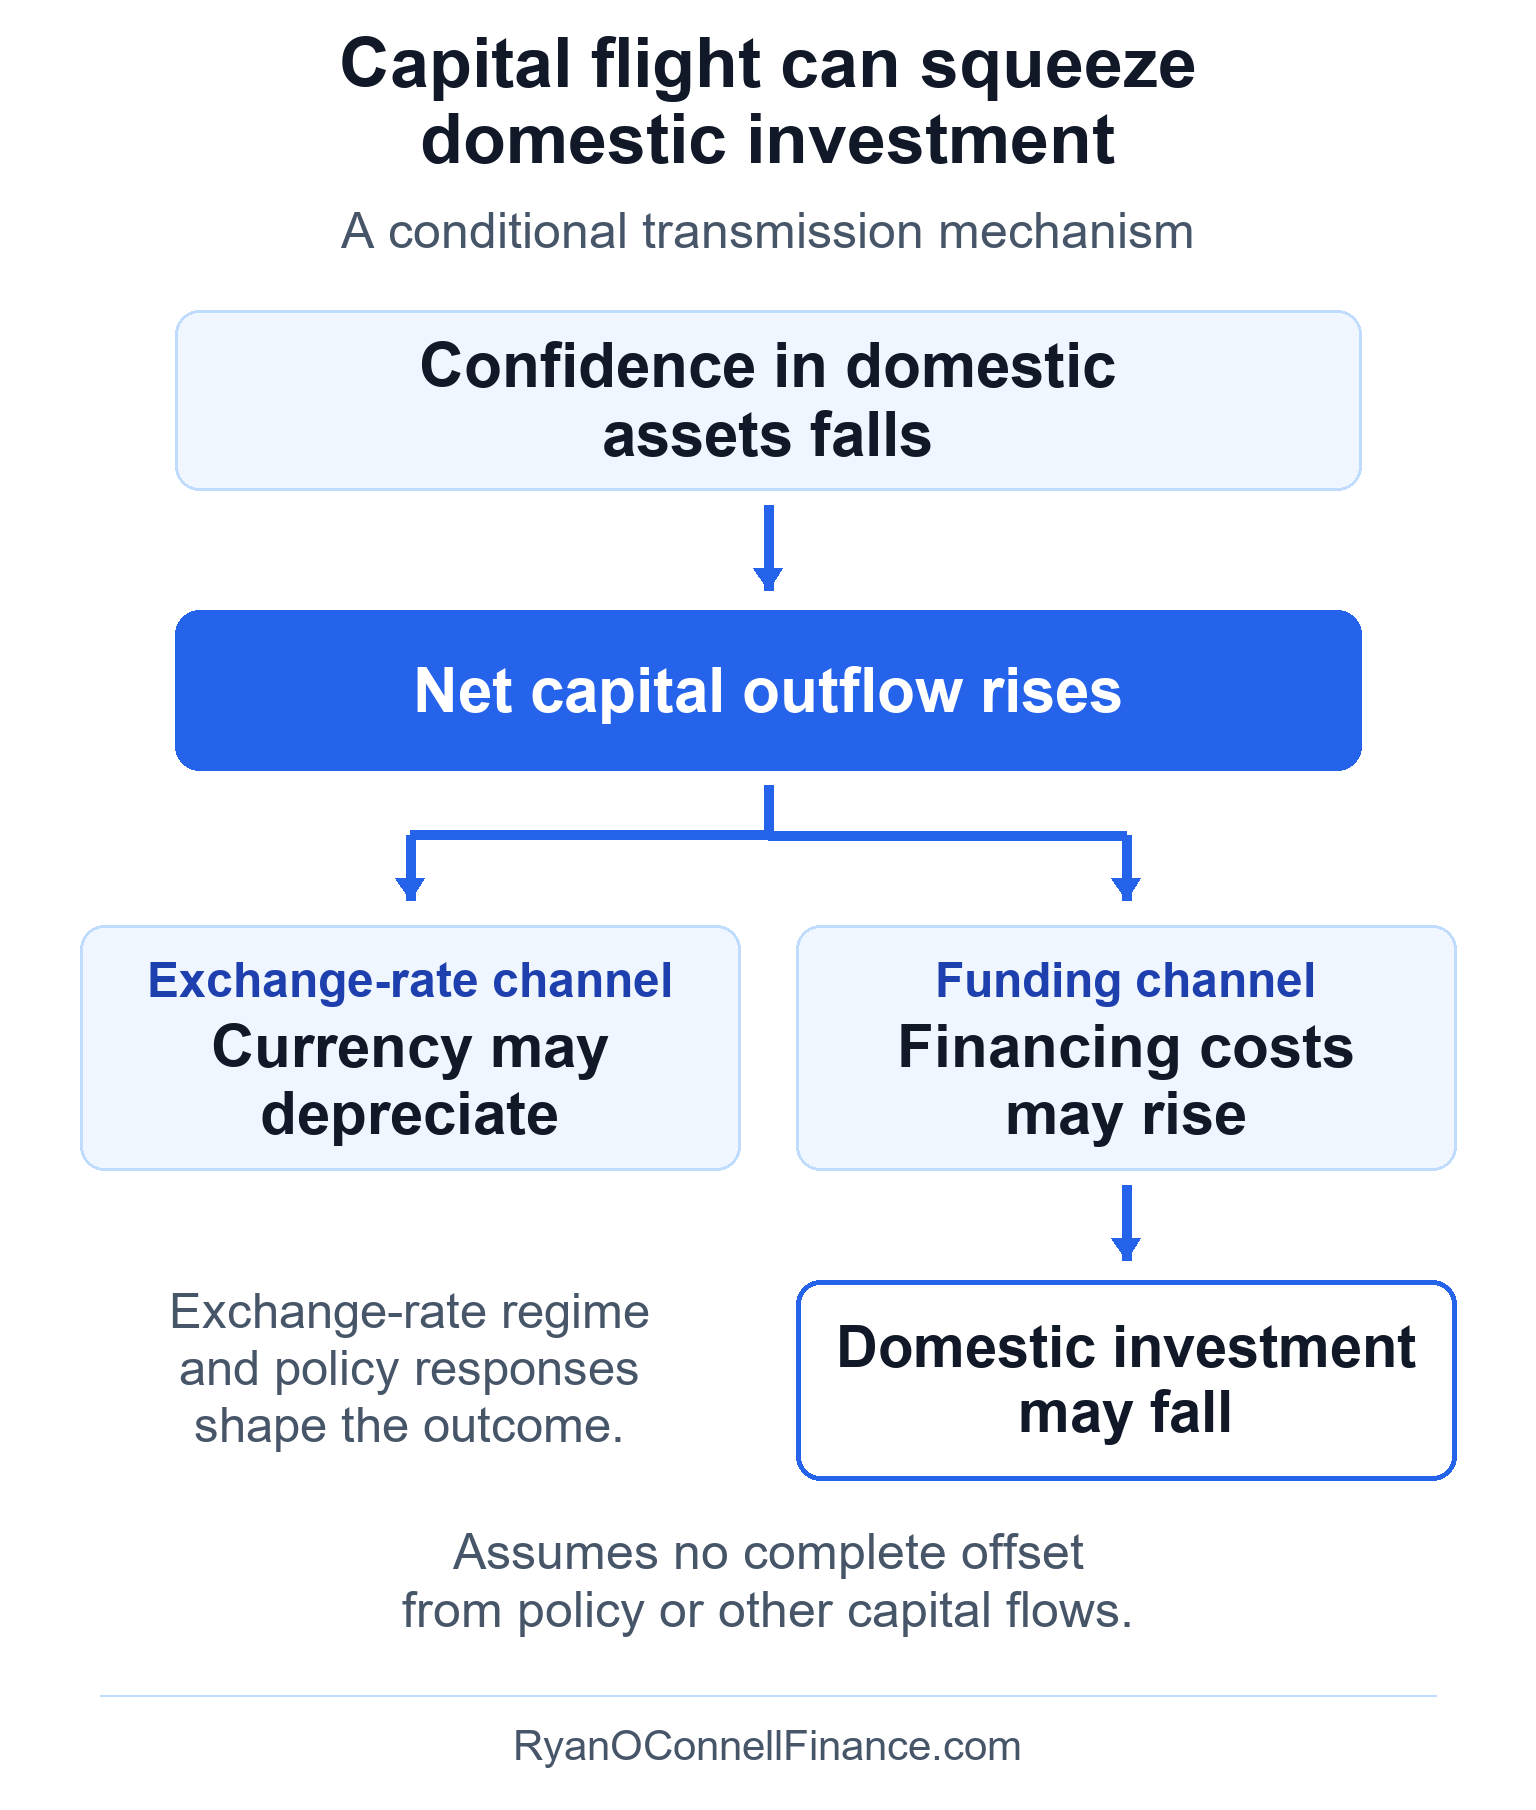
The funding channel explains why investment can contract when capital leaves. Currency depreciation is a separate possible response, rather than a necessary intermediate step between outflow and lower investment.
In late 1994, a series of political shocks — including the assassination of a presidential candidate and an armed uprising — triggered a massive flight of capital from Mexico. Investors rapidly sold Mexican assets and moved funds abroad.
The consequences were severe: the Mexican peso depreciated from 29 U.S. cents to 15 U.S. cents per peso. Short-term government bond rates surged from 14% to 70% as Mexico desperately tried to attract capital. Domestic investment collapsed, and GDP contracted sharply. The United States organized a $50 billion international bailout package to stabilize the peso and restore confidence.
The Asian Financial Crisis of 1997 followed a similar pattern on a larger scale. Capital that had flowed into Thailand, South Korea, Indonesia, and other East Asian economies during the early 1990s reversed suddenly. Currencies collapsed — the Thai baht lost more than half its value — interest rates surged, and the IMF organized emergency lending programs totaling tens of billions of dollars. The crisis demonstrated how quickly and violently capital flows can reverse when investor confidence breaks.
Russia’s 1998 crisis added another example: the government defaulted on its domestic debt, the ruble collapsed, and capital fled. These episodes illustrate a possible pattern — capital flight raises net outflow, weakens the currency, raises borrowing costs, and reduces domestic investment. Receiving economies may face capital inflows, appreciation pressure, and lower financing costs, depending on their policies and other shocks. Capital flight can violently unwind the international capital flows that finance external deficits — a dynamic closely related to the sudden reversal of carry trade positions.
Trade Surplus vs Trade Deficit
The balance relationships in these cards use the simplified textbook assumptions stated above; actual net lending or borrowing also includes income, transfers, and the capital account.
Trade Surplus (NX > 0)
- Exports exceed imports
- Net capital outflow is positive (NCO > 0)
- Country is a net lender to the rest of the world
- National saving exceeds domestic investment (S > I)
- An increase in net capital outflow may create depreciation pressure, with other conditions held fixed
- Examples: Germany, Japan, China
- Not inherently “good” — may reflect weak domestic demand or an undervalued currency
Trade Deficit (NX < 0)
- Imports exceed exports
- Net capital inflow (NCO < 0)
- Country is a net borrower from the rest of the world
- Domestic investment exceeds national saving (S < I)
- An increase in net capital inflow may create appreciation pressure, with other conditions held fixed
- Examples: United States, United Kingdom
- Not inherently “bad” — may reflect strong investment opportunities attracting foreign capital
Whether a surplus or deficit is healthy depends entirely on context. A trade deficit driven by a domestic investment boom (like the U.S. in the 1990s) reflects economic strength — foreign investors want to participate in the country’s growth. A deficit driven by government dissaving (like the U.S. in the 1980s) raises concerns about long-run fiscal sustainability. Similarly, a surplus can reflect either prudent saving (building wealth for the future) or weak domestic demand and insufficient investment (Japan’s “lost decades”).
Common Mistakes
1. Treating trade deficits as always bad. A trade deficit can reflect that a country has strong investment opportunities attracting foreign capital. The United States ran large trade deficits during the 1990s tech boom — not because of economic weakness, but because foreign investors wanted to participate in U.S. growth. The external deficit accompanied substantial net capital inflows. Context determines whether a deficit is healthy or unhealthy.
2. Confusing bilateral trade balances with the overall trade balance. Politicians often focus on the bilateral deficit with a specific country (for example, the U.S. deficit with China). Economists emphasize that the overall trade balance is what matters economically, because trade is multilateral — a country may run deficits with some partners and surpluses with others, and it is the overall current account, rather than any bilateral trade balance, that connects to national saving minus domestic investment.
3. Assuming trade policy can fix the trade balance. In the simplified NX = S − I framework, the overall trade balance cannot change if saving and investment are unchanged. A tariff may reduce imports of specific goods, while exchange-rate adjustments can offset some of the direct effect. Trade policy can also affect saving and investment, so the identity alone is not a causal prediction of a tariff’s total effect.
4. Ignoring that trade deficits and capital inflows are two sides of the same coin. Under the simplified NX = NCO assumptions, a trade deficit corresponds to net capital inflow; in full accounts, financing matches the combined current and capital accounts. Eliminating a net inflow does not eliminate gross foreign investment — equal inflows and outflows can continue in both directions.
5. Confusing the trade balance with national competitiveness. A strong economy can run trade deficits (the U.S.) while a weak economy can run surpluses (Japan during its lost decades ran surpluses because weak domestic investment meant excess saving flowed abroad). The simplified model links the trade balance to the saving-investment gap; full accounts link that gap to the current account. Neither balance alone measures a country’s ability to compete in global markets.
6. Confusing the trade balance with the current account balance. The trade balance measures only goods and services trade. The current account also includes net primary income and net current transfers. For the United States in 2024, the goods-only trade deficit was approximately $1.21 trillion while the current account deficit was approximately $1.13 trillion — the difference reflects services trade, net primary income, and net current transfers. The two measures can tell different stories, so it matters which one is being cited.
Limitations of the Trade Balance Framework
The balance of payments framework and the saving-investment identity provide powerful tools for understanding international trade and capital flows, but the underlying data and models have important limitations.
1. Statistical discrepancy. In practice, the balance of payments accounts do not balance exactly due to measurement errors — the statistical discrepancy can be significant, especially for countries with large informal economies or complex financial flows. Official data revisions can also change the picture substantially after initial release.
2. Business cycle effects. The trade balance is heavily influenced by the business cycle. Imports fall during recessions as domestic demand weakens, which can temporarily improve the trade balance without reflecting any structural change. Comparing trade balances across different phases of the cycle can be misleading.
3. Exchange rate volatility. Trade balances measured in domestic currency terms can change significantly due to exchange rate movements alone. A depreciating dollar makes foreign goods more expensive in dollar terms, initially widening the measured trade deficit (the J-curve effect) even if trade volumes have not yet adjusted.
4. Underground and informal trade. Official statistics do not capture smuggling, informal cross-border trade, or trade mis-invoicing (over- or under-reporting trade values to evade taxes or move capital). These unmeasured flows can be substantial in some economies and distort the official trade balance picture.
Frequently Asked Questions
Disclaimer
This article is for educational and informational purposes only and does not constitute financial or investment advice. Trade data cited are approximate figures from Bureau of Economic Analysis (BEA) and other government sources for the years indicated; they are subject to revision. The identities and models described are standard macroeconomic frameworks based on Mankiw’s “Principles of Macroeconomics”; real-world international trade and finance are more complex. Always consult primary sources and qualified professionals for policy analysis and investment decisions.
Keep reading
Next in this series
Part 25 of 33 in Economics Essentials
Exchange Rate Determination: Nominal & Real Exchange RatesMore in Economics
-
Supply and Demand: How Markets Determine Prices
Supply and demand is the foundational economic model explaining how prices are set, how markets reach equilibrium, and what causes surpluses and shortages.
-
Gross Domestic Product (GDP)
Gross domestic product (GDP) is the total market value of all final goods and services produced within a country.
-
Inflation & Consumer Price Index (CPI) Explained: How It Works & Why It Matters
Learn what inflation is, how the Consumer Price Index (CPI) measures it, and why it matters for investment decisions.