Margin Trading: How It Works, Margin Calls, and Real Risk Examples
Table of Contents
Margin trading is one of the most powerful—and risky—tools in an investor’s toolkit. By borrowing money from your broker to buy securities, you can amplify your gains. But leverage cuts both ways: it magnifies losses just as much as gains, and in extreme scenarios, you can lose more than you initially deposited. This guide covers how margin trading works, how to calculate when you’ll face a margin call, and the real risks that every margin trader must understand.
How Margin Trading Works
Margin trading allows you to borrow money from your broker to purchase securities, using your existing cash and securities as collateral. Instead of paying the full purchase price upfront, you put up a percentage (typically 50% in the U.S.) and borrow the rest from your broker.
Margin trading is the practice of buying securities by borrowing part of the purchase price from your broker. Your investment is split into two components: your own cash (equity) and borrowed funds (the margin loan). The borrowed funds accrue interest daily and must be repaid when you sell the securities.
Here’s a simple example: You want to buy $20,000 worth of stock but only have $10,000 in cash. With a margin account, you can borrow the additional $10,000 from your broker, buy the full $20,000 position, and pay interest on the $10,000 loan. If the stock rises, your gains are amplified. If it falls, your losses are amplified—and if it falls too far, you’ll face a margin call or forced liquidation.
Margin trading is fundamentally different from simply having financial leverage as a concept. This article focuses on the mechanics, regulations, and risks specific to margin accounts, while the financial leverage article covers the broader theoretical framework of leverage in investing.
U.S. Margin Rules and Requirements
Margin trading in the United States is governed by a combination of federal regulations, self-regulatory organization (SRO) rules, and individual broker policies. Understanding these layers is critical because your broker’s requirements can—and often do—exceed the regulatory minimums.
Regulation T (Reg T)
Regulation T is a Federal Reserve rule that sets the initial margin requirement at 50% for margin-eligible securities. This means you must pay for at least half the purchase price with your own cash. For a $20,000 stock purchase, you must deposit $10,000 and can borrow up to $10,000.
FINRA Minimum Maintenance Margin
The Financial Industry Regulatory Authority (FINRA) requires a maintenance margin of at least 25% for long stock positions. This is the minimum equity you must maintain relative to the current market value of your position. If your equity percentage falls below this threshold, your broker can issue a margin call or force-liquidate your position.
Important: 25% is just the floor. Most brokers set their “house” maintenance requirements higher—commonly 30% to 40%.
Broker House Rules
Brokers have the authority to set stricter requirements than Reg T and FINRA minimums. Common house rules include:
- Higher maintenance margins: 30% or 40% instead of 25%
- Minimum account balance: $2,000 equity required to open a margin account (FINRA rule)
- Security-specific requirements: Certain stocks may have higher margin requirements based on liquidity, volatility, or price
Security-Specific Margin Requirements
| Security Type | Typical Initial Margin | Typical Maintenance Margin |
|---|---|---|
| Standard stocks (liquid, over $5) | 50% | 25%-30% |
| Low-priced stocks (under $5) | 100% (no margin) | 100% |
| Leveraged ETFs (2x, 3x) | 50%-100% | 75%-100% |
| Concentrated positions (>20% of account) | 50%+ | 30%-50% |
| High-volatility stocks | 50%-100% | 30%-100% |
Your broker can change margin requirements at any time—even intraday—without advance notice. During periods of market volatility, brokers frequently increase maintenance requirements on specific securities or across entire accounts. When this happens, you may face an immediate margin call even if your positions haven’t moved.
Additionally, when a margin call is triggered, your broker has complete discretion: they can liquidate positions without prior warning, choose which securities to sell, and execute at prevailing market prices. You remain liable for any remaining debit balance after liquidation.
Initial Margin vs Maintenance Margin
The two most important margin concepts are initial margin and maintenance margin. Confusing these terms is one of the most common mistakes new margin traders make.
Initial Margin
- Purpose: Minimum equity to OPEN a position
- Reg T requirement: 50% for margin securities
- Example: To buy $20,000 stock, you need $10,000 cash
- Applies only at purchase
- Can fall below initial margin after purchase without triggering margin call
Maintenance Margin
- Purpose: Minimum equity to KEEP a position open
- FINRA minimum: 25% (brokers often use 30%+)
- Example: $20,000 position requires $5,000-$6,000 equity minimum
- Applies continuously after purchase
- Falling below can lead to a margin call or forced liquidation
How Equity Percentage Changes
Your equity percentage is calculated as:
For a hypothetical purchase of 200 shares at $100, funded by $10,000 cash and a $10,000 loan, the loan stays fixed as the stock price changes. This figure uses a 25% maintenance requirement and excludes interest.
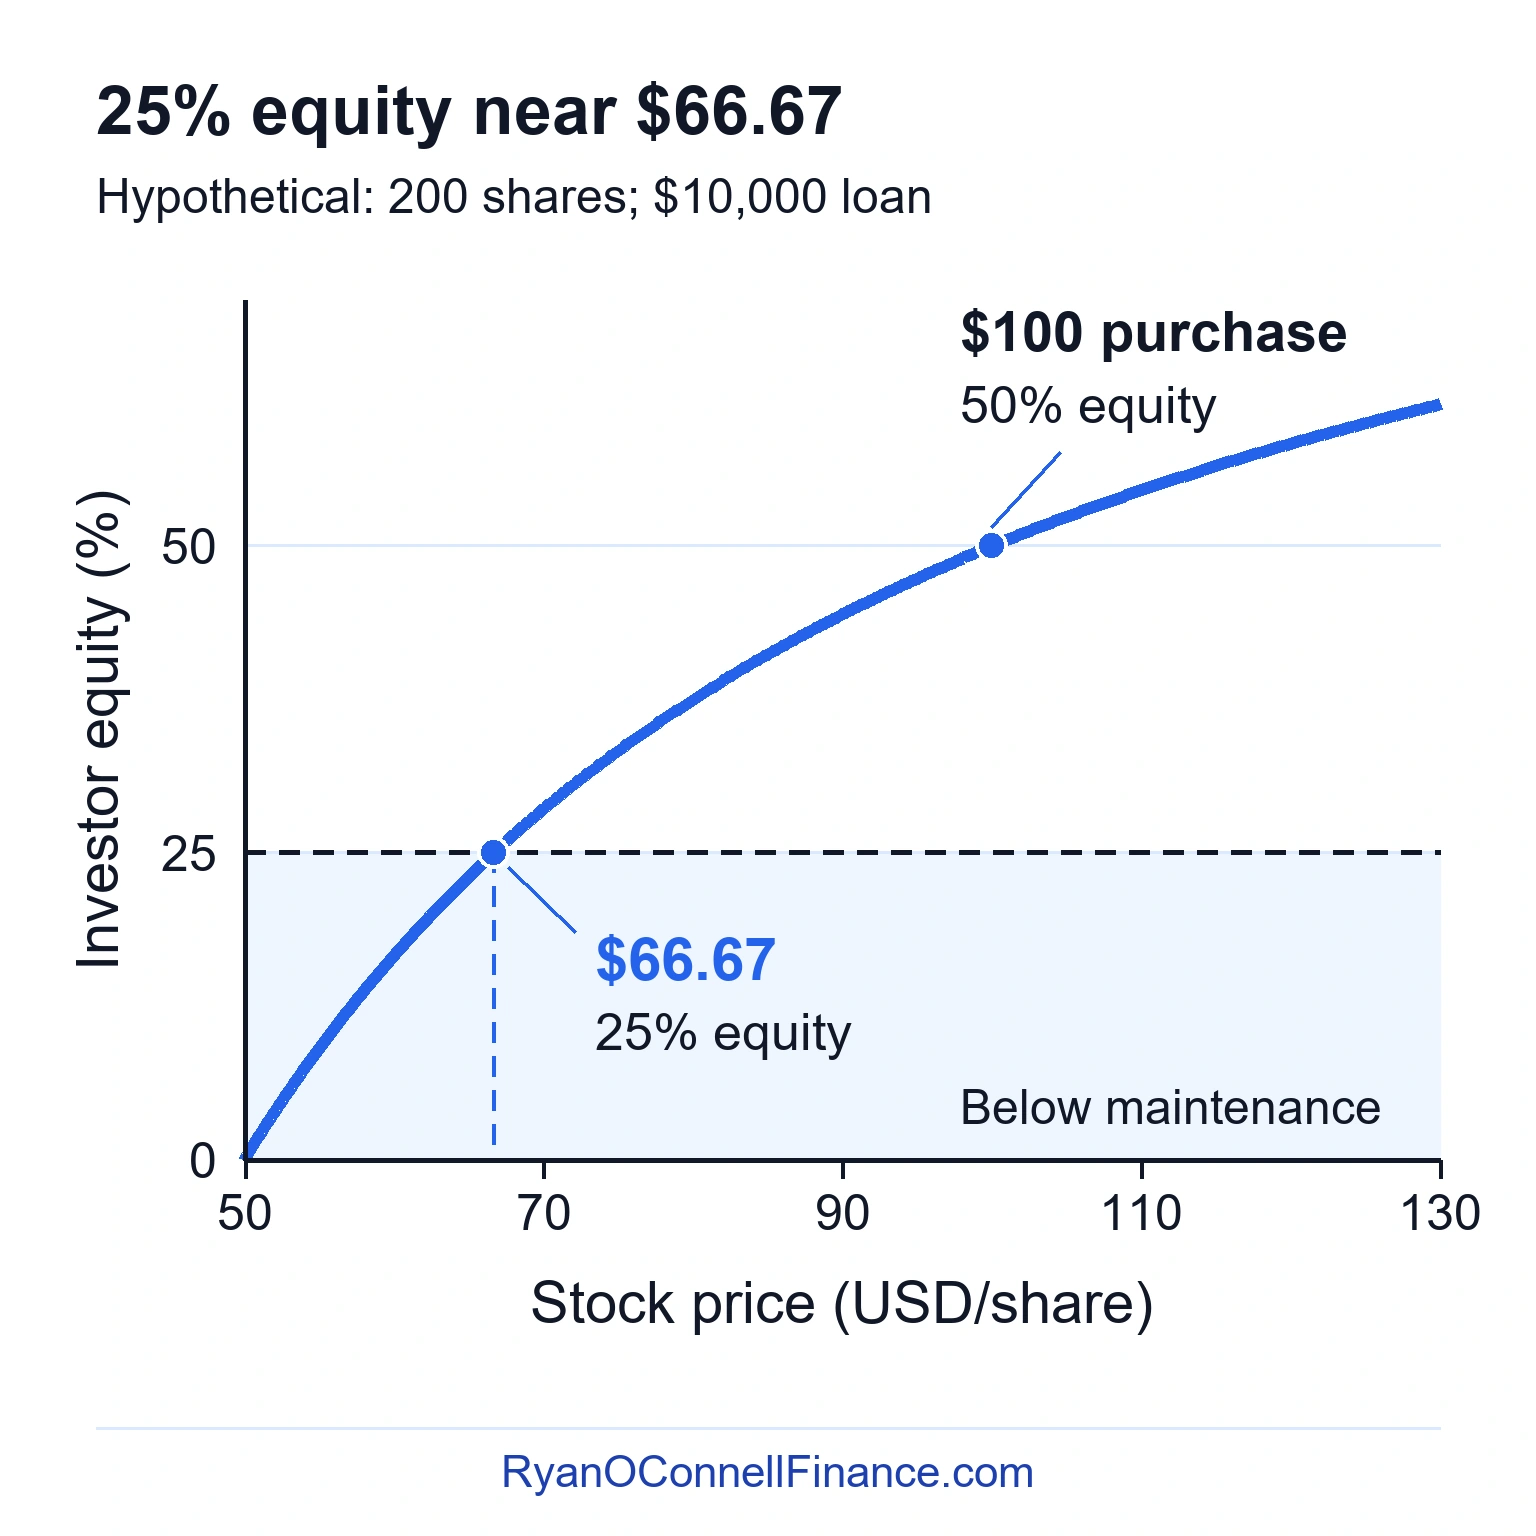
At $80 per share, market value is $16,000 and equity is $6,000, or 37.5%: below the initial 50% requirement but above 25% maintenance. The threshold is $66.666… per share, rounded to $66.67; falling below it permits a margin call or liquidation, rather than guaranteeing a sale at that price.
Margin Call Formula (With Example)
The single most important calculation in margin trading is determining the margin call price—the threshold stock price at which your equity percentage equals the maintenance requirement. Below it, your broker can issue a margin call or liquidate; the formula does not predict an execution price. Calculate this threshold before entering a trade.
Where:
- Purchase Price: The price per share you bought at
- Initial Margin: The percentage of equity you put up (e.g., 0.50 for 50%)
- Maintenance Margin: The broker’s maintenance requirement (e.g., 0.25 for 25%)
Step-by-Step Derivation
Why does this formula work? Let’s derive it:
- At the margin call price, your equity must equal exactly the maintenance margin percentage of the market value.
- Equity = Market Value – Loan Amount
- Loan Amount = Purchase Price × Number of Shares × (1 – Initial Margin)
- Set Equity / Market Value = Maintenance Margin and solve for the price
The result: Margin Call Price = Purchase Price × (1 – Initial Margin) / (1 – Maintenance Margin)
Setup:
- Buy 200 shares at $100/share = $20,000 total
- Initial margin: 50% → you pay $10,000 cash, borrow $10,000
- Maintenance margin: 25% (FINRA minimum; many brokers use 30%+)
Calculate margin call price:
Margin Call Price = $100 × (1 – 0.50) / (1 – 0.25)
= $100 × 0.50 / 0.75
= $66.67 per share
Verification: Using the unrounded threshold of $66.666…/share:
- Market Value = 200 shares × $66.666… ≈ $13,333.33
- Loan = $10,000 (unchanged)
- Equity = $13,333.33 – $10,000 = $3,333.33 (rounded)
- Equity % = 25% at the unrounded threshold; approximately 25.0% at $66.67
Key insight: A decline of about 33.3% reaches the 25% maintenance threshold before interest. If interest is added to the loan instead of paid separately, the loan balance and threshold rise.
Calculate your margin call price BEFORE entering the trade. Know exactly how much downside you can tolerate. If the margin call price is only 10-15% below your purchase price, you’re over-leveraged and should reduce your position size or use less margin.
What Happens During a Margin Call
When your equity percentage falls below the maintenance margin, you have three options:
- Deposit more cash immediately: Add funds to bring your equity back above the maintenance threshold
- Sell securities yourself: Liquidate some or all of your position to reduce the loan amount
- Broker force-liquidates (most common): The broker sells your securities at prevailing market prices
Your broker has complete control over liquidation. When a margin call is triggered, the broker can:
- Liquidate positions immediately without prior notice
- Choose which securities to sell (you have no say)
- Execute at current market prices, regardless of slippage or illiquidity
- Sell as much as necessary to restore the account to compliance
Margin calls happen at the worst possible time—during maximum drawdown periods when prices are at their lowest. You’re forced to sell at exactly the wrong time, locking in permanent losses that a cash-account investor could simply wait out.
Margin Trading Example (Gains and Losses)
Compare three hypothetical outcomes for the same initial position: buy 200 shares at $100 per share ($20,000), using $10,000 cash and a $10,000 margin loan. The chart compares returns on the initial cash before interest, fees, and taxes. A cash account buys 100 shares with the same $10,000.
| Stock move (%) | Margin (%) | Cash (%) |
|---|---|---|
| Gain: +30% | 60 | 30 |
| Threshold: −33.3% | -66.7 | -33.3 |
| Gap: −60% | -120 | -60 |
Hypothetical, 50% initial margin and fixed $10,000 loan. Threshold returns use the unrounded 25% maintenance price; sale prices are assumptions.
The same price move affects twice as much stock in the margin account. A 60% gap down produces a 120% loss on the initial deposit because the loan does not shrink with the shares.
Scenario 1: +30% Stock Gain
At $130 per share, selling for $26,000 and repaying the $10,000 loan leaves $16,000: a 60% gross return on your $10,000. Now assume a hypothetical 11.8% annual interest rate for six months, with interest paid separately. Simple interest is $10,000 × 0.118 × 0.5 = $590. Net proceeds are $15,410, a 54.1% net return, compared with 30% in the cash account. Capitalized interest, fees, and taxes would change the result.
Scenario 2: -33.3% Stock Loss (Maintenance Threshold)
At the unrounded 25% maintenance price of $66.666… per share, the position is worth about $13,333.33 and equity is about $3,333.33. Selling there would lock in a 66.7% loss before interest. The displayed $66.67 price is rounded, and a broker’s actual liquidation price can differ. Interest paid while holding the position makes the loss larger; adding it to the loan also changes the threshold.
Scenario 3: -60% Gap-Down (YOU CAN LOSE MORE THAN DEPOSITED)
If the stock gaps to $40 and the broker sells there, the $8,000 proceeds cannot cover the $10,000 loan. You lose your $10,000 deposit and still owe $2,000: a $12,000 total loss, or -120%, before interest. A price gap can skip the maintenance threshold. The cash account’s long-stock loss would be 60%.
Margin interest accrues daily. At the example’s hypothetical 11.8% annual rate on a constant $10,000 loan, simple-interest estimates are $3.23 per day, $98 per average month, and $1,180 per year. That annual cost is 11.8% of the initial $10,000 cash even if the stock is flat. If unpaid interest is added to the loan, future interest charges increase.
Margin Trading vs Cash Account
Should you trade on margin or stick with a cash account? Understanding the trade-offs is essential for making an informed decision.
Margin Trading
- Amplified gains: 2x leverage with 50% margin (30% stock gain → 54.1% return after the example’s interest)
- Amplified losses: CAN lose more than deposited in gap scenarios
- Interest costs: 11-12% annual typical for small balances
- Margin call risk: Forced liquidation without notice during drawdowns
- Can short sell: Borrow shares to bet on price declines
- Requirements: $2,000 minimum, broker approval, ongoing monitoring
- Daily interest accrual: Interest accrues even on losing positions
Cash Account
- No leverage: Returns match stock performance (30% gain → 30% return)
- Limited losses: Can’t lose more than invested (except with options)
- No interest costs: Zero financing costs
- No margin calls: Can hold through drawdowns indefinitely
- Cannot short sell: Margin account required in the U.S.
- No special requirements: No minimums, no approval process
- No ongoing costs: No daily interest accrual
The key advantage of margin is amplified gains and the ability to short sell. The key disadvantages are amplified losses, interest costs, and forced liquidation risk. For long-term buy-and-hold investors, cash accounts are almost always superior. For short-term tactical traders with strict risk management, margin can be appropriate—but only if you fully understand and accept the risks.
When Does Margin Trading Make Sense?
Margin trading is not appropriate for most investors, but there are specific scenarios where it can be used effectively:
- Short-term tactical trades: High-conviction positions with a defined exit strategy and stop-loss
- Arbitrage opportunities: Low-risk, time-sensitive strategies that capitalize on pricing inefficiencies
- Professional traders: Those with sophisticated risk management systems, real-time monitoring, and experience with leverage
- Very liquid positions: Highly liquid securities where forced liquidation won’t result in significant slippage
Margin trading is NOT appropriate for:
- Long-term buy-and-hold investing: Interest costs compound over time and erode returns
- Volatile or speculative stocks: High volatility increases margin call risk exponentially
- Investors who can’t monitor positions daily: Margin accounts require constant attention
- Anyone uncomfortable with forced liquidation: If the thought of your broker selling your positions without notice keeps you up at night, don’t use margin
- Retirement accounts: Most retirement accounts don’t allow margin for good reason—the risk of permanent capital loss is too high
Understanding margin trading is critical for portfolio risk management. Our Portfolio Analytics & Risk Management course covers leverage, risk metrics, and portfolio construction strategies in depth.
Common Mistakes
Even experienced traders make costly mistakes with margin. Here are the seven most common errors and how to avoid them:
1. Ignoring Margin Interest Costs
At the hypothetical 11.8% rate and a constant $10,000 loan, simple interest is $1,180 per year, or about $3.23 per day. On a flat stock, that is an 11.8% loss on the initial $10,000 cash; capitalizing interest would increase the cost. Interest accrues daily, including on losing positions.
Solution: Factor interest costs into your expected return calculations. Keep the return and financing bases consistent. For example, a hypothetical 15% stock gain on a $20,000 position earns $3,000. Subtracting $1,200 of simple annual interest on a $10,000 loan leaves $1,800, or an 18% return on the initial $10,000 cash, before other costs.
2. Over-Leveraging
Using the maximum 50% margin on every position leaves no buffer for volatility. One bad trade triggers a margin call and forced liquidation across your entire account.
Solution: Use significantly less leverage than the maximum. Consider using only 20-30% margin instead of 50%, which provides a cushion for market fluctuations. Your gains will be smaller, but you’ll avoid catastrophic forced liquidation.
3. Not Understanding Forced Liquidation
Many traders assume they’ll receive a warning or get to choose which positions to sell during a margin call. In reality, brokers can liquidate immediately without notice, choose which securities to sell, and execute at market prices (possibly during panic selling).
Solution: Understand that you have zero control once a margin call is triggered. Broker discretion is absolute. Plan for this by using less leverage and setting your own stop-losses before the broker forces your hand.
4. Treating Margin Like Free Money
Margin is a loan with interest, not extra capital. You’re paying to borrow, and the cost compounds (typically monthly when posted).
Solution: View margin as a short-term financing tool with a specific purpose, not as “extra buying power.” Every dollar borrowed has a cost.
5. Ignoring the Margin Call Formula
Most traders never calculate the price level that triggers a margin call before entering a trade. This is the single most important number to know.
Solution: Before every margin trade, calculate: Margin Call Price = Purchase Price × (1 – Initial Margin) / (1 – Maintenance Margin). Know exactly how much downside you can tolerate.
6. Assuming 25% Applies to All Positions
The 25% FINRA minimum is just the floor. Many brokers use 30-40% as house rules. Low-priced stocks, leveraged ETFs, and concentrated positions often require 50-100% maintenance. Requirements can change intraday without notice.
Solution: Check your broker’s margin handbook for security-specific requirements. Don’t assume 25% applies to everything you hold. During volatile markets, brokers may increase requirements on specific stocks—sometimes to 100%, effectively forcing you to close the position.
7. Ignoring Gap and Slippage Risk During Forced Liquidation
Your broker liquidates at prevailing market prices. Gaps, illiquidity, and volatility can make execution far worse than expected. You bear all slippage costs. In extreme gaps, you can end up owing money even after losing your entire deposit.
Solution: Understand that forced liquidation doesn’t happen at favorable prices. It happens when the market is in turmoil, spreads are wide, and liquidity is poor. Factor this into your risk assessment. If you’re trading an illiquid stock on margin, the gap risk is enormous.
Can You Lose More Than You Invest on Margin?
This is the question every margin trader must answer before opening a margin account: Can you lose more than you initially deposited?
The answer is YES.
While long stock positions theoretically have limited downside (a stock can’t go below $0), in practice you can lose more than your initial deposit due to:
- Overnight gaps: The stock gaps down before your broker can liquidate (earnings miss, fraud announcement, trading halt)
- Illiquid markets: Forced liquidation executes at severely depressed prices with wide bid-ask spreads
- Fast-moving crashes: The broker can’t liquidate fast enough during flash crashes or circuit breaker halts
- You remain liable: If liquidation proceeds don’t cover the loan, you owe the difference to your broker
Hypothetical Example: -120% Loss
Suppose you deposit $10,000, borrow $10,000, and buy 200 shares at $100. Overnight news sends the stock straight to $40 before the broker can sell. If the broker liquidates all 200 shares at $40, this is the remaining debt before interest:
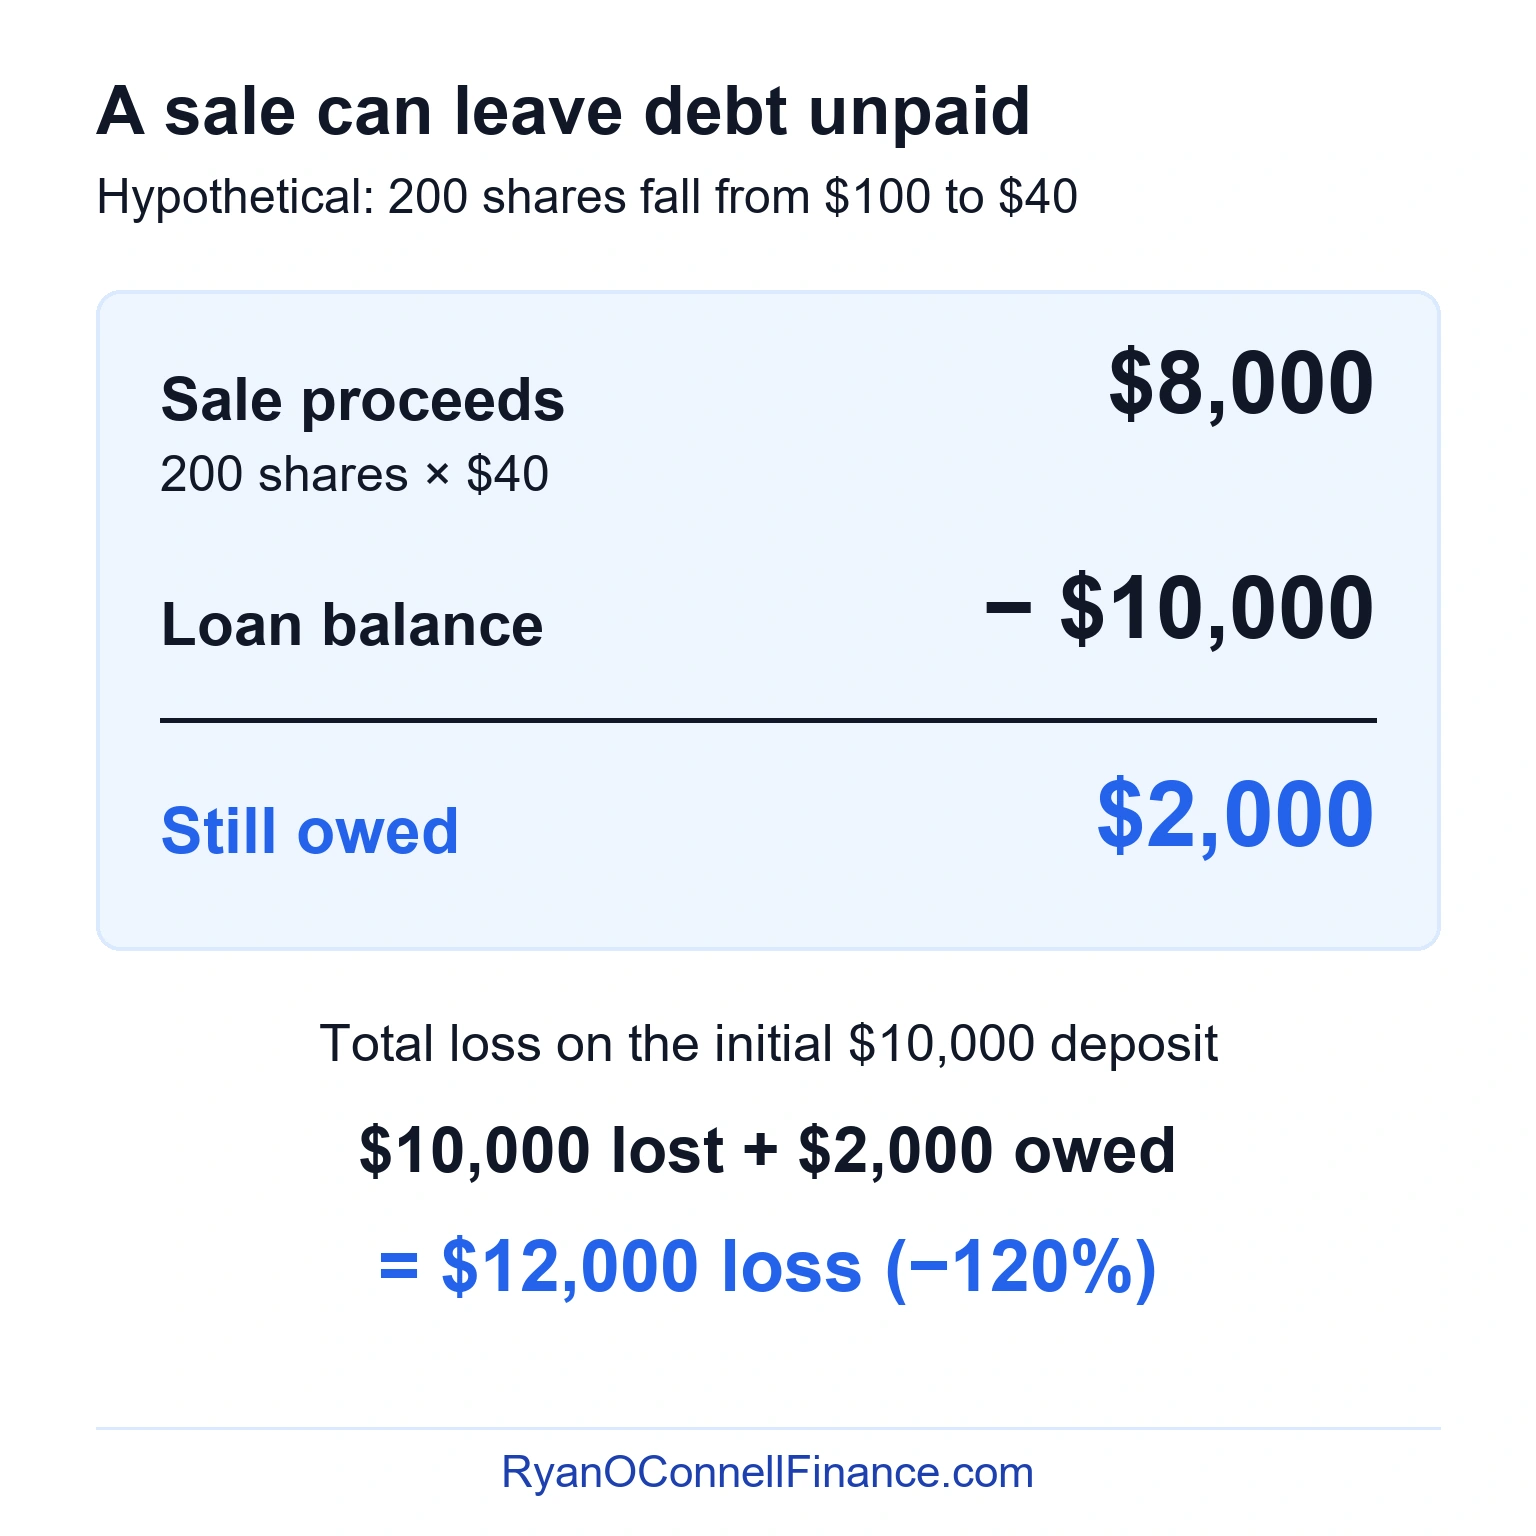
The broker’s loan survives the fall in the shares: the $2,000 debt is additional to the $10,000 deposit already lost. You remain liable for that debit balance, and the broker may demand payment or pursue collections or legal action.
Cash accounts cannot have this problem. The worst you can lose in a cash account is 100% of your investment (the stock goes to $0). With margin, losses can exceed 100% because you owe the loan regardless of what happens to the stock price.
Limitations and Risks
Beyond the risk of losing more than you invest, margin trading has several structural limitations that every trader must understand:
Forced Selling at the Worst Time
Margin calls are triggered during market drawdowns when prices are at their lowest. You’re forced to sell at exactly the wrong time, locking in permanent losses that a cash-account investor could simply wait out. This is perhaps the most insidious risk of margin: it removes your ability to be patient during temporary market declines.
Interest Costs Compound
Even if the stock goes sideways, interest accrues. At the example’s hypothetical 11.8% annual rate, one average month’s simple interest on a constant $10,000 loan is about $98, or 0.98% of the initial $10,000 cash. Adding unpaid interest to the loan increases future charges, so financing can erode returns even in a flat market.
Psychological Pressure
Watching a leveraged position move against you is psychologically stressful and can lead to poor decisions. The fear of a margin call may cause you to sell prematurely or panic during normal volatility. Leverage amplifies not just gains and losses, but also emotional responses.
Broker Discretion Is Absolute
Your broker can change margin requirements intraday without advance notice, especially during market volatility. A stock that was marginable at 30% maintenance in the morning might suddenly require 100% (no margin) by afternoon due to increased volatility or news. When this happens, you face an immediate margin call even if the position hasn’t moved against you.
Volatility Exposure Amplified
Leveraged positions have approximately 2x exposure to standard deviation risk. If a stock has 30% annual volatility, a 2x leveraged position effectively has 60% volatility. This dramatically increases the probability of hitting your margin call trigger price during normal market fluctuations.
VaR Underestimation
Value-at-Risk (VaR) calculations on leveraged portfolios must account for amplified tail risk. Standard VaR models often underestimate the true risk of leveraged positions because they assume normal distributions and don’t fully capture the impact of forced liquidation during market stress. A 5% VaR on an unleveraged portfolio might be 12-15% VaR on a 2x leveraged portfolio—not simply 10%.
Frequently Asked Questions
Maintenance margin is the minimum equity you need to keep a position open. The FINRA minimum is 25% for long positions, but most brokers set their house requirements at 30-40%. If your equity percentage falls below this threshold, your broker can force-liquidate your position immediately without warning.
Key difference: You can fall below the initial margin after purchasing without triggering a margin call. For example, if you buy $20,000 of stock with $10,000 cash (50% initial margin) and the stock falls to $16,000, your equity is now $6,000 ($16,000 – $10,000 loan), which is 37.5% of the market value—below the 50% initial margin but still above the 30% maintenance margin. No margin call. But if the stock continues to fall below the maintenance threshold, your broker can issue a margin call or force-liquidate; a sale at the threshold price is not guaranteed.
Example: You buy a stock at $100 with 50% initial margin and your broker has a 25% maintenance requirement.
Margin Call Price = $100 × (1 – 0.50) / (1 – 0.25) = $100 × 0.50 / 0.75 = $66.67
The unrounded threshold is $66.666…; at the displayed $66.67, equity is approximately 25.0%. Falling below the maintenance requirement permits a margin call or liquidation, but does not guarantee a sale at that price. This calculation assumes a constant loan and excludes interest. You should calculate this number before entering every margin trade so you know exactly how much downside you can tolerate. If the margin call price is only 10-15% below your purchase price, you’re over-leveraged.
Hypothetical example, before interest: You deposit $10,000, borrow $10,000, and buy $20,000 worth of stock. Overnight, the company announces fraudulent accounting and the stock gaps down 60% to $40/share before your broker can liquidate. Your position is now worth only $8,000. The broker liquidates at $8,000, but you still owe the $10,000 loan. You owe the broker $2,000 even after losing your entire $10,000 deposit. Total loss: -120%.
You remain liable for any debit balance after liquidation. The broker will demand immediate payment, and if you can’t pay, they may pursue collections or legal action. This is rare, but it’s a REAL risk that’s unique to margin trading. Cash accounts cannot have this problem—the worst you can lose in a cash account is 100% of your investment.
What your broker controls:
- Which securities to sell: The broker decides which positions to liquidate—you have no say
- How much to sell: They’ll sell as much as necessary to restore your account to compliance with margin requirements
- When to sell: Liquidation can happen at any time during market hours, often during periods of peak volatility
- At what price: Sales happen at prevailing market prices, which may include slippage, wide spreads, and illiquid conditions
You have zero control over this process once a margin call is triggered. Some brokers may give you a courtesy notification, but they are under no obligation to do so. Many traders discover they’ve been liquidated only when they log in and see their positions gone. This is why margin trading requires constant monitoring—you can’t set it and forget it.
Typical house rules: 30-40% maintenance for most stocks
Security-specific requirements:
- Low-priced stocks (under $5): Often 100% requirement (no margin allowed)
- Leveraged ETFs: Typically 75-100% maintenance
- Concentrated positions: If one position represents more than 20-30% of your account, brokers may impose higher requirements
- Volatile stocks: Brokers can increase requirements based on historical volatility, beta, or recent price movements
- Hard-to-borrow securities: Stocks with limited availability for short selling often have higher maintenance margins
Broker discretion: Requirements can change intraday without notice, especially during market stress. A stock that was marginable at 30% in the morning might suddenly require 100% (no margin) by afternoon due to increased volatility or company news. When this happens, you face an immediate margin call even if your positions haven’t moved.
Always check your broker’s margin handbook for current requirements on specific securities before trading.
Margin trading (buying on margin): Borrowing cash from your broker to buy securities. You hold a long position with leverage. Your potential loss is limited (theoretically) to the amount invested, though as discussed earlier, you can lose more than your deposit in gap scenarios.
Short selling: Borrowing securities from your broker to sell them, betting on a price decline. Your potential loss is unlimited because there’s no cap on how high a stock price can rise. If you short a stock at $50 and it rises to $500, you lose $450 per share—far more than your initial margin.
Key similarities: Both amplify risk, both accrue interest/fees (margin interest on borrowed cash for long margin; borrow fees for short selling), and both require a margin account with a broker.
Key differences: Long margin has limited (but amplified) downside; short selling has unlimited upside risk. Long margin benefits from dividends; short selling requires you to pay dividends to the lender of the shares.
Small retail balances (under $25,000): Approximately 11-13% annual at major brokers (as of February 2026)
Tiered rates for larger balances:
- $25,000-$100,000: ~9-10%
- $100,000-$500,000: ~7-8%
- $500,000-$1,000,000: ~6-7%
- $1,000,000+: ~5-6%
Rates are based on the broker’s base rate (which tracks the Federal Reserve’s benchmark rate) plus a spread. When the Fed raises or lowers rates, margin rates typically adjust within days.
Important notes:
- Interest accrues daily; unpaid interest added to the loan increases future interest charges
- Some brokers (Interactive Brokers, Robinhood Gold) offer significantly lower rates for all balance tiers
- Rates can vary even within the same broker based on account type (e.g., retail vs. institutional)
Always check your specific broker’s current margin rates before trading. Using the example’s hypothetical 11.8% annual rate on a constant $10,000 loan, simple-interest estimates are $3.23 per day or $98 per average month. Actual billing depends on your broker’s terms and whether interest is paid or added to the loan.
Key restrictions:
- You can only deduct up to the amount of your investment income (dividends, interest, and short-term capital gains)
- You cannot deduct margin interest against long-term capital gains unless you elect to treat those gains as ordinary income—which means giving up the preferential long-term capital gains tax rate (a major trade-off)
- You must itemize deductions on Schedule A. If you take the standard deduction, you can’t claim investment interest expense
- Any disallowed interest (amount exceeding your investment income) can be carried forward to future years
Example: You pay $1,500 in margin interest during the year and have $1,000 in dividend income. You can deduct $1,000 of the interest in the current year. The remaining $500 carries forward to the next year.
This is a complex tax topic. Consult a qualified tax professional for your specific situation. See IRS Publication 550 (Investment Income and Expenses) for details. This is NOT tax advice.
PDT requirements:
- You must maintain a $25,000 minimum equity in your account at all times (measured at the end of each trading day)
- If your equity falls below $25,000, you cannot execute any day trades until you restore the balance
- You can still hold positions and make non-day-trade transactions (overnight holds)
Important notes:
- The PDT rule applies to margin accounts only. Cash accounts are exempt from the PDT rule, but they’re subject to separate free-riding and good faith violation rules (you can’t trade with unsettled funds)
- PDT status typically remains once flagged. Many brokers allow removal requests after a period of no day trading (commonly 60-90 days), but this varies by firm policy
- This is a FINRA rule, separate from margin requirements, but it’s commonly confused with margin trading because both involve margin accounts and minimum balance requirements
Many traders mistakenly think the $25,000 minimum is a margin requirement—it’s not. It’s specifically a day trading restriction designed to protect retail traders from the risks of active day trading on leverage.
Disclaimer
Last reviewed: February 2026. This article is for educational and informational purposes only and does not constitute financial, investment, or tax advice. Margin regulations and broker policies can change intraday without advance notice. Regulation T and FINRA requirements are current as of the publication date, but brokers set their own house rules above these minimums.
Specific margin rates, maintenance requirements, and security-specific rules vary significantly by broker. Always consult your broker’s current margin handbook and margin disclosure statement before trading. Margin trading involves substantial risk of loss and is not appropriate for all investors. You can lose more than your initial investment.
Keep reading
Next in this series
Part 19 of 20 in Portfolio Analytics
Leveraged ETFs: What They Are, How They Work, and Why They Fail Long-TermMore in Portfolio Management
-
Investment Policy Statement & RRTTLLU Framework: Complete Guide
Learn what an investment policy statement (IPS) is, how to write one using the RRTTLLU framework, and why it is the cornerstone of the portfolio management…
-
Systematic vs Unsystematic Risk: What’s the Difference?
Learn the difference between systematic (market) risk and unsystematic (company-specific) risk, why diversification eliminates only one type…
-
Annualized Return (CAGR): Formula, Calculation, and Examples
Learn how to calculate annualized returns (CAGR) and understand the critical difference between geometric mean and arithmetic mean for measuring multi-year…