Information Ratio and Tracking Error: Active Management Guide
Table of Contents
The Information Ratio and tracking error are the two most important metrics for evaluating active fund managers. Tracking error measures how much a portfolio’s returns deviate from its benchmark, while the Information Ratio measures whether those deviations consistently produce outperformance. Together, they answer a critical question: is the active risk a manager takes being rewarded with genuine skill, or is it just expensive noise? Whether you’re choosing between active and passive management, evaluating a mutual fund, or studying for the CFA exam, understanding both metrics is essential for assessing whether active management fees are justified.
What is the Information Ratio?
The Information Ratio (IR) measures risk-adjusted active return — how much excess return a portfolio generates per unit of active risk taken relative to a benchmark. In essence, it answers one critical question:
Does this manager consistently beat their benchmark, or are their results just noise?
Unlike the Sharpe Ratio (which measures return per unit of total volatility) or the Treynor Ratio (which measures return per unit of systematic risk), the Information Ratio isolates consistency of active bets. It’s the go-to metric for deciding whether an active manager’s performance justifies their fees.
A portfolio can have a high Sharpe Ratio (good total risk-adjusted return) but a low or negative Information Ratio (doesn’t beat its benchmark). The IR summarizes historical active return per unit of active risk; statistical evidence and benchmark quality still matter when assessing skill.
The Information Ratio Formula
The Information Ratio is calculated as active return divided by tracking error:
Where:
- Rp — portfolio return (annualized)
- Rb — benchmark return (annualized)
- Rp – Rb — active return (arithmetic average excess return vs. benchmark, not CAGR)
- TE — tracking error (standard deviation of active returns, annualized)
Critical: The numerator and denominator must use the same periodicity — both annualized or both monthly. Under the usual uncorrelated-return scaling assumption, annualized IR equals monthly IR multiplied by √12; the two reported ratios are therefore different. Mixing annual active return with monthly tracking error without proper scaling is a common calculation mistake.
The Information Ratio is typically calculated from 36-60 months of monthly return data. For investor decision-making, IR should usually be calculated net of fees (after expense ratios), not gross, since investors care about what they actually earn.
Tracking Error Explained
Before judging what a good Information Ratio is, you need to understand the denominator: tracking error. It’s the foundation of active risk measurement and the key to interpreting IR correctly.
Tracking Error (TE) is the standard deviation of the difference between portfolio and benchmark returns. It measures the consistency or volatility of active bets, not just the magnitude of outperformance in a single period.
Tracking error is not the absolute difference between portfolio and benchmark return in one period. It measures how active returns vary around their average. Consider these two hypothetical paths:
| Month (number) | Variable (pp) | Steady (pp) |
|---|---|---|
| 1 | 8 | 2 |
| 2 | -4 | 2 |
| 3 | 8 | 2 |
| 4 | -4 | 2 |
| 5 | 8 | 2 |
| 6 | -4 | 2 |
Hypothetical six-month paths using the article's +8/-4 and +2 examples. Tracking error uses the sample standard deviation.
Both paths average +2 percentage points of monthly active return. Sample monthly tracking error is 0 for Steady and 6.57 percentage points for Variable. A nonzero average return can therefore coexist with zero tracking error; IR is undefined when its denominator is zero.
| Annualized tracking error (%) | Fund Style | Interpretation |
|---|---|---|
| < 1% | Passive / Index | Close benchmark replication; residual TE from sampling, transaction costs, and cash drag |
| 1% – 2% | Low-active / Enhanced index | Minimal active bets; small tilts around the benchmark to capture marginal alpha |
| 2% – 6% | Diversified active | Typical actively managed fund with meaningful deviations from benchmark |
| > 6% | High-conviction / Concentrated | Large active bets; portfolio looks very different from benchmark |
Note: These ranges are heuristics for equity funds benchmarked to broad indices like the S&P 500 or MSCI World. Tracking error thresholds vary by asset class — fixed income funds typically have lower TE than equity funds, and emerging market strategies tend to have higher TE due to greater volatility and liquidity constraints.
Benchmark Quality Matters: For meaningful tracking error, the benchmark must match the fund’s mandate:
- Style — growth, value, or blend
- Market cap — large-cap, mid-cap, or small-cap
- Geography — U.S., International, Emerging Markets
- Fund’s stated mandate — the benchmark should align with what the fund claims to do
If an “active” fund has very low tracking error (<1-2%) combined with high fees, it’s likely a closet indexer — charging active management fees without providing real active management. Active Share (the percentage of holdings different from the benchmark) is another useful metric for identifying closet indexers.
Tracking Error vs Tracking Difference
A common source of confusion is conflating tracking error with tracking difference. They measure different things:
- Tracking error — the volatility (standard deviation) of active returns over time. It measures how unpredictably a fund deviates from its benchmark.
- Tracking difference — the cumulative return gap between the fund and its benchmark over a period (often annualized for comparison). It measures the total drag on returns.
This distinction matters because expense ratios primarily affect tracking difference, not tracking error. A fund charging 0.50% per year will consistently underperform a zero-cost benchmark by roughly that amount — a predictable, steady drag that shows up as negative tracking difference. But because the fee impact is nearly constant each period, it adds very little to the variability of active returns and therefore contributes minimally to tracking error. The sources that drive tracking error are the ones that introduce unpredictable return differences between fund and benchmark.
Sources of Tracking Error
Several factors cause a fund’s returns to deviate unpredictably from its benchmark:
- Sampling and optimization — Many index funds hold a representative subset of the index rather than every security (especially for broad indices with thousands of constituents). This introduces return differences that vary from period to period.
- Transaction costs and market impact — Trading costs from index rebalancing, corporate actions, and fund flows create variable drag that differs each period.
- Cash drag variability — Funds hold cash for redemptions and pending dividend reinvestment. The amount fluctuates, creating unpredictable performance differences versus a fully invested benchmark.
- Rebalancing timing — Index additions, deletions, and weight changes don’t happen instantaneously in the fund. Timing differences between the index’s effective date and the fund’s actual trades create short-term return gaps.
- Dividend and tax withholding timing — Differences in when dividends are received, reinvested, or subject to withholding taxes (especially for international indices) introduce period-to-period variability.
Real-world example: The Vanguard S&P 500 ETF (VOO) typically has a tracking difference of roughly -0.03% per year (driven almost entirely by its 0.03% expense ratio) but a tracking error of only about 0.02-0.04% annualized. The small TE reflects excellent full-replication and minimal cash drag. By contrast, an international index fund like the Vanguard FTSE Emerging Markets ETF (VWO) may show tracking error of 0.30-0.50% due to sampling, time-zone settlement lags, and dividend withholding variability — even though its tracking difference is also largely fee-driven.
When evaluating passive funds (index funds and ETFs), focus on tracking difference to assess total cost of ownership, and tracking error to assess replication quality. A fund with low tracking difference but high tracking error is delivering the right average return but with unpredictable deviations — which can matter for rebalancing and tax-loss harvesting timing.
Ex-Ante vs Ex-Post Tracking Error
Tracking error can be measured in two fundamentally different ways:
- Ex-post tracking error — calculated from historical active returns (what actually happened). This is the standard definition used throughout this article and in most performance reports. It’s backward-looking and tells you how much a portfolio’s returns actually deviated from its benchmark.
- Ex-ante tracking error — a forward-looking estimate predicted by factor risk models (such as Barra or Axioma). Portfolio managers use ex-ante TE during portfolio construction to set risk budgets and ensure active risk stays within target bounds.
The two measures can diverge significantly, especially during market regime shifts or periods of unusual correlation. A portfolio might have low ex-ante TE (the model predicts low active risk) but experience high ex-post TE when unexpected events cause factors to behave differently than the model assumed. This divergence reflects model misspecification, not necessarily poor management — it’s a known limitation of factor-based risk models.
What Is a Good Information Ratio?
The Information Ratio summarizes average active return relative to its variability. A larger positive IR means more active return per unit of tracking error; it does not by itself establish skill. The bands below are qualitative rules of thumb, not statistical significance cutoffs.
| Annualized Information Ratio | Quality Rating | Interpretation |
|---|---|---|
| IR < 0 | Negative | Negative average active return vs. benchmark |
| 0.0 – 0.25 | Poor | Small positive average active return relative to active risk |
| 0.25 – 0.50 | Fair/Average | Modest active return relative to active risk; assess fees and uncertainty |
| 0.50 – 0.75 | Good | Stronger historical risk-adjusted active return; verify persistence and uncertainty |
| 0.75 – 1.00 | Excellent | High historical active return relative to active risk |
| > 1.00 | Exceptional | Very high historical ratio; verify benchmark, sample length, and denominator |
With independent, identically distributed (IID) monthly active returns, the test statistic is approximately t = IRannual × √Y, where Y = number of months / 12. For positive estimated performance, a two-sided 95% normal-approximation screen is IRannual > 1.96 / √Y; a one-sided 95% screen uses 1.645. These are approximate cutoffs. An exact IID-normal test with estimated volatility uses Student’s t critical values; serial correlation and manager selection can also change inference.
| Track record (years) | 95% cutoff (annual IR) |
|---|---|
| 3 | 1.132 |
| 4 | 0.98 |
| 5 | 0.877 |
| 6 | 0.8 |
| 7 | 0.741 |
| 8 | 0.693 |
| 9 | 0.653 |
| 10 | 0.62 |
Analytical illustration, 3–10 years: 1.96/√years. Two-sided 95% normal approximation with IID monthly active returns.
Three years requires an annualized IR of about 1.13, and five years about 0.88 under this approximation. An annualized IR of 0.50 alone does not meet this 95% screen over either period.
Ex-Post vs. Ex-Ante IR: The historical (ex-post) IR tells you what happened. The forecast (ex-ante) IR is what you expect going forward. Managers’ ex-post IRs often don’t persist — a high IR over one 5-year period may evaporate in the next. This is why statistical significance testing and long evaluation periods matter.
Watch for Instability: IR can look artificially high when tracking error is very small. A fund with 0.5% active return and 0.3% tracking error would have an IR of 1.67, which looks exceptional — but such small denominators make the estimate unstable. Always interpret IR in the context of the tracking error magnitude.
Information Ratio Example: Active Large-Cap Fund
Let’s walk through a hypothetical example of an actively managed large-cap fund evaluated over 5 years (60 months) against a mandate-appropriate S&P 500 Total Return Index. The active returns are gross of fund fees so we can show the fee adjustment explicitly.
Assume a hypothetical large-cap fund whose mandate fits this benchmark, with 60 monthly observations:
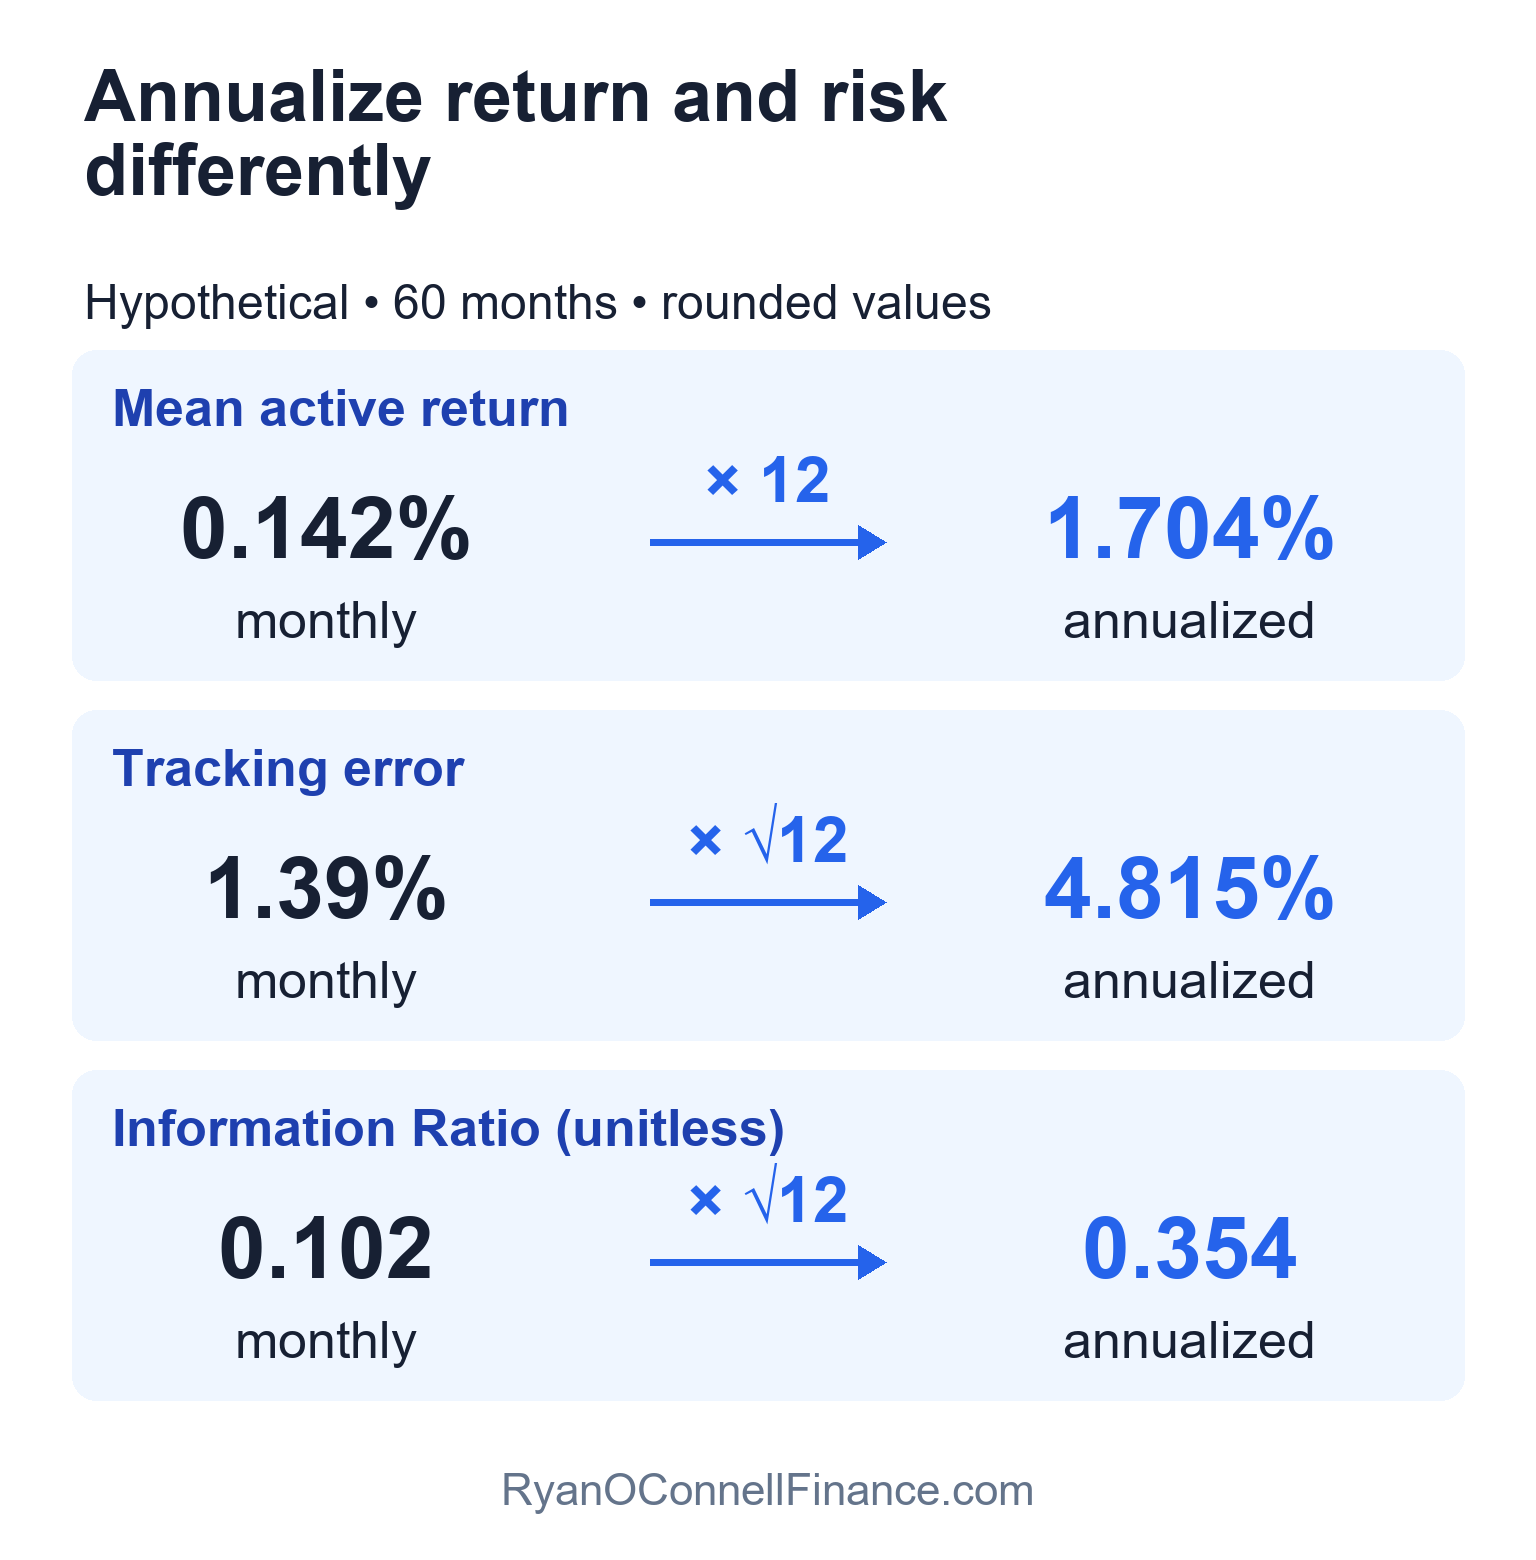
The mean active return scales by 12, while its standard deviation scales by √12. Their ratio therefore scales by √12 as well. The steps below round the annual return and tracking error for presentation.
Step 1: Calculate Active Return
Calculate the fund’s monthly return minus the S&P 500 return for each of the 60 months. The arithmetic mean of these monthly differences is 0.142%. Annualize by multiplying by 12: 0.142% × 12 = 1.7% per year.
Step 2: Calculate Tracking Error
Use the sample standard deviation of those same 60 monthly active returns: 1.39% per month. Assuming uncorrelated monthly active returns, annualize as follows:
TE = 1.39% × √12 = 1.39% × 3.464 = 4.8% per year
Step 3: Calculate Information Ratio
IR = 1.7% / 4.8% = 0.354
Interpretation: The annualized IR is about 0.35 before fees. Over 5 years, its approximate test statistic is 0.354 × √5 = 0.79, below 1.96 for the two-sided 95% normal-approximation screen. The positive historical active return does not establish statistical evidence of skill. For investor evaluation:
- Separate historical gross outperformance from evidence of persistent skill
- Evaluate returns net of fees and against a benchmark that fits the mandate
- With a 1.2% annual fund expense ratio, the 1.7% gross active return becomes approximately 0.50% net active return versus the gross benchmark. If fees are the only index-fund drag, an index fund charging 0.05% would have approximately -0.05% net active return. The active fund’s advantage over that index fund is then 0.55 percentage points per year
For comparison, an index fund with a steady fee drag has negative net active return against a gross benchmark. Its IR is negative when tracking error is positive, but its magnitude depends on that tracking error; if tracking error is zero, IR is undefined. For passive funds, tracking difference and replication quality are usually more informative than IR.
Information Ratio vs Sharpe Ratio: Key Differences
The most common confusion in portfolio evaluation is conflating the Information Ratio with the Sharpe Ratio. They measure fundamentally different aspects of performance and should be used for different purposes.
Information Ratio
- Formula: (Rp – Rb) / TE
- Risk measure: Tracking error (active risk — volatility of deviations from benchmark)
- Numerator: Active return (return relative to specific benchmark)
- What it measures: Consistency of beating a specific benchmark
- Benchmark dependency: Changes if you change the benchmark
- Best use case: Evaluating active fund managers vs. their stated benchmark
Sharpe Ratio
- Formula: (Rp – Rf) / σp
- Risk measure: Standard deviation (total risk — all volatility)
- Numerator: Excess return over risk-free rate
- What it measures: Return per unit of total volatility
- Benchmark dependency: Benchmark-independent (only depends on risk-free rate)
- Best use case: Standalone investments or comparing across different asset classes
The fundamental difference is the denominator (risk measure) and reference point (numerator):
- Sharpe Ratio asks: “How much return am I earning per unit of total volatility compared to a risk-free investment?” It’s an absolute measure of risk-adjusted return.
- Information Ratio asks: “How consistently is this manager beating their benchmark?” It’s a relative measure focused on active management skill.
Example scenario: A fund could have a high Sharpe ratio (earning excellent risk-adjusted returns in absolute terms) but a low or negative IR (failing to beat its specific benchmark consistently). This would suggest the fund is a good investment overall, but the benchmark itself is strong, so passive indexing might be preferable.
Conversely, a fund could have a mediocre Sharpe ratio but a high historical IR. This indicates higher average active return per unit of tracking error in the sample; it does not by itself establish manager skill. Assess statistical significance, benchmark fit and persistence alongside total risk.
When to use each:
- Use Sharpe when comparing investments across asset classes (stocks vs. bonds) or evaluating a standalone portfolio’s efficiency
- Use IR when comparing active managers to their benchmarks or deciding between active and passive management within the same asset class
Most professional investors use both: Sharpe for absolute quality, IR for relative skill.
Information Ratio vs Treynor Ratio vs Jensen’s Alpha
The Information Ratio is one of several metrics for evaluating manager performance. Here’s how it compares to two other common measures:
| Metric | Formula | What It Measures |
|---|---|---|
| Information Ratio | (Rp – Rb) / TE | Consistency of beating benchmark (active risk-adjusted return) |
| Treynor Ratio | (Rp – Rf) / β | Return per unit of systematic risk |
| Jensen’s Alpha | Rp – [Rf + β(Rm – Rf)] | Absolute excess return vs. CAPM prediction |
Key distinction: The Information Ratio and Treynor Ratio are ratios (rate-based measures), while Alpha is an absolute return difference (level-based). IR is best for manager selection against a benchmark, not standalone asset ranking. Use IR to decide if an active manager is worth the fees; use Alpha to measure the absolute value added; use Treynor when you want to focus on systematic risk only.
The M² Ratio and Active Management
The M² Ratio (Modigliani-Modigliani) is a complement to the Information Ratio. While IR is expressed as a ratio, M² converts the Sharpe Ratio into percentage return terms for easier comparison. The M² Active variant adjusts a portfolio to the same volatility as the benchmark and shows what the return would be.
M² is particularly useful when presenting performance to clients or stakeholders who find ratios hard to interpret. It answers the question: “If this portfolio had the same risk as the benchmark, what would its return be?”
Common Mistakes When Using the Information Ratio
Even experienced investors make critical errors when calculating and interpreting the Information Ratio. Avoid these common pitfalls:
A high historical IR can reflect chance. For annualized IR, the two-sided 95% normal-approximation screen under IID monthly returns is IR > 1.96/√Y, where Y is years of data. The earlier chart gives the 3- and 5-year cutoffs; count 36 months as 3 years, not 36 years. Longer histories help, but autocorrelation, changing strategies and multiple manager comparisons can make a simple screen unreliable.
1. Using Too-Short Evaluation Periods — Evaluating IR over 12-24 months and making long-term investment decisions based on that data is dangerous. One or two good years can be driven by market conditions favoring a manager’s style (e.g., growth stocks outperforming during a tech rally), not by skill. As soon as conditions change, the IR can collapse. Academic research consistently shows that manager skill only becomes distinguishable from luck over multi-year horizons. Use a minimum of 3 years, ideally 5+ years of monthly returns.
2. Mixing Frequencies/Annualization — Keep the numerator and denominator on the same periodicity, and state the IR’s reporting frequency. With 2.0% annual arithmetic active return and 0.40% monthly tracking error, annual TE is 0.40% × √12 = 1.39%, giving annualized IR ≈ 1.44. Alternatively, monthly mean active return is 2.0% / 12, giving monthly IR ≈ 0.417; multiply that ratio by √12 to obtain annualized IR. Dividing 2.0 by 0.40 directly gives 5.0 and overstates the annualized IR by √12. These conversions assume uncorrelated monthly active returns.
3. Wrong Benchmark Selection — Calculating IR using an inappropriate benchmark makes the result meaningless. Using the S&P 500 to evaluate a small-cap fund, or using a broad market index to evaluate a sector-focused fund, tells you nothing about manager skill — it’s just measuring the style difference. Always use the fund’s stated benchmark or the most appropriate style-matched index. For U.S. large-cap growth funds, use the S&P 500 or Russell 1000 Growth. For small-cap value, use the Russell 2000 Value. Benchmark must match the fund’s mandate (style, market cap, geography).
4. Confusing IR with Sharpe Ratio — Using IR and Sharpe interchangeably is a fundamental conceptual error. They measure different things: Sharpe measures total risk-adjusted return (return per unit of total volatility), while IR measures active risk-adjusted return (return per unit of active risk vs. benchmark). A fund can have a high Sharpe (efficient in absolute terms) but a low/negative IR (doesn’t beat its benchmark). Always use the right metric for the right question.
5. Ignoring Fees in the Comparison — Establish whether returns are gross or net before calculating IR. If a fund has gross annual active return of 1.5% and 5% tracking error, its gross IR is 0.30. Deducting a 1.2% annual expense ratio gives approximately 0.30% net active return and a net IR of 0.06 if tracking error is unchanged. If fees are the only index-fund drag, an index fund charging 0.05% would trail the gross benchmark by about 0.05%, so the active fund’s advantage over that index fund is approximately 0.35 percentage points per year. If reported active returns are already net of fees, do not subtract the expense ratio again.
Limitations of the Information Ratio
While the Information Ratio is an excellent tool for evaluating active managers, it has several important limitations that every investor should understand:
1. Assumes Consistent Active Management Style — The Information Ratio assumes the manager maintains a consistent investment process and style throughout the measurement period. If a manager changes strategy mid-period (e.g., shifts from growth to value, or from concentrated to diversified), the historical IR becomes less relevant for predicting future performance. Similarly, if a key portfolio manager leaves and is replaced, the historical IR reflects the prior manager’s skill, not the new manager’s. Always investigate manager tenure and strategy consistency before relying on historical IR.
2. Backward-Looking Measure — Like all historical performance metrics, IR tells you what happened, not what will happen. Past outperformance does not guarantee future results — especially in active management, where skill can degrade due to manager distraction, asset bloat (large AUM makes it harder to be nimble), or market regime changes. A manager who excelled in a low-rate growth environment may struggle in a high-rate value environment. Use IR as a starting point, not a decision rule.
3. Benchmark Dependency — IR is only as meaningful as the benchmark is appropriate. Closet indexers can game IR by choosing a slightly different benchmark than their actual holdings. For example, a fund that holds mostly large-cap growth stocks but benchmarks to the S&P 500 (a blend index) may show a positive IR simply due to growth outperforming value, not because of manager skill. Verify that the fund’s holdings actually match the benchmark’s universe. Check the fund’s active share (percentage of holdings different from the benchmark) — a low active share (<60%) combined with high fees is a classic closet indexing red flag.
4. Doesn’t Account for Risk-Adjusted Utility — IR measures consistency of outperformance but doesn’t tell you whether taking active risk was worth it from a utility (investor happiness) perspective. A fund with a high IR might still have higher maximum drawdowns or tail risk than the benchmark, which may not be acceptable to risk-averse investors. A manager could have a high IR by taking small, consistent bets that add up over time, or by taking large, volatile bets that happened to work out. Supplement IR with other risk metrics like maximum drawdown and Value at Risk.
5. Can Be Volatile Across Time Windows — IR estimates can fluctuate significantly depending on the start and end dates of the measurement window. Rolling 5-year IRs for the same fund can vary widely — what looks like a 0.70 IR in one window might be 0.30 in a different window just 12 months later. This instability makes it dangerous to base decisions on a single-point IR estimate. Report IR with context: specify the measurement period, and ideally show rolling IR over time to illustrate consistency.
The Information Ratio is an excellent starting point for evaluating active managers, but it should never be your only metric. Combine it with the Sharpe ratio, Jensen’s alpha, maximum drawdown, and qualitative factors like team stability, investment process, fee structure, and capacity constraints. No single number tells the full story of manager quality. Always verify sufficient track record length (5+ years preferred) and ensure the benchmark matches the fund’s actual mandate.
For a deeper dive into performance evaluation metrics with real-world examples, see our Portfolio Analytics & Risk Management course, which covers Information Ratio, Sharpe, Treynor, and alpha in an integrated framework.
Frequently Asked Questions
Disclaimer
This article is for educational and informational purposes only and does not constitute investment advice. Information Ratio values and fund performance data cited are illustrative examples and may differ based on the data source, time period, and methodology used. Always conduct your own research and consult a qualified financial advisor before making investment decisions.
Keep reading
Next in this series
Part 13 of 20 in Portfolio Analytics
Time-Weighted vs Money-Weighted Return: Key Differences ExplainedMore in Portfolio Management
-
Investment Policy Statement & RRTTLLU Framework: Complete Guide
Learn what an investment policy statement (IPS) is, how to write one using the RRTTLLU framework, and why it is the cornerstone of the portfolio management…
-
Systematic vs Unsystematic Risk: What’s the Difference?
Learn the difference between systematic (market) risk and unsystematic (company-specific) risk, why diversification eliminates only one type…
-
Annualized Return (CAGR): Formula, Calculation, and Examples
Learn how to calculate annualized returns (CAGR) and understand the critical difference between geometric mean and arithmetic mean for measuring multi-year…